Delaware VA manufactured home loans let eligible veterans and active-duty service members buy a single-wide, double-wide, or multi-wide manufactured home with $0 down and a 30-year fixed rate – as long as the home sits on a permanent foundation, on land you own, and is titled as real property. Homes on leased land are not eligible and need a chattel loan instead. Current as of June 2026.
If you are a veteran or active-duty service member thinking about buying a manufactured home in Delaware, your VA home loan benefit can be one of the strongest financing tools you have. I’m John Thomas, NMLS #38783, a mortgage loan officer with Primary Residential Mortgage in Newark, and I help buyers across Delaware and Maryland use the VA loan to finance single-wide, double-wide, and multi-wide manufactured homes. On a qualifying manufactured home, the VA loan is the same powerful benefit it is on a site-built house – $0 down, no monthly mortgage insurance, and competitive rates – as long as the home meets a few extra property rules. If you want the full picture of the benefit first, start with my guide to Delaware VA Loans, then come back here for the manufactured-home specifics. Ready to begin? Call the John Thomas Team at 302-703-0727 or apply online today.
Start Your Delaware VA Manufactured Home Loan
Call, schedule a free 30-minute review, or apply online – whichever fits your day.
Table of Contents
Why Use a VA Loan for a Manufactured Home in Delaware?
Manufactured homes are common across Kent and Sussex County Delaware, and pairing one with a VA loan can stretch your buying power further than almost any other financing path. Here is why veterans choose it:
- $0 down payment. With full VA entitlement, most eligible buyers finance up to 100% of the purchase price with no down payment.
- No monthly mortgage insurance. Unlike FHA or low-down conventional loans, the VA loan has no monthly mortgage insurance, which keeps the payment lower.
- Competitive rates and strong borrower protections. VA loans come with competitive interest rates and consumer protections built into the program.
- More home for your money. A manufactured home often costs less per square foot than a comparable site-built home, so your VA benefit can reach a larger or newer home.
- Single-wide, double-wide, and multi-wide all qualify when the home meets the VA’s program rules (covered below).
Who Qualifies for a Delaware VA Manufactured Home Loan?
To use a VA loan you need to meet both VA service requirements and standard financial qualifications (income, credit history, residual income, and underwriting). On the service side, you may be eligible if you fall into one of these groups:
- Veterans, active-duty service members, and those with prior service who meet the minimum service standards (the exact requirement varies by the era and type of service), or
- National Guard or Reserve members who meet the qualifying service criteria, or
- Qualified surviving spouses as defined by VA guidelines.
Occupancy: The home must be your primary residence, and you will certify your intent to occupy it (generally within 60 days of closing) per VA guidelines.
Credit: The VA does not publish a single minimum credit score. Most lenders apply their own minimums, often around 620, but Primary Residential Mortgage follows the VA’s own credit standards and does not impose a blanket minimum-score overlay on VA loans – approval depends on your full borrower profile, including credit history, income, residual income, and the property itself.
Certificate of Eligibility (COE): What You Need
The COE tells your lender that the VA has confirmed your VA entitlement. You can request it through your lender (fastest in most cases) or directly from the VA. The documentation depends on your status:
- Veterans / former service: Your DD-214 (use the Member-4 or service copy that shows the character of your service).
- Active-duty service members: A Statement of Service signed by your commanding officer or personnel office.
- National Guard or Reserve members: Your NGB-22 or NGB-23, or a Reserve points statement.
- Surviving spouses: Follow VA guidelines and provide the required supporting documents.
Not sure where to start? I can help you pull your COE quickly – just call me at 302-703-0727.
What Property Requirements Must a Manufactured Home Meet?
The VA will finance a single-wide, double-wide, or multi-wide manufactured home as long as the property meets all of the following:
- Classified as real property. The home must be permanently affixed to a foundation, the personal-property (vehicle) title must be retired, and the home must be legally classified and taxed as real estate rather than personal property. In Delaware, your title company handles the title conversion as part of closing.
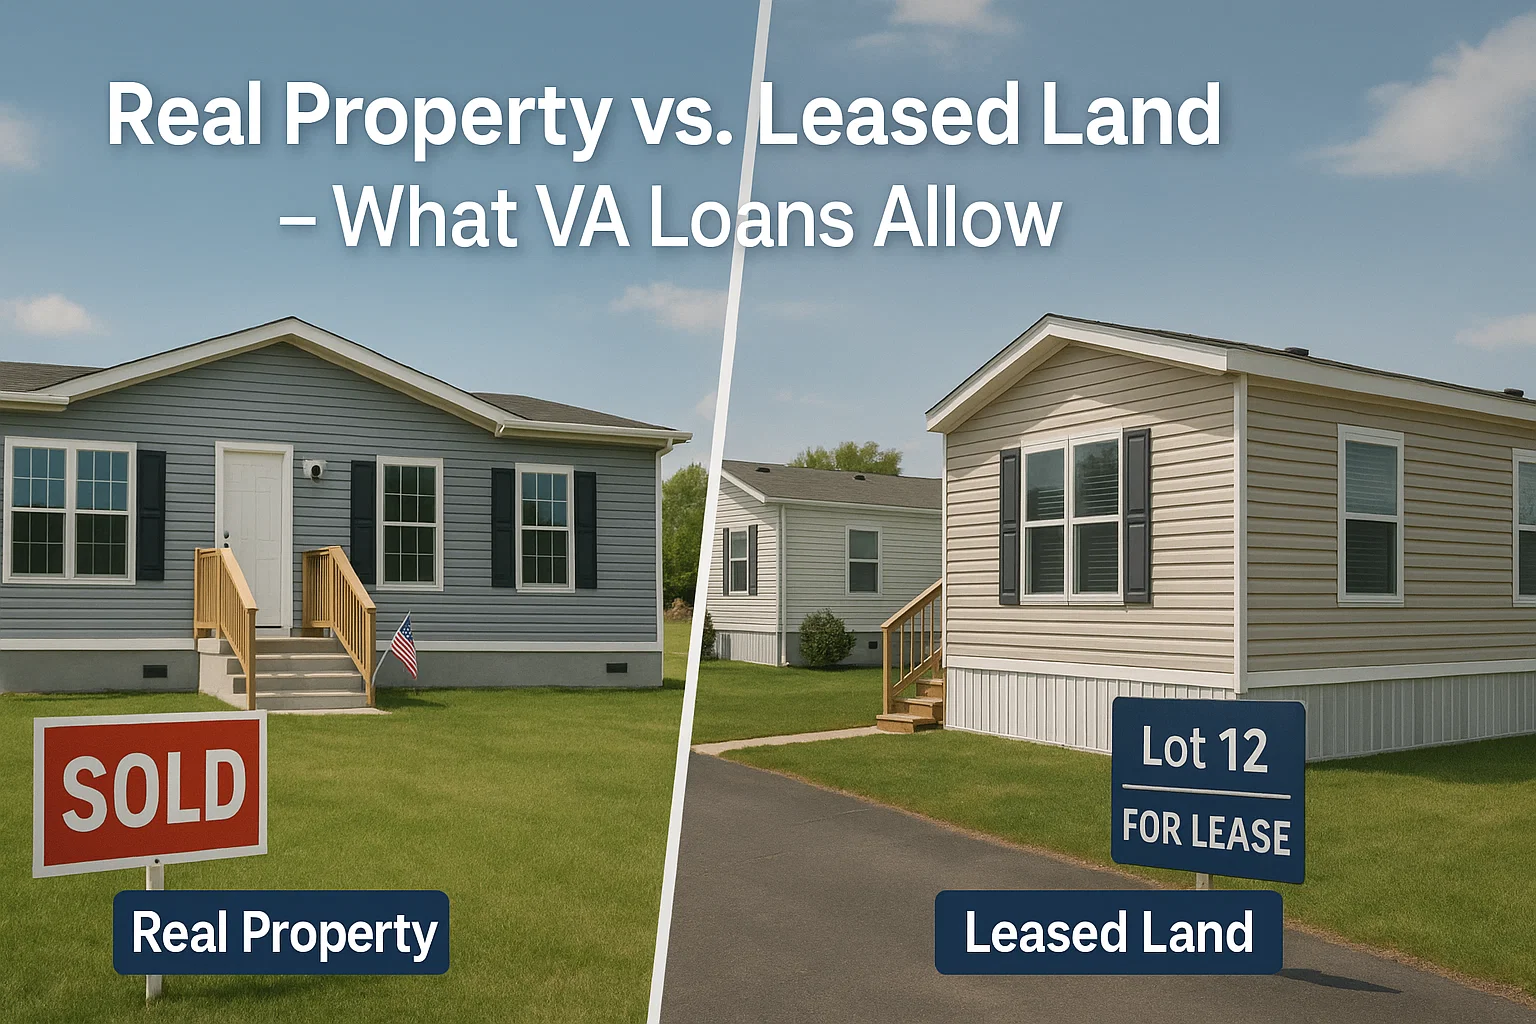
- Land ownership. You must own the land – or be buying it together with the home in the same transaction. A home on rented or leased land does not qualify for a VA loan; that situation needs a chattel loan instead (more in Mobile Home Loans on Leased Land).
- HUD code compliance. The home must comply with the federal Manufactured Home Construction and Safety Standards, which took effect June 15, 1976. It must carry HUD certification labels (the red tags) and a Data Plate, or the lender must be able to verify they were issued.
- Permanent foundation certification. Most VA files require a licensed engineer’s certification that the foundation meets HUD’s Permanent Foundations Guide for Manufactured Housing. This inspection typically runs a few hundred dollars and is usually ordered around the appraisal.
- Minimum size. The home generally must have at least 400 square feet of living area for a single-wide, or 700 square feet for a double-wide.
- VA Minimum Property Requirements (MPRs). The property must be safe, structurally sound, and sanitary – with working mechanical systems, safe utilities, proper access, and no obvious health or safety hazards.
A practical tip: before you pay for an appraisal or engineer’s report, confirm with the county that the home is (or can be) titled as real property. Catching a titling problem early saves time and money. For a broader overview of manufactured-home financing beyond VA, see Delaware Manufactured Home Loans.
Before You Make an Offer, Confirm These 5 Things
- Is the home on land you own (or will buy in the same purchase)?
- Is it titled – or can it be titled – as real property?
- Was it built after June 15, 1976?
- Are the HUD certification labels and the interior Data Plate present (or verifiable)?
- Can the foundation pass a licensed engineer’s certification?
If you can answer yes to all five, a VA loan may be worth reviewing. Not sure? Send me the listing before you spend money on inspections and I will help you check the land, title, HUD label and Data Plate, and the foundation path.
Where VA Manufactured Home Deals Fall Apart in Delaware
Most VA manufactured home files that fall through do not fail because of the buyer – they fail because of the property paperwork. These are the issues I check for early so we catch them before you spend money:
- Title never converted to real property. If the personal-property (vehicle) title was never retired, the home is still legally personal property and a VA loan cannot attach. In Delaware your title company handles the conversion – confirm the county records before the appraisal.
- Missing HUD label or Data Plate. If the red HUD certification label or the interior Data Plate is missing, the file can usually still proceed – you can request a Label Verification Letter from HUD’s labeling contractor, the Institute for Building Technology and Safety (IBTS), which most lenders accept in place of a missing label. Catching this before the appraisal avoids a delay.
- The home has been moved more than once. Most lenders will not finance a manufactured home that has been relocated from its original installation site. This is a widespread lender overlay rather than an absolute VA rule – the cleanest files are homes moved only once, from the factory to their current permanent site. A previously relocated home is one of the most common disqualifiers, so flag it early.
- Foundation will not pass certification. A temporary or non-compliant setup designed for relocation will not meet HUD’s Permanent Foundations Guide. A licensed engineer’s certification is what most VA files need.
- Appraisal or MPR problems. Safety, structural, or utility issues that fail VA Minimum Property Requirements can stall a file until they are repaired and re-inspected.
Manufactured homes are most common in rural Kent and Sussex County Delaware – around Dover, Milford, Georgetown, Seaford, Millsboro, Laurel, and Harrington – where buyers often already own or are buying the land. The CFPB confirms that VA-guaranteed loans are available for manufactured homes; the work is making sure the specific property clears these checks. Send me the listing and I will help you read the land, title, and foundation path before you commit.
Can You Really Get a 30-Year Fixed VA Loan on a Single-Wide?
Yes – and this is where a lot of online advice gets it wrong. You will see articles flatly state that VA loans on manufactured homes are capped at 20 years. That advice is describing the old VA manufactured-home-only program (sometimes called Title I), where the home is financed as personal property without the land. That program has a low loan cap and a shorter term, and very few lenders even offer it.
When the manufactured home is permanently affixed, on land you own, and titled as real property, it is financed as a standard VA purchase loan – the same loan a veteran uses on a site-built house. That means a 30-year fixed-rate term is available even for a single-wide, with no VA loan limit when you have full entitlement, provided the home and your file meet VA property standards and underwriting. Individual lenders may add their own conditions (minimum scores, reserves, home age, or extra foundation documentation), but the 30-year fixed is on the table for eligible real-property manufactured homes.
The takeaway: if the home is titled as real estate, follows HUD and VA rules, and your qualifications line up, a 30-year fixed VA loan – single-wide included – is realistic. This applies to the real-property VA purchase loan path – not personal-property or chattel financing – and lender and investor guidelines still apply.
Illustration: Say an eligible veteran with full entitlement buys a $250,000 double-wide on a lot they own. On the real-property VA purchase path, a buyer in that situation may be able to finance up to 100% of the purchase price with no down payment and no monthly mortgage insurance – subject to credit, income, residual income, the VA appraisal, property eligibility, and full underwriting. Your actual terms depend on your file; let’s run your specific numbers together.
Single-Wide vs. Double-Wide vs. Multi-Wide: What Is Eligible?
All three configurations can be VA-eligible when they meet the same real-property, HUD-code, foundation, and MPR rules above:
- Single-wide – eligible; generally needs at least 400 square feet of living area.
- Double-wide – eligible; generally needs at least 700 square feet of living area.
- Multi-wide (triple-wide and larger) – eligible under the same standards.
The number of sections does not by itself decide eligibility. What matters is that the home is titled as real property on owned land, built after June 15, 1976, on a certified permanent foundation, and able to pass the VA appraisal.
Manufactured vs. Modular Homes: What Is the Difference for VA?
It is worth knowing which kind of home you are buying, because the VA treats them a little differently:
- Manufactured homes are built to the federal HUD code, carry HUD red tags, and must clear the extra requirements on this page (real-property titling, permanent foundation certification, HUD labels).
- Modular homes are built in sections to the same state and local building codes as a site-built house and assembled on a permanent foundation. The VA generally treats a modular home like standard construction once it is set, so it usually faces fewer manufactured-home-specific hurdles.
If you are not sure which category a home falls into, send me the listing and I will help you confirm it before you make an offer.
VA vs. FHA vs. USDA vs. Chattel for Delaware Manufactured Homes
The VA loan is usually the strongest path for a veteran buying a real-property manufactured home – but it helps to see it next to the alternatives. Many Delaware manufactured-home buyers qualify for more than one of these.
| Program | Down payment | Monthly mortgage insurance | Land / titling | 30-year fixed? | Best for |
|---|---|---|---|---|---|
| VA (this page) | $0 with full entitlement | None | Must own land; titled as real property | Yes | Eligible veterans and service members |
| FHA | From 3.5% | Yes | Real property on owned land | Yes | Buyers without VA eligibility or with lower credit |
| USDA | $0 in eligible rural areas | Yes (guarantee fee) | Real property in a USDA-eligible area (much of rural Kent and Sussex) | Yes | Buyers within USDA income limits in rural Delaware |
| Chattel | Varies | N/A | Home only – leased land or park (personal property) | No (shorter terms) | Homes on leased land that cannot be titled as real property |
What this means for you: if you own (or are buying) the land and the home can be titled as real property, VA is almost always your best option as a veteran. If the home is on leased land or in a park, VA is not available and a chattel loan is the path – which is a different conversation we are happy to have.
How the VA Manufactured Home Loan Process Works
Here is how I walk Delaware veterans through a manufactured-home purchase from start to closing:
- Check eligibility and pull your COE. I verify your service eligibility and request your Certificate of Eligibility from the VA.
- Get pre-approved. We review your income, credit, residual income, and payment comfort to set a realistic price range and a plan.
- Vet the property. I work with your real estate agent and the seller to confirm the home and its foundation paperwork match VA and HUD rules – titling, HUD tags, Data Plate, and foundation certification – before you spend money on inspections.
- Appraisal and underwriting. We order the VA appraisal and underwrite your file with a VA underwriter, update you weekly, and resolve any conditions quickly.
- Clear to close. My team handles the details so you can focus on moving in.
Want to know what the monthly payment might look like? Start with my guide to Understanding Your Mortgage Payment, then call me and we will run your specific numbers.
Documents You Will Need to Submit
- Your COE (I can help you obtain it)
- Government-issued ID and proof of military service (for example, DD-214 or Statement of Service)
- Most recent 30 days of pay stubs or LES, W-2s or 1099s for the past 2 years, and – if required – the last 2 years of federal tax returns
- Most recent 60 days of bank and/or asset statements
- Ratified purchase contract and property details (HUD tags / Data Plate, foundation documentation, and proof of title conversion to real property if applicable)
When a VA Manufactured Home Loan Is Not the Right Fit
Being straight with you matters more than a sale. A VA manufactured home loan is usually not the right path in these situations:
- The home is on leased land or in a park. VA requires real-property titling on land you own. For leased land, look at a chattel loan instead.
- The home was built before June 15, 1976. Pre-HUD-code “mobile homes” are generally not eligible for VA real-property financing.
- The home cannot be titled as real property or cannot be placed on a certified permanent foundation. If the titling or foundation path is blocked, the VA loan is blocked too.
- You do not have VA eligibility. If you have not earned a VA entitlement, an FHA manufactured home loan or, in rural areas, a USDA manufactured home loan may fit instead.
If you are building new on land you are buying rather than purchasing an existing manufactured home, ask me about the VA One-Time Close Construction Loan. And if you already own a VA-financed home, you may be able to lower your rate with a VA IRRRL streamline refinance or tap equity with a VA renovation loan.
FAQ: Delaware VA Manufactured Home Loans
Can I buy a single-wide manufactured home with a VA loan in Delaware?
Yes. The VA allows single-wide, double-wide, and multi-wide manufactured homes as long as they follow the program rules – classified as real property on land you own, built to HUD code (after June 15, 1976), set on a certified permanent foundation, and able to pass the VA appraisal and MPRs. A 30-year fixed term can apply when underwriting and property requirements are met, though individual lenders may add their own conditions.
Can I get a VA loan for a manufactured home on leased land in Delaware?
No. A VA loan must be secured by real property, which requires land ownership and real-property titling. If the home is on leased land or in a park, you would use a chattel loan instead. See Mobile Home Loans on Leased Land for the chattel path: https://delawaremortgageloans.net/mobile-home-loans-on-leased-land/
Can I really get a 30-year fixed VA loan on a single-wide?
Yes, when the home is titled as real property on owned land and meets VA and HUD standards. Articles that say VA caps manufactured homes at 20 years are describing the old manufactured-home-only (Title I) program, where the home is financed as personal property. A permanently affixed, real-property manufactured home is financed as a standard VA purchase loan with a 30-year fixed term available – single-wide included – subject to your file and the property meeting VA and lender requirements.
What documents do I need for my Certificate of Eligibility (COE)?
It depends on your status. Veterans typically provide a DD-214; active-duty members provide a Statement of Service; Guard and Reserve members provide an NGB-22, NGB-23, or a points statement. Surviving spouses follow VA guidelines. In most cases a lender can retrieve your COE electronically – I can help you get yours quickly.
Is there a minimum credit score for a VA manufactured home loan?
The VA does not set a universal minimum credit score; lenders apply their own standards, often around 620. Primary Residential Mortgage follows the VA’s own credit standards and does not impose a blanket minimum-score overlay on VA loans – approval depends on your full borrower profile, including credit history, income, residual income, and the property.
Can I buy the land and the manufactured home together with one VA loan?
Yes. Many buyers purchase the home and the lot together on a single VA loan, as long as the home will be permanently affixed and titled as real property. I can help coordinate the paperwork so the titling and foundation requirements are met before closing.
Are older mobile homes (built before June 1976) eligible?
Generally no. Homes must comply with the HUD Manufactured Home Construction and Safety Standards, which took effect June 15, 1976. Pre-HUD-code mobile homes are typically not eligible for VA real-property loans.
What if the HUD label or Data Plate is missing on a manufactured home?
A missing HUD certification label or Data Plate does not always end the loan, but it can delay the file. In many cases a Label Verification Letter from IBTS (HUD’s labeling contractor) can document the home, and most lenders accept it in place of a missing label. The lender still has to confirm the home meets VA, HUD, title, foundation, appraisal, and underwriting requirements.
Do I have to pay the VA funding fee on a manufactured home?
Most VA buyers pay a one-time VA funding fee, which you can roll into the loan. Veterans receiving VA compensation for a service-connected disability (and certain surviving spouses) are typically exempt. Because a real-property manufactured home is financed as a standard VA purchase loan, the funding fee follows the standard VA schedule based on your entitlement use and down payment – I will confirm your exact fee before you commit.
Can a manufactured home that was moved qualify for a VA loan?
It depends on the lender and the home’s history. Most lenders prefer manufactured homes that were moved only once, from the factory to the permanent site. A home relocated after its first installation is one of the most common disqualifiers and can be harder to finance, so it is worth reviewing the move history before you make an offer.
About John Thomas
NMLS #38783VA Loan SpecialistManufactured Home LendingAuthor
John Thomas is a mortgage loan officer with Primary Residential Mortgage in Newark, Delaware, with more than 20 years of experience helping veterans and active-duty service members finance manufactured homes – single-wide, double-wide, and multi-wide. Whether you are buying a single-wide on a lot you already own in Kent County, a double-wide in Sussex County, or coordinating a title conversion to real property, John has closed the scenario before and knows where VA manufactured-home files succeed and where they stall.
John guides veterans through COE requirements, HUD-code property standards, permanent foundation certification, and titling so they can confidently secure a 30-year fixed VA mortgage when eligible. He is the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826) and runs monthly first-time home buyer seminars. Licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA). NMLS #38783.
20+ Years | 3,000+ Buyers Helped | 1,000+ VA & Government Loans | DE & MD | PRMI
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | Schedule Appointment | YouTube | Full bio
Rated 4.8 stars across 285+ Google reviews. See the John Thomas Team on Google.
Ready to Use Your VA Benefit on a Delaware Manufactured Home?
If you are a veteran or service member considering a manufactured home in Delaware, I will walk you through every step – from your Certificate of Eligibility to the closing table – and help you find the home and program that fit. Let’s confirm your eligibility and map your path to closing.
Last Updated: June 2026 | Mortgage content reviewed by John R. Thomas, NMLS #38783.
John Thomas, NMLS #38783 | Primary Residential Mortgage, Inc. | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com | delawaremortgageloans.net
Copyright John R. Thomas, All Rights Reserved.
