Hockessin Delaware Mortgage Loans: Financing a Home in 19707 at Today’s Prices
Hockessin Delaware Mortgage Loans are mostly conventional, because the 19707 median sits above the FHA, DSHA and County DPS price caps. FHA, VA and DSHA fit many homes, and eligible first-time buyers can add New Castle County DPS, up to $15,000, on homes up to $594,550. USDA isn’t available (USDA map). Current as of October 2026.
In Hockessin the price of the house decides the loan more often than the buyer’s credit does. The ZIP’s median sale price recently passed the FHA limit, DSHA’s price limit and the County assistance cap, so the first thing we do is line your price range up against those numbers. I’m John Thomas, NMLS #38783, and I work from our office on East Chestnut Hill Road in Newark. This guide walks through Hockessin Delaware mortgage loans by price band, the County programs, cash to close and the property checks a Hockessin home can need. First purchase? Our Delaware first-time home buyer programs page is the place to start.
Looking at Homes in Hockessin?
Send us the price range or the listing. We’ll show which loans reach it, whether County DPS or DSHA can still help at that price, and what you’d bring to closing.
Table of Contents
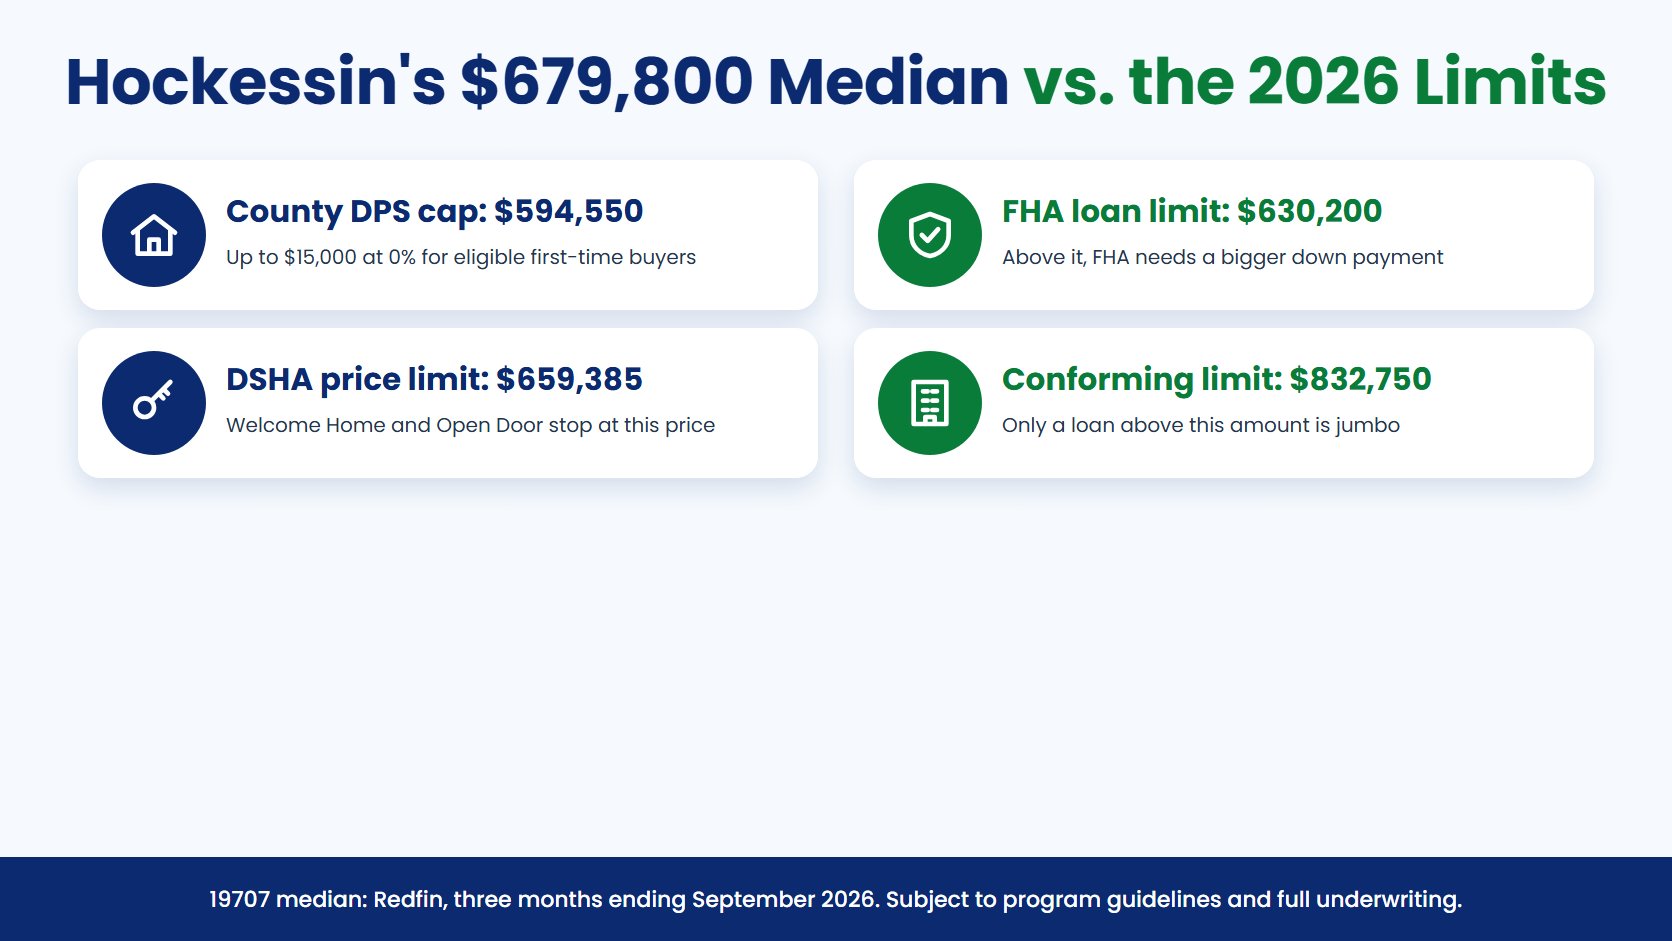
- 19707 median sale price: $679,800 (Redfin, three months ending September 2026).
- FHA loan limit, one unit, New Castle County: $630,200 (HUD).
- DSHA purchase price limit: $659,385 (DSHA Program Notice).
- New Castle County DPS price cap: $594,550; up to $15,000 at 0% for eligible first-time buyers (County DPS).
- Conforming loan limit: $832,750; larger loans are jumbo (2026 conforming limits).
- Transfer tax: 4% total, 2.5% to the State and 1.5% to New Castle County, with first-time buyer breaks on both shares (County transfer tax sheet).
- USDA: not available in Hockessin (USDA map).
Which Loans Reach Hockessin’s Price Range?
As of October 2026, the 19707 median of $679,800 sits above the FHA, DSHA and County DPS price caps, so conventional loans carry most Hockessin purchases. FHA, DSHA and New Castle County DPS still fit condos, townhomes and lower-priced houses, VA has no loan cap with full entitlement, and USDA doesn’t reach Hockessin.
Conventional financing does most of the work here. The 2026 conforming limit is $832,750 for one unit (Delaware conforming loan limits 2026), and it caps the loan amount, not the price: 10% down on a $900,000 house leaves an $810,000 loan that is still conforming. First-time buyers can put as little as 3% down through programs such as Freddie Mac Home Possible, and 20% down avoids private mortgage insurance. A loan above the limit becomes a Delaware jumbo mortgage. See conventional loans for Hockessin buyers.
FHA can lend up to $630,200 on a one-unit home in New Castle County in 2026 (HUD FHA limit lookup). At the $679,800 median, that cap means bringing about $49,600, roughly 7.3%, instead of the usual 3.5%, so FHA works best on Hockessin homes priced nearer the limit. HUD’s minimum score is 580 for 3.5% down, or 500 to 579 with 10% down (HUD FHA rules), and lenders may set a higher bar. Read FHA loans for Hockessin homebuyers and Delaware FHA loan limits 2026.
VA is the one zero-down loan that keeps pace with Hockessin prices: a veteran with full entitlement has no VA loan limit, and there’s no monthly mortgage insurance. Veterans who receive VA disability compensation are exempt from the funding fee (VA funding fee rules). Start with VA loans for Hockessin veterans and the VA eligibility requirements.
USDA doesn’t apply anywhere in Hockessin. In northern New Castle County, USDA-eligible land starts south and east of a line running along Porter Road and Route 72 to the canal bridge, and Hockessin lies well north of it. Buyers also shopping farther south can test each address on the USDA eligibility map and read about USDA loans in Delaware.
| Hockessin price or loan amount | Loans that can reach it | Watch for |
|---|---|---|
| Condo, townhome or house up to $594,550 | FHA, conventional or a DSHA first mortgage, plus County DPS for eligible first-time buyers | Association fee and condo project approval |
| $594,550 to $659,385 | FHA, conventional or DSHA; County DPS no longer applies | An FHA loan can’t pass $630,200, so the down payment grows |
| $659,385 to the low $800,000s | Conventional or VA; FHA only with extra cash down | DSHA’s price limit is passed |
| Loan amount over $832,750 | Jumbo, or VA with full entitlement | Jumbo reserve and credit standards |
What Does Unincorporated New Castle County Mean for a Hockessin Closing?
Hockessin is a Census-designated place rather than a town, so New Castle County fills the local role, as of October 2026. The County receives the 1.5% local share of the transfer tax and grants qualifying first-time buyers a partial exemption, its DPS Program covers Hockessin because it lies outside Wilmington, and no town tax is added.
Where the transfer tax goes. A New Castle County purchase carries 4% realty transfer tax, 2.5% for the State and 1.5% local. Inside Newark or Wilmington the local piece goes to the city; on a Hockessin parcel it goes to New Castle County on the County’s own return (County transfer tax information sheet).
The County’s first-time buyer break. On the New Castle County realty transfer tax return, a buyer who has never held an interest in residential property and will occupy the home within 90 days can claim a partial exemption of 0.75% on up to $400,000 of the price, a maximum of $3,000. That sits alongside the State’s own first-time buyer reduction, and your settlement attorney prepares the County affidavit and confirms the amount at closing.
County help applies. The New Castle County DPS Program serves every part of the county except the City of Wilmington, which runs its own programs, so a Hockessin buyer applies to the County.
No town tax, and a state line nearby. Property tax comes from New Castle County and the school district the parcel sits in, with no municipal bill, and we use the home’s real tax figures in your payment; any parcel can be looked up in the County’s online parcel records. Hockessin also sits just below the Pennsylvania line. Delaware and County programs and tax breaks stop at the border, so a house across the border in Chester County follows Pennsylvania’s rules.
Where Does the New Castle County DPS Program Fit in Hockessin?
It fits the lower-priced end of the market. As of October 2026, the County’s DPS Program offers eligible first-time buyers as much as $15,000 at 0% interest anywhere in New Castle County outside Wilmington, Hockessin included. Its price cap is $594,550, below the 19707 median, so DPS usually fits a Hockessin condo, townhome or smaller single-family house.
The program changed on October 1, 2026. DPS is now a 15-year second mortgage: nothing is due for three years, then a full $15,000 costs $104.17 a month for twelve years, and the balance is repaid if you sell or transfer the home. A housing counselor sets the amount, from $1,000 up to $15,000, based on what you need; you contribute at least $500 yourself, and each borrower completes homeownership education before closing, through a HUD-approved agency the County recognizes (County DPS program page).
The County measures income across the whole household, every member aged 18 or older, against 80% of the area median: $68,750 for one person up to $98,150 for four. That and the price cap matter more in Hockessin than anywhere else nearby. Redfin’s recent 19707 sales include condos that closed between $315,000 and $340,000 in October 2026, comfortably inside the cap, while most detached houses sell above it. Where both programs’ rules allow it, DPS can be stacked with DSHA assistance. Household-size income limits and the County’s property rules are explained on our New Castle County DPS Program page.
| For a Hockessin buyer | DSHA assistance | New Castle County DPS |
|---|---|---|
| Who can use it | Welcome Home: a buyer without a home in the past 3 years, or a qualified veteran. Open Door: first-time or repeat buyers | First-time buyers who haven’t owned property for 3 years |
| Whose income counts | Borrowers’ income (all income on the note for Welcome Home) | Everyone in the household aged 18 or older |
| Highest price | $659,385 | $594,550 |
| What you get | 3% to 5% of the loan, 0%, deferred until sale or refinance | $1,000 to $15,000 at 0%, 3 years deferred, then 12 years of payments |
| Homebuyer education | At a credit score of 659 or below | Every borrower, before closing |
Do DSHA’s Limits Work for Hockessin Delaware Mortgage Loans?
DSHA’s New Castle County standard limits cover Hockessin, as of October 2026. Welcome Home allows $122,700 of income for one or two people and $141,105 for three or more, Open Door allows $147,240 and $184,050, and both stop at a $659,385 purchase price, about $20,000 under the 19707 median.
| DSHA first mortgage | Buyer | Income limit, 1-2 / 3+ people (NCC standard) | Assistance options |
|---|---|---|---|
| Welcome Home | Hasn’t owned a home in the last 3 years, or a qualified veteran | $122,700 / $141,105, counting all income on the note | One of: First State 3%, Keys4You 4%, Take5 5%, Diamond in the Rough 5% |
| Open Door | First-time or repeat buyer | $147,240 / $184,050, qualifying income | First State 3% or Keys4You 4% |
DSHA’s Delaware Mortgage Program runs through those two first mortgages, and its down payment help is only available with one of them; the first mortgage underneath can be FHA, VA, USDA or conventional (DSHA Program Notice). Each assistance loan is a 0% deferred second mortgage repaid when you sell, refinance or move out: First State and Keys4You go with either first mortgage, while Take5 and Diamond in the Rough, which adds an FHA 203(k) Limited repair loan, pair only with Welcome Home.
None of DSHA’s New Castle County targeted tracts, which carry higher limits, is in Hockessin; they are all inside Wilmington. For Hockessin buyers the price limit, more than income, is what usually rules DSHA out, so we test the price first. Below $659,385, on a condo, a townhome or a smaller house, DSHA assistance can still cover a meaningful share of the down payment. Details: DSHA Open Door for Hockessin repeat buyers, DSHA Welcome Home for Hockessin buyers, and the full DSHA loan programs guide.
How Much Cash Does a Hockessin Purchase Take?
As of October 2026, a $680,000 Hockessin home bought with a conventional loan and 10% down needs $68,000 down plus closing costs, which often run 3% to 5% of the price and include $13,600 as the buyer’s half of the transfer tax. A $340,000 condo with FHA needs about $11,900 down, and assistance may help.
Check who pays the transfer tax. The standard Delaware Association of Realtors contract divides the 4% tax evenly between buyer and seller, but builder contracts and some resale contracts assign all of it to the buyer. On a $680,000 Hockessin home that is $27,200 rather than $13,600.
| Two hypothetical Hockessin purchases | $680,000 house, conventional, 10% down | $340,000 condo, FHA, 3.5% down |
|---|---|---|
| Down payment | $68,000 (loan $612,000) | About $11,900 |
| Buyer’s 2% transfer tax, standard contract | $13,600 | $6,800 |
| State first-time buyer reduction, if eligible | $2,000 (the cap) | About $1,700 |
| County first-time buyer exemption, if eligible | $3,000 (the cap) | About $2,550 |
| New Castle County DPS, if eligible | Not available above $594,550 | $1,000 to $15,000, set by your housing counselor |
| Lender, title, attorney, insurance and escrow | Depends on the loan and closing date | Depends on the loan and closing date |
To run your own numbers, enter a Hockessin price below. The estimator applies the same 4% split and the two first-time buyer breaks shown in the table.
For a home outside any city or town in New Castle County, where the 1.5% local share goes to the County. This is arithmetic on the 2026 tax rates, with no rates or payments involved. Your answers stay in your browser: nothing is sent to us or saved.
The remaining costs are the lender and title charges, appraisal, a year of homeowners insurance and prepaid taxes for the escrow account. An attorney handles every Delaware closing, so include the settlement fee, and read about owner’s title insurance. The State’s reduction, half a percent capped at $2,000 for buyers who have never owned a home, is explained on our Delaware first-time home buyer transfer tax exemption page, with the official rules at the Delaware Division of Revenue.
At Hockessin prices, family gifts and seller credits often matter as much as assistance programs. A negotiated seller credit (seller-paid closing costs) can reduce cash at closing, and FHA buyers whose income is too high for DPS or DSHA can ask about the Dream Maker down payment assistance program, which has no income limit and no first-time buyer rule. Not every combination is allowed, so we confirm yours on the file. For every statewide option, read the Delaware down payment assistance programs guide; understanding your mortgage payment breaks down the monthly figure.
What Are Hockessin Home Prices Doing in 2026?
Redfin put the 19707 median sale price at $679,800 for the three months ending September 2026, 18.2% above a year earlier, with homes taking about 38 days to sell compared with 22 the year before. A three-month median moves with the mix of homes that sold, so compare recent sales of your own home type.
Redfin’s 19707 housing market page counted 52 sales in September 2026, up from 39 a year earlier, at a median $216 per square foot. The 2020 Census counted 13,478 people and 5,113 homes in the Hockessin Census-designated place (Census TIGERweb place data). At the median, a Hockessin house is about $49,600 over the FHA limit, $20,400 over DSHA’s price limit and $85,250 over the County DPS cap, yet about $153,000 under the conforming limit, which is why conventional loans dominate here and why price bands matter so much.
Well and septic. If the house you choose uses a private well or a septic system rather than public water and sewer, ask early what the lender and appraiser will need, such as a water test or septic inspection, and build the time into your contract dates.
Flood risk. First Street’s data on the same Redfin page rates about 5% of 19707 properties at risk of severe flooding over the next 30 years. Look up the address on FEMA’s Flood Map Service Center; a home in a special flood hazard area needs flood insurance for the loan, and the premium counts in the payment you qualify for.
Condos, townhomes and older houses. An association fee is added to your housing payment when the lender figures debt-to-income, and a condo project must meet the rules for your loan type; FHA keeps a searchable list (HUD FHA condo search), and our Delaware condo loans page covers the paperwork. When an older house needs a roof, furnace or kitchen, the repairs can be financed with the purchase through a conventional HomeStyle renovation loan, an FHA 203(k) rehab loan or DSHA’s Diamond in the Rough. DPS requires a final appraisal that isn’t subject to repairs.
How Do You Buy a Home in Hockessin, Step by Step?
For a Hockessin purchase, the order runs: a pre-approval sized against the loan limits, a County DPS and DSHA check if your price allows, counseling when a program needs it, well, septic or association reviews, a contract whose transfer tax clause you’ve checked, and finally inspection, appraisal, underwriting and settlement, where first-time buyer forms are filed.
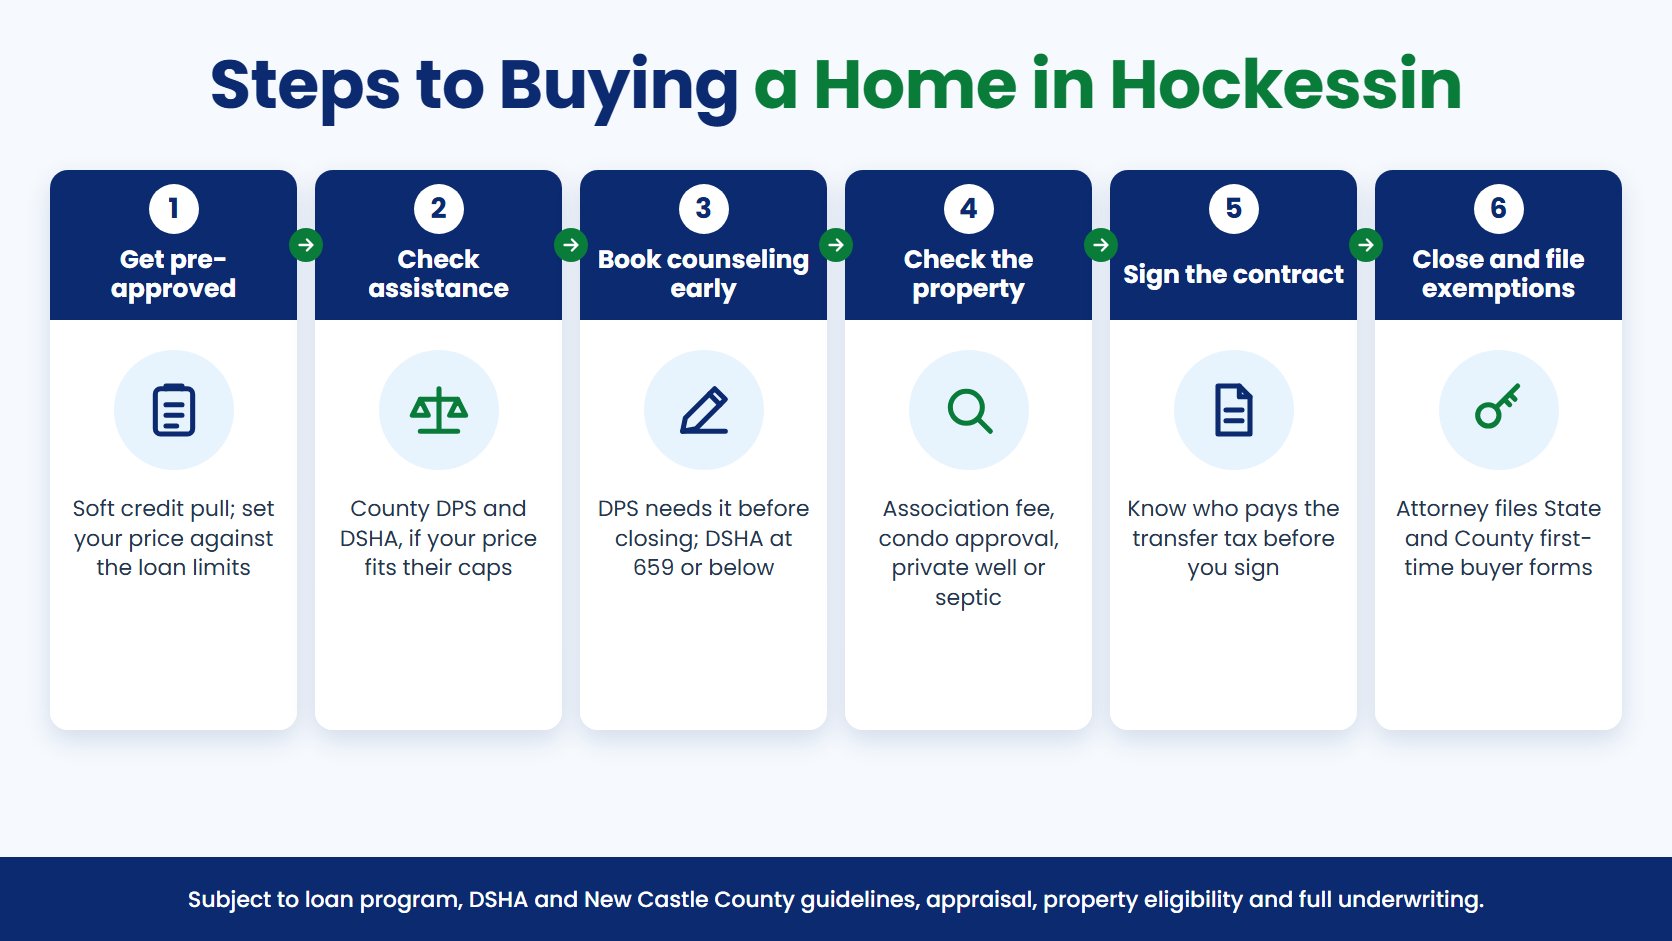
- Get pre-approved with a soft credit pull, and set your price range against the $630,200 FHA, $659,385 DSHA, $594,550 DPS and $832,750 conforming lines. A Platinum Pre-Approval has an underwriter review the file before you write an offer.
- If your price fits, check County DPS against your household income and DSHA against the income on the loan.
- Book homebuyer education early: every DPS borrower needs it before closing, and DSHA requires it at a 659 score or below.
- Before you offer, get the association fee on a condo or townhome, and ask whether the house has a private well or septic system.
- Choose the loan and any assistance, and sign the contract once you know who pays the transfer tax.
- Inspection, appraisal, underwriting and settlement. Underwriting a complete file usually takes 24 to 48 hours, and when the file is clean and the appraisal cooperates, closing in 21 days or less is common. At settlement the attorney files any first-time buyer transfer tax affidavits.
When a Hockessin Loan Option Is the Wrong Choice
- County DPS is out on a home priced above $594,550, when household income is over 80% of the area median, or when anyone buying has owned property in the past three years.
- DSHA is out above a $659,385 price, and standard Welcome Home is out once income on the note passes $122,700 for one or two people or $141,105 for three or more, though Open Door’s higher limits may still work.
- FHA loses its edge when the price forces a much larger down payment to stay at the $630,200 loan limit, or when strong credit makes a conventional loan’s removable mortgage insurance cheaper than FHA’s, which stays for the life of the loan with less than 10% down.
- USDA isn’t an option in Hockessin at all; VA, FHA or a 3% down conventional loan are the low-down routes.
- A jumbo loan isn’t needed just because the price is high: if your down payment keeps the loan at or under $832,750, the loan stays conforming.
Your own numbers decide each of these, and a 30-minute call with them in hand is usually the quickest way to an answer.
Serving Hockessin From Newark: Our Delaware and Maryland Service Area
The team works from 248 E Chestnut Hill Rd, Newark, DE 19713, and lends throughout Delaware and Maryland. Hockessin buyers can come into the office or do the whole loan by phone, video and online application.
Hockessin is marked; the team lends throughout Delaware and Maryland. Office: 248 E Chestnut Hill Rd, Newark, DE 19713.
Looking at neighboring areas too? See Pike Creek Delaware mortgage loans, Newark Delaware mortgage loans or Wilmington Delaware mortgage loans. Pike Creek shares Hockessin’s County rules at lower prices; Newark and Wilmington are cities with their own transfer tax share and local programs. To compare Hockessin with every other town we cover, including county loan limits and who collects the transfer tax, see Delaware mortgage service areas.
Why John Thomas Knows Hockessin
Every point here can be verified:
- John lives in Newark and is a Glasgow High School graduate; northern New Castle County has been home for most of his life.
- Our Newark office on East Chestnut Hill Road is where Hockessin buyers meet the team in person.
- The team teaches a free Newark Delaware first-time home buyer seminar, the nearest one to Hockessin, covering the buying steps before you shop.
- We’re a DSHA-approved lender and handle New Castle County DPS files, so Hockessin buyers can use the County program and the DSHA options with the same team.
Buying in Hockessin: Local Questions Answered
Questions buyers ask about Hockessin and the 19707 ZIP. Current as of October 2026.
Is Hockessin an incorporated town?
No. Hockessin is a Census-designated place in unincorporated New Castle County, counted at 13,478 residents and 5,113 homes in 2020. There’s no town government, so the County collects the local transfer tax share, County programs apply, and there’s no municipal tax bill.
Does New Castle County DPS work in Hockessin?
Yes, for eligible first-time buyers. Hockessin is in the county outside Wilmington, where the New Castle County DPS Program applies. It lends up to $15,000 at 0%, deferred for three years, to households at or below 80% of the area median, on homes priced up to $594,550, which in Hockessin usually means a condo, townhome or smaller house.
Can I use FHA on a Hockessin home above the FHA limit?
Sometimes. The limit caps the loan at $630,200, not the price, so you can buy above it if you bring the difference as a larger down payment. On a $679,800 home that’s about $49,600 down. Past that point, a conventional loan is usually the better fit.
How much transfer tax does a first-time buyer save in Hockessin?
Up to $5,000 combined if you qualify for both breaks. The State reduction is 0.5% of the price, capped at $2,000, and New Castle County’s exemption is 0.75% on up to $400,000, capped at $3,000. Both require that you’ve never owned residential property, and your settlement attorney confirms them.
Is any part of Hockessin eligible for a USDA loan?
No. Hockessin lies north and west of the Porter Road and Route 72 line, and nothing on that side of northern New Castle County is USDA-eligible. VA for eligible veterans, conventional with 3% down for first-time buyers, and FHA with 3.5% down are the low-down options.
Does a home with a well or septic system need anything extra?
Often, yes. Depending on the loan and the appraisal, the lender may ask for a water test on a private well or an inspection of the septic system, so find out whether the house has either before you set your contract dates.
What’s the typical home price in Hockessin right now?
Redfin’s 19707 median sale price was $679,800 for the three months ending September 2026, up 18.2% from a year earlier, and homes took about 38 days to sell. Condos and townhomes sell well below that figure and larger houses above it, so compare your own home type.
FAQ: Hockessin Delaware Mortgage Loans
What credit score do I need for a Hockessin home loan?
It depends on the loan. FHA’s HUD minimums are 580 with 3.5% down and 500 to 579 with 10% down. DSHA asks for 620 on both of its first mortgages and 640 for Diamond in the Rough, and borrowers at 659 or lower complete homebuyer education. County DPS follows your first mortgage. Conventional, VA and jumbo scores are set by the lender’s underwriting, and a lender may set its own higher floor. Rules as of October 2026.
Do I need a jumbo loan to buy in Hockessin?
Usually not. The 2026 conforming limit of $832,750 applies to the loan amount, so a $679,800 home stays conforming with any down payment, and even a $900,000 house does with 10% down. Only a loan above $832,750 is jumbo, with its own reserve and credit standards; see Delaware jumbo mortgages. Eligible veterans with full entitlement can use VA instead, as of October 2026.
Can I use New Castle County DPS and DSHA together on a Hockessin home?
Yes, if both programs’ rules allow it and the price fits both caps. DPS stops at $594,550 and DSHA at $659,385, so in Hockessin the pairing usually works on a condo, townhome or smaller house. DPS lends up to $15,000 at 0%, deferred for three years, and DSHA adds a 3% to 5% assistance loan, as of October 2026. County terms are on the New Castle County DPS Program page.
What is the least I can put down on a Hockessin home?
An eligible veteran can put nothing down with VA, a first-time buyer can start at 3% conventional, or 3.5% with FHA when the loan stays at or under $630,200. On a $679,800 home, 3% conventional is about $20,400, while FHA needs about $49,600 because of the loan limit. Eligible first-time buyers on lower-priced homes can add County DPS and DSHA assistance, as of October 2026.
Can I buy a Hockessin condo with FHA?
Only if the condo project meets FHA’s requirements, usually by being on FHA’s approved list or qualifying for a single-unit approval. Conventional lenders run a separate project review, so a building may pass for one loan and fail for another. Check before you write an offer; the lender will also look at the association’s budget and insurance.
Can I get a Hockessin mortgage after bankruptcy?
Usually, once a waiting period passes. After a Chapter 7 discharge, FHA and VA generally look for two years of rebuilt credit and conventional loans for four. County DPS and DSHA follow the first mortgage’s timing, and a lender may be stricter. Chapter 13 has different rules; see Delaware mortgage after bankruptcy, and a soft-pull review shows where you stand.
Can a family gift cover my Hockessin down payment?
Yes. Gifts from eligible donors are allowed on FHA, VA and conventional loans when documented with a signed gift letter and a record of the money moving to you. At Hockessin prices gifts are common. County DPS still needs at least $500 of your own money. Our gift funds and gift of equity page covers the paperwork.
I’m self-employed. Can I qualify for a Hockessin home?
Yes. Two years of tax returns usually support a conventional or FHA loan. If write-offs make your returns show less than you really earn, the 1099 mortgage loan program can qualify you on 1099 income, and a bank statement loan uses your deposits. Their terms differ, so we compare them for you.
Will a private well or septic system affect my Hockessin mortgage?
It can add steps. Depending on the loan and the appraisal, a lender may ask for a water test on a private well or an inspection of the septic system, and any repairs it turns up may need to be handled before closing. Ask the listing agent whether the house uses public water and sewer before you set your contract dates.
How quickly can I get pre-approved and close in Hockessin?
We begin with a soft credit pull and review your documents for pre-approval within a day of getting them. Underwriting a complete file usually takes 24 to 48 hours, and clean files with a cooperative appraisal regularly close in 21 days or less. County DPS and DSHA add counseling and their own approvals, so start those early.
About Your Hockessin Mortgage Lender, John Thomas
John R. Thomas is Branch Manager and Division Vice President with the John Thomas Team in Newark, Delaware, and has helped Delaware families buy homes for more than 20 years. He lives in Newark, graduated from Glasgow High School, and taught physics and physical science at Delcastle High School for more than ten years before mortgage lending became his full-time career. He also owned and ran a local SERVPRO franchise. With a Hockessin buyer, John starts by setting the price range against the FHA, DSHA, County DPS and conforming limits, because at Hockessin prices those lines choose the loan before rates do.
John holds a BS in Physics Education from the University of Delaware and an MS in Curriculum and Instruction from Delaware State University, and he earned the Certified Mortgage Planner designation in 2008. He is the author of Your Guide to Buying Your First Home in Delaware (see our Delaware first-time home buyer guide) and teaches the team’s first-time buyer seminars. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access. Read more on his loan officer bio page or meet the John Thomas Team.
Years 3,000+
Buyers Helped 1,000+
First-Time Buyers DE & MD
Service Area CMP
Certified Mortgage Planner
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com
Schedule Appointment (30 min)
See John Thomas Team on Google for reviews, directions, and local office information.
YouTube | Facebook | Instagram | TikTok | X / Twitter | LinkedIn
- Within 4 business hours you’ll hear from us by phone, text and email, and we keep following up for 14 days (the 4-14-24 standard).
- Once your documents arrive, a licensed loan officer reviews them for pre-approval within 24 hours.
- With a Platinum Pre-Approval, an underwriter reviews the full file before you make an offer; the appraisal and final approval remain.
- A single Loan Concierge handles your file from contract to closing and sends a Tuesday status email to everyone involved.
- New calls are answered Saturday and Sunday from 9 AM to 4 PM, for buyers writing offers on the weekend.
It starts with a soft credit pull, so your score isn’t affected. We set your price range against the loan limits, check New Castle County DPS and DSHA where the price allows, show the loans and assistance you may qualify for, depending on your credit, income and the property, and walk through your cash to close before you make an offer.
Last Updated: October 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
John R. Thomas, NMLS #38783 | John Thomas Team with AnnieMac Home Mortgage | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
AnnieMac Home Mortgage is an Equal Housing Lender. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access.
(c) Copyright John R. Thomas, All Rights Reserved.
