The benefit didn’t disappear — it shifted into lower interest rates and expanded down payment assistance through the current DSHA Delaware Mortgage Program. See what replaced it below or call 302-703-0727 for current options.
Delaware Mortgage Credit Certificate Program (MCC)
Quick Answer: The Delaware Mortgage Credit Certificate (MCC) program was a first-time home buyer tax credit issued by the Delaware State Housing Authority (DSHA) under Section 25 of the Internal Revenue Code that allowed eligible buyers to claim up to $2,000 per year in federal tax credits on mortgage interest paid. The program ended on August 15, 2025 and is no longer accepting applications. Today, those benefits have been replaced by the DSHA Welcome Home loan program — which provides reduced interest rates on first mortgages — and an expanded set of down payment assistance options including Keys4You (4% DPA), First State (3% DPA), Take5 (5% DPA), and Diamond in the Rough (5% DPA + 203k renovation). Call John Thomas, NMLS #38783, at 302-703-0727.
Quick Answer for Delaware Buyers
- The MCC program ended August 15, 2025 and is no longer accepting new applications
- The main rate-based replacement is the DSHA Welcome Home loan program
- Repeat buyers and higher-income buyers should review the DSHA Open Door program (formerly Home Again, renamed in the April 2026 DSHA rebrand)
- Down payment help is available through Keys4You (4%), First State (3%), Take5 (5%), and Diamond in the Rough (5% + 203k)
- Call 302-703-0727 to compare your current options in 15 minutes
Watch: What Happened to the Delaware Mortgage Credit Certificate in 2026?
The Delaware Mortgage Credit Certificate program — also called the Delaware First Time Home Buyer Tax Credit — was issued by DSHA under Section 25 of the Internal Revenue Code. It allowed qualifying borrowers to apply a percentage of their annual mortgage interest directly against their federal income tax liability — a more powerful benefit than a standard deduction. The program was available through approved lenders such as Primary Residential Mortgage in Newark, Delaware, where my team originated MCC loans throughout the program’s life from 2013 to 2025.
The MCC Program ended August 15, 2025. If you found this page while searching for the Delaware MCC, you’re in the right place — this page explains how the program worked, why it ended, and exactly what replaced it for Delaware home buyers today. The good news: the buyers who used to qualify for the MCC almost always qualify for one of the current DSHA programs, and for many buyers the new lineup actually delivers more value over the life of the loan than the old $2,000-per-year tax credit ever could.
Find Your Current Delaware First-Time Home Buyer Program
I’ll review your county, income, credit, and purchase goal — and tell you exactly which currently-funded DSHA program (or combination) is the best fit. No pressure, no obligation.
In This Guide
What You Will Learn on This Page
- What the Delaware MCC program was and how the $2,000-per-year tax credit worked
- Who qualified — and what the income, purchase price, and first-time buyer rules required
- Why the program ended on August 15, 2025 and what DSHA replaced it with
- How the current DSHA Welcome Home, Open Door, Keys4You, First State, Take5, and Diamond in the Rough programs work today
- Which current Delaware first-time home buyer program is the best fit for your situation
Watch: Delaware Mortgage Credit Certificate Program Explained by John Thomas
This video covers the MCC program as it operated prior to August 2025. It remains a valuable resource for understanding how the tax credit worked — and the comparison below shows why the new DSHA programs may serve you even better.
What Was the Delaware Mortgage Credit Certificate Program?
The Delaware Mortgage Credit Certificate was a first-time home buyer tax credit issued by DSHA under Section 25 of the Internal Revenue Code. It allowed eligible Delaware home buyers to claim up to 35% of their annual mortgage interest as a direct credit against their federal income taxes, capped at $2,000 per year. Unlike a tax deduction — which only reduces your taxable income — a tax credit reduces your actual tax bill dollar-for-dollar.
The credit could be claimed every year the borrower held the mortgage, making the total lifetime value significant. On a 30-year mortgage, the MCC had the potential to deliver up to $60,000 in cumulative federal tax savings for a qualifying borrower.
For Example: If you paid at least $5,715 each year in mortgage interest for the first 5 years you had the mortgage, you would get the full $2,000 federal tax credit each year — for a total of $10,000 in tax savings over those 5 years.
How Did the Delaware First Time Home Buyer Tax Credit Work?
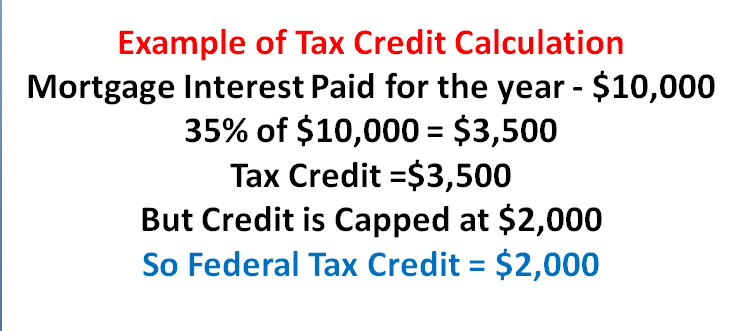
Each year, a borrower enrolled in the Delaware MCC Program multiplied their annual mortgage interest by 35% to calculate their credit. For example, a borrower paying $12,000 in mortgage interest in a year would calculate a credit of $4,200 — but the cap meant only $2,000 of that could be claimed. That $2,000 came directly off their federal tax bill at filing time. The remaining interest above the cap could still be claimed as a standard mortgage interest deduction.
Here’s what this means for you (today): If you were targeting the MCC’s $2,000 annual tax credit, the closest current equivalent is a DSHA Welcome Home first mortgage at the program’s reduced rate. On a $300,000 loan, even a 0.5% rate reduction saves roughly $90/month — about $1,080 per year — and that savings starts at closing rather than at tax time. Stack that with a Keys4You 4% DPA or First State 3% DPA and the buyer often comes out ahead of the old MCC math.
What Were the Eligibility Requirements for the Delaware MCC?
Principal Residence Requirement
Borrowers had to occupy the subject property as a primary residence within 60 days of closing. Investment properties, second homes, and rental properties did not qualify.
First-Time Home Buyer Requirement
Each borrower had to qualify as a Delaware first-time home buyer — defined as no principal residence ownership in the prior three years — unless the home was in a federally designated targeted area or the borrower was a qualified veteran. The targeted-area and veteran exceptions are still part of the current DSHA Welcome Home eligibility framework today.
Purchase Price and Income Limits
Purchase prices could not exceed 90% of the average area price for the county (110% in targeted areas). Household income could not exceed 115% of the applicable median gross income for the county (100% for households under three people). In targeted areas, the limit was 140% (120% for smaller households).
New Mortgage and Fixed Rate Requirement
The MCC applied only to new purchase transactions — not refinances. It was available only with fixed-rate mortgage loans through an approved DSHA lender. Certificates were issued on a first-come, first-served basis until the annual allocation was exhausted.
What Were the Income Limits for the Delaware MCC Program?
Income limits were based on the county where the property was located and the size of the household. The 2024 limits below are shown for historical reference only — the program ended August 15, 2025 and these figures are no longer in effect.
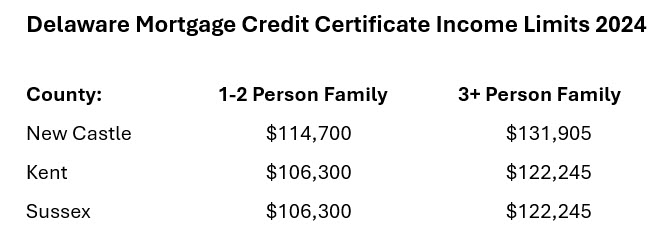
Current DSHA income limits (2026): The current Welcome Home program limits are $119,400 (1–2 person, NCC) up to $137,310 (3+ person, NCC); Kent & Sussex limits are slightly lower. The Open Door track allows higher incomes — up to $179,100 for 3+ person households in New Castle County. We’ll calculate your AMI percentage and tell you which programs you actually qualify for in about 15 minutes.
What Were the Maximum Purchase Price Limits?
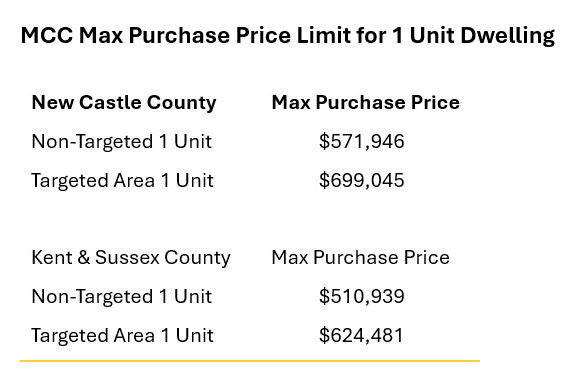
The current DSHA Open Door program raises the purchase price ceiling significantly above where the MCC operated — up to $617,241 in non-targeted areas and $544,232 in Kent and Sussex counties — which means today’s higher Delaware home prices fit comfortably under the cap. The Welcome Home program does not have a published purchase-price cap separate from the underlying loan-product limits.
What Replaced the Delaware MCC Program?
The Delaware Mortgage Credit Certificate program was effectively replaced by the DSHA Welcome Home loan program, which channels DSHA’s resources into reduced interest rates on first mortgages instead of a yearly tax credit. Rather than waiting for tax season, Delaware home buyers benefit from a lower interest rate starting from their very first payment. In addition, the April 16, 2026 DSHA rebrand expanded the down payment assistance lineup so today’s buyers also have access to Keys4You, First State, Take5, and Diamond in the Rough — none of which existed in the old MCC era.
The shift from a tax credit to a rate reduction is actually an improvement for many buyers. A lower interest rate reduces every monthly payment for the life of the loan — no paperwork, no tax filing, no annual cap. The savings begin immediately at closing rather than arriving as a refund the following spring. And because the new lineup includes multiple DPA programs that the MCC era did not have, buyers who used to get only the $2,000 tax credit can now get a reduced rate plus 3%, 4%, or 5% in down payment assistance — a much bigger combined benefit.
Delaware MCC Program vs. DSHA Welcome Home + Keys4You
| Feature | Delaware MCC Program | DSHA Welcome Home + Keys4You (2026) |
|---|---|---|
| Status | Ended August 15, 2025 | Currently funded |
| Type of benefit | Federal tax credit | Below-market rate + 4% DPA second mortgage |
| When you save | Once per year at tax filing | Every month starting at closing + at closing for DPA |
| Maximum benefit | $2,000/year tax credit | Lower payment for life of loan + 4% of loan amount as DPA |
| Buyer type | First-time buyers (with veteran/targeted-area exceptions) | First-time (Welcome Home) or repeat (Open Door) |
| Down payment help | None — tax credit only | Pairs with Keys4You (4%), First State (3%), Take5 (5%), or Diamond (5% + 203k) |
| Stacks with other programs | FHA, VA, USDA, Conventional | FHA, VA, USDA, Conventional + DSHA DPA second |
| Impact on affordability | Reduces tax bill once per year | Reduces monthly payment + reduces cash to close |
Why the Change May Actually Help Delaware Buyers More
For many buyers, a lower monthly payment combined with down payment assistance delivers more practical value than a yearly tax credit. Here’s why:
- Savings start immediately — no waiting until the following April to see the benefit
- A lower payment may help a buyer qualify for a higher purchase price
- No annual paperwork, IRS filings, or $2,000 caps to track
- The current programs pair with down payment assistance (3% to 5%) — something the MCC never offered
- Repeat buyers and higher-income buyers now have the Open Door program, which the old MCC era did not include
Before and After: How a Delaware Buyer Saves in 2026
2024 Buyer Using the MCC
Purchase price: $320,000
Annual mortgage interest: ~$14,000
MCC credit: 35% = $4,900 (capped at $2,000)
Federal tax savings: $2,000/year
Cash needed at closing: full down payment + closing costs
Benefit arrived once per year at tax time only
2026 Buyer Using Welcome Home + Keys4You
Purchase price: $320,000
Welcome Home reduced rate cuts monthly payment
Keys4You DPA: 4% = $12,800 toward down payment
Cash needed at closing: dramatically reduced
Monthly savings begin at closing — every month for the life of the loan
Benefit starts at payment one — every month, no tax-filing required
Current Delaware First-Time Home Buyer Programs Available in 2026
If you found this page looking for the Delaware MCC, these are the active DSHA programs to review now. All are currently funded and accepting applications through approved lenders including Primary Residential Mortgage. The April 16, 2026 DSHA rebrand consolidated the lineup under the new “Delaware Mortgage Program” umbrella, replacing the old Kiss Your Landlord Goodbye branding and updating product names — most notably renaming Home Again to Open Door and naming the 4% DPA “Keys4You” for the first time.
DSHA Welcome Home Mortgage Loan
The primary rate-based replacement for the MCC benefit. DSHA’s Welcome Home program provides below-market interest rates on first mortgages for qualifying Delaware first-time home buyers. Minimum credit score of 620 required. Pairs with the Keys4You (4%), First State (3%), Take5 (5%), or Diamond in the Rough (5% + 203k) DPA programs. Rates are published daily by DSHA at destatehousing.com.
DSHA Open Door Mortgage Loan
For buyers who exceed the Welcome Home income limits or who are not first-time buyers. The Open Door program (which renamed and replaced the old DSHA Home Again program in the April 16, 2026 rebrand) has higher income limits and is open to repeat buyers throughout Delaware. Pairs with Keys4You (4% DPA) or First State (3% DPA). Pairs with FHA, VA, USDA, and Conventional first mortgages. (See the legacy Home Again page for historical context.)
DSHA Keys4You Down Payment Assistance (4%)
Currently the largest DSHA DPA option available to repeat buyers. Provides 4% of the first mortgage amount as a zero-interest deferred second mortgage with no required monthly payments. Pairs with both Welcome Home (FTHB) and Open Door (repeat buyers) — that dual-pairing makes Keys4You the closest current equivalent of the old MCC’s broad accessibility. Named “Keys4You” in the April 16, 2026 DSHA rebrand; before that, the 4% DPA was an unnamed program tied only to Home Again.
DSHA First State Home Loan Down Payment Assistance (3%)
A 0% interest deferred second mortgage providing 3% of the first mortgage loan amount toward down payment and closing costs. No monthly payments required. Pairs with both DSHA Welcome Home and Open Door first mortgages. (This program was historically referred to as the “Preferred Plus DPA” before DSHA’s branding update.)
DSHA Take5 Down Payment Assistance (5%)
Launched April 16, 2026 as part of the DSHA Delaware Mortgage Program rebrand. Provides 5% of the first mortgage amount as DPA — currently the largest DSHA DPA available. Welcome Home (first-time buyer) only. For buyers who need maximum cash-to-close help.
DSHA Diamond in the Rough (5% DPA + FHA 203k)
For buyers purchasing a home that needs renovation work. Combines 5% DSHA down payment assistance with FHA 203(k) renovation financing of up to $75,000 — letting buyers roll purchase price and renovation costs into a single first mortgage. Welcome Home (FTHB) only.
For a full overview of all current Delaware home buyer options, visit the Delaware Down Payment Assistance Programs page or the Delaware First-Time Home Buyers pillar — or call 302-703-0727 to discuss which combination is right for your specific situation.
Which Program Is Right for You?
| Your Situation | Best Program to Review |
|---|---|
| First-time buyer, 620+ credit, moderate income | DSHA Welcome Home + Keys4You (4% DPA) |
| First-time buyer who needs maximum DPA | DSHA Welcome Home + Take5 (5% DPA) |
| Buyer over Welcome Home income limits | DSHA Open Door + Keys4You (4% DPA) |
| Repeat buyer (owned a home before) | DSHA Open Door + Keys4You or First State |
| Buying a home that needs repairs | Diamond in the Rough (5% DPA + 203k) |
| Veteran using VA loan | Delaware VA Loan — $0 down, no PMI |
| Buying in rural or suburban Delaware | USDA Loan — 100% financing |
| Not sure which program fits | Call 302-703-0727 — John Thomas reviews all options |
Common Myths About the Delaware MCC Program
Myth: The Delaware MCC Program Is Still Available
The program ended on August 15, 2025. DSHA stopped accepting applications on that date and the program has not been renewed. Any lender still advertising the MCC for new applications is providing outdated information.
Myth: The Benefit Disappeared When the MCC Ended
The benefit didn’t disappear — it shifted, and for many buyers it actually expanded. DSHA redirected MCC resources into the Welcome Home rate-reduction structure and added an entirely new layer of down payment assistance programs (Keys4You, Take5, Diamond in the Rough) that did not exist during the MCC era. For most buyers, the combined monthly payment savings plus DPA over the life of a loan exceed what the MCC’s $2,000 annual cap could have provided.
It’s also worth noting that Delaware has a separate First-Time Home Buyer Transfer Tax Exemption that is often confused with the MCC program. This is a different benefit — it reduces the state portion of the transfer tax paid at closing by 0.5% on purchase prices up to $400,000, saving buyers up to $2,000 at settlement. That program is still active and has nothing to do with the MCC ending. If you were searching for information on that benefit, see the Delaware First-Time Home Buyer State Transfer Tax Exemption and the New Castle County Transfer Tax Exemption for full details. Also worth knowing: Delaware’s standard DAR contract splits transfer tax 2% buyer / 2% seller, but home builders write their own contracts — some require the buyer to pay the entire 4%. Always read your sales contract carefully on new construction.
Myth: A Tax Credit Is Always Better Than a Rate Reduction
It depends entirely on the buyer’s situation. A $2,000 annual tax credit is fixed. A rate reduction compounds across every payment for the full loan term. A buyer who stays in the home long-term and finances a larger loan may come out significantly ahead with a rate reduction versus the $2,000 cap the MCC imposed. And once you stack down payment assistance on top — which the MCC never offered — the comparison gets even more lopsided in favor of the current programs.
Buying a Home in Delaware? Programs Are Available Statewide
DSHA programs are available throughout all three Delaware counties. Whether you’re buying in New Castle County — in cities like Newark, Wilmington, or Middletown — or in Kent County near Dover, or in Sussex County near Rehoboth Beach, Georgetown, or Lewes, the Welcome Home, Open Door, Keys4You, First State, Take5, and Diamond in the Rough programs apply statewide. Income limits and purchase price limits do vary by county, so working with a DSHA-approved lender who knows those specific thresholds is important.
John Thomas with Primary Residential Mortgage has helped buyers across all three Delaware counties for over 20 years. His team holds monthly home buyer seminars in Dover, Newark, and Wilmington — free to attend and covering all current DSHA programs in detail.
Delaware Mortgage Credit Certificate — Frequently Asked Questions
Is the Delaware Mortgage Credit Certificate program still available?
No. The Delaware MCC Program ended on August 15, 2025 and is no longer accepting new applications. Delaware home buyers should now review the DSHA Welcome Home and Open Door programs, which provide below-market interest rates and pair with current down payment assistance programs (Keys4You, First State, Take5, Diamond in the Rough). Call John Thomas at 302-703-0727 for current options.
What replaced the Delaware MCC program?
The DSHA Welcome Home loan program effectively replaced the MCC by providing reduced interest rates on first mortgages instead of a yearly tax credit. The April 16, 2026 DSHA rebrand also expanded the down payment assistance lineup with Keys4You (4%), Take5 (5%), and Diamond in the Rough (5% + 203k) — none of which existed in the MCC era. Rather than saving $2,000 per year on taxes, qualifying buyers save through lower monthly payments starting from day one of their loan plus thousands of dollars in down payment help at closing.
Is the DSHA Welcome Home program better than the MCC was?
For many buyers, yes. The Welcome Home rate reduction delivers savings every month from closing rather than once a year at tax time. It also has no annual cap and can be paired with down payment assistance — something the MCC did not provide. The right answer depends on your specific loan amount, tax situation, and how long you plan to stay in the home. John Thomas can run a side-by-side comparison for your scenario in about 15 minutes.
How much was the Delaware First Time Home Buyer Tax Credit worth?
Eligible home buyers could claim up to 35% of annual mortgage interest paid as a direct federal income tax credit, capped at $2,000 per tax year. The credit reduced actual taxes owed dollar-for-dollar and could be claimed every year the borrower held the mortgage — potentially up to $60,000 in cumulative federal tax savings over a 30-year loan for a qualifying borrower.
Who was eligible for the Delaware Mortgage Credit Certificate?
Borrowers had to be Delaware first-time home buyers (no homeownership in the prior 3 years), purchasing a primary residence in Delaware, using a fixed-rate mortgage through a DSHA-approved lender, and meeting household income and purchase price limits by county. Qualified veterans and buyers in federally designated targeted areas had relaxed eligibility requirements. The targeted-area and veteran exceptions are still part of the current DSHA Welcome Home eligibility framework today.
What mortgage programs can be used with the DSHA Welcome Home program?
The DSHA Welcome Home program supports FHA, VA, USDA, and Conventional loan types. It pairs with Keys4You (4% DPA), First State (3% DPA), Take5 (5% DPA — Welcome Home only), and Diamond in the Rough (5% DPA + FHA 203k renovation — Welcome Home only). Welcome Home cannot be combined with the MCC because the MCC has ended.
What is the DSHA Open Door loan program?
The DSHA Open Door program is for Delaware buyers who do not qualify for the Welcome Home program due to higher income or prior homeownership. It has higher income limits than Welcome Home, is open to repeat buyers statewide, and pairs with the Keys4You (4%) and First State (3%) DPA programs. Open Door replaced the previous DSHA Home Again program in the April 16, 2026 DSHA rebrand.
Does Delaware still have down payment assistance for first-time buyers?
Yes. Delaware has a stronger down payment assistance lineup in 2026 than at any point during the MCC era. The DSHA Keys4You program provides 4% of the loan amount as a deferred 0% interest second mortgage when paired with Welcome Home or Open Door. First State provides 3%, Take5 provides 5% (Welcome Home only), and Diamond in the Rough provides 5% plus FHA 203k renovation financing up to $75,000. Call 302-703-0727 or visit the Delaware Down Payment Assistance Programs page for full details.
Ready to Review Your Current Delaware Home Buyer Options?
If you were originally looking for the Delaware MCC tax credit, the next step is to find out which current programs you qualify for. I’ve helped 3,000+ Delaware families navigate DSHA programs and I’m a DSHA-approved lender for Welcome Home, Open Door, Keys4You, First State, Take5, and Diamond in the Rough.
Call 302-703-0727 Schedule Appointment Apply Online Now
Program availability, income limits, credit requirements, interest rates, and assistance amounts are subject to change by DSHA, investor guidelines, and market conditions. This page is for educational purposes and is not a commitment to lend or a guarantee of loan approval. All loans subject to credit and underwriting approval.
About the Author — John R. Thomas
Branch Manager & Mortgage Loan Officer — Primary Residential Mortgage, Inc.
John R. Thomas is a DSHA-approved mortgage loan officer and Branch Manager at Primary Residential Mortgage, Inc. in Newark, Delaware. With over 20 years of mortgage lending experience and 3,000+ Delaware buyers helped, John originated Delaware Mortgage Credit Certificate loans throughout the program’s life and now guides buyers through the full current DSHA Delaware Mortgage Program lineup — including Welcome Home, Open Door, Keys4You, First State, Take5, and Diamond in the Rough.
John holds a Bachelor of Science in Physics Education from the University of Delaware and a Master of Science in Curriculum and Instruction from Delaware State University — credentials that translate directly into the way he teaches Delaware home buyers about complex topics like the math behind tax credits versus rate reductions, DSHA program pairing strategy, and how to maximize cash-to-close when stacking DPA programs.
John is the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826) and teaches the monthly Delaware First Time Home Buyer Seminar in Newark, Wilmington, and Dover. His firsthand expertise on the Delaware MCC program — including how the Section 25 tax credit calculation actually worked in practice and how it compares to the current DSHA programs that replaced it — is the kind of lender knowledge national aggregator and bank sites simply cannot match.
248 E Chestnut Hill Rd, Newark, DE 19713
302-703-0727 | Schedule Appointment | See John Thomas Team on Google for reviews, directions, and local office information | YouTube Channel | NMLS #38783 Verified
Last Updated: April 28, 2026
John Thomas, NMLS #38783 | Primary Residential Mortgage, Inc. | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net | Licensed by the Delaware State Bank Commissioner | Equal Housing Lender
Copyright John R. Thomas, All Rights Reserved.
