
Newark Delaware First Time Home Buyer Seminar: FREE Virtual Class with John Thomas
AI OVERVIEW – NEWARK DELAWARE FIRST TIME HOME BUYER SEMINAR (Current as of June 2026)
The Newark Delaware first time home buyer seminar is a free two-hour virtual webinar taught by John Thomas, NMLS #38783, mortgage loan officer at Primary Residential Mortgage with a Newark office at 248 E Chestnut Hill Rd. Next sessions: Saturday July 18 and Saturday August 15, 2026 from 10 AM to Noon ET. The class covers DSHA Welcome Home, Open Door, Keys4You, Take5, First State, Diamond in the Rough, FHA, VA, USDA, and conventional financing as they apply to buyers in Newark ZIP codes 19711, 19713, and 19702 plus surrounding New Castle County. Every attendee receives a complimentary soft credit pull. No hard inquiry, no FICO impact. No sales pitch, no obligation.
If you are searching for a Newark Delaware first time home buyer seminar, you are in the right place. I am John Thomas, NMLS #38783, and I have been teaching free home buyer seminars from my office at 248 E Chestnut Hill Rd in Newark for more than 20 years. Through the Delaware Homebuyer Seminars program our team has run 586 seminars and helped educate 21,092 Delaware home buyers since 2005. Most of the buyers who attend live in or are looking to buy in Newark, Bear, Hockessin, Pike Creek, Glasgow, or surrounding New Castle County communities, though Maryland buyers and Wilmington area buyers are welcome too.
The class is virtual now, so you can attend from your kitchen table in 19713 or 19711 instead of driving anywhere. The seminar is taught live on Zoom, not a pre-recorded video. You can ask questions in real time. You will get a complimentary soft credit pull if you want one, with no hard inquiry and no FICO impact, so you walk out of the class with a real mortgage-grade credit score instead of the VantageScore your free credit-monitoring app shows. The seminar walks through the DSHA programs that were rebranded in April 2026, the FHA and VA loan basics, the Delaware transfer tax math that surprises a lot of Newark buyers at closing, and the buyer agency agreement rule change from the September 2024 NAR settlement that changes how you tour homes today. Below you can reserve your seat for the next Newark Delaware first time home buyer seminar.
Reserve Your Seat for the Next Newark Delaware Home Buyer Seminar
Free two-hour virtual class. Complimentary soft credit pull included. No sales pitch, no obligation.
NMLS #38783
Licensed Loan Officer
20+ Years
Delaware Lending
586 Seminars
Run Since 2005
21,092 Buyers
Educated
285 Google Reviews
Important note about DSHA homebuyer counseling: The Newark Delaware first time home buyer seminar is an educational lender seminar. It is not a HUD-approved housing counseling course. If your DSHA program loan requires a HUD-approved counseling certificate, you will need to complete that separately through a DSHA-approved housing counseling agency. The lender seminar gives you the mortgage program knowledge to choose the right loan; the HUD-approved counseling fulfills DSHA’s regulatory certificate requirement. Many Newark buyers do both, in either order. See the comparison further down the page.
Table of Contents
Quick Answer: What Is the Newark Delaware First Time Home Buyer Seminar?
QUICK ANSWER FOR DELAWARE BUYERS
Q: What is the Newark Delaware first time home buyer seminar?
A: A free two-hour virtual class taught live on Zoom by John Thomas, NMLS #38783, mortgage loan officer at Primary Residential Mortgage’s Newark DE office. The class covers Delaware-specific first time home buyer programs (DSHA Welcome Home, Open Door, Keys4You, Take5, First State, Diamond in the Rough), the four core mortgage loan types (FHA, VA, USDA, conventional), the Delaware 2% transfer tax math, and the September 2024 NAR settlement rules for buyer agency agreements. Every attendee gets a complimentary soft credit pull with no hard inquiry and no FICO impact. Next sessions: Saturday July 18 and Saturday August 15, 2026, both 10 AM to Noon ET. Register at delawarehomebuyerseminar.com or call 302-703-0727.
Q: Is this seminar local to Newark?
A: The presenter is local to Newark. The PRMI office at 248 E Chestnut Hill Rd is in Newark, John lives in Newark, and the seminar covers Newark-specific market context (19711, 19713, 19702 ZIP codes; University of Delaware, ChristianaCare, Christiana Hospital employer references; New Castle County housing data). The session itself is virtual on Zoom, so you can attend from anywhere with internet, but the content is tuned to Newark and surrounding NCC buyers.
Who Should Attend the Newark Delaware First Time Home Buyer Seminar?
The seminar is built for buyers who fit one or more of the following profiles. If you do not see yourself here, that does not mean the seminar is wrong for you. It usually means you should call 302-703-0727 first so we can route you to the right next step.

- First time home buyers in Newark or surrounding NCC. If you have not owned a primary residence in the last 3 years (DSHA’s first time buyer definition), most of the DSHA programs are available to you. Many Newark first time buyers do not realize they qualify until they take the class.
- Repeat buyers looking at DSHA Open Door. Open Door is the DSHA first mortgage track that opened to repeat buyers in April 2026. If you have owned before and want a competitive Delaware rate with optional down payment assistance, you should hear how Open Door works.
- Newark renters thinking about buying in the next 3 to 24 months. Most attendees attend 6 to 12 months before they actually purchase. The class is most useful when you have runway to fix credit issues, save additional reserves, or document income properly.
- UD faculty, ChristianaCare staff, and Christiana Hospital employees. These three employers cover a large share of Newark area buyers. The seminar covers the income documentation considerations that come up most often for these employer profiles, including W-2 plus 1099 mixed income, shift differentials, and per diem.
- Self-employed Newark buyers. If your tax returns understate your income because of write-offs, the seminar covers the Self Employed Bank Statement Loan and 1099 Mortgage program as alternatives to standard tax-return-based qualification.
- Veterans and active-duty military in Newark. Dover AFB is in Kent County, but plenty of Newark area veterans qualify for VA loans. The seminar covers the 0% down VA option and how it stacks against FHA + DSHA.
- Realtor partners and Realtor-side professionals. A handful of Newark area Realtors attend each session to stay current on DSHA program rebrands and FHA loan limit changes so they can advise their own buyers better.
What the Newark Delaware First Time Home Buyer Seminar Covers
The agenda is the same agenda used at the canonical Delaware First Time Home Buyer Seminars hub. The Newark seminar adds local context where relevant – Newark ZIP codes, University of Delaware and ChristianaCare employer scenarios, Newark housing price ranges – but the core program coverage is identical to what runs every month across the state. You will leave the class understanding the following in plain English:
- How pre-approval actually works and what makes it different from pre-qualification
- The three things mortgage lenders review when deciding whether to approve you: income, assets, and credit
- How to determine your maximum monthly mortgage payment based on your real budget, not just what a calculator says you can afford
- DSHA Welcome Home (first time buyers) vs DSHA Open Door (first time + repeat buyers) – which one fits your situation
- DSHA Keys4You (4% down payment assistance), Take5 (5% DPA, Welcome Home only), First State (3% DPA), and Diamond in the Rough (5% DPA + FHA 203k limited)
- FHA loan basics: 3.5% down at 580+ credit score, 10% down at 500 to 579 credit score, 2026 loan limits by Delaware county
- VA loan basics: 0% down for veterans and active duty military, no monthly mortgage insurance, what the VA funding fee covers
- USDA Rural Housing 100% financing – which Newark area communities are USDA-eligible (most of Newark itself is not, but parts of Glasgow and outlying areas are)
- Conventional 3% down and 5% down options for buyers with strong credit
- The Delaware 2% transfer tax math and why some new-construction builder contracts make you pay all 4% instead of splitting
- The September 16, 2024 NAR settlement and what it means for signing a buyer agency agreement before you tour homes
- How gift funds work for down payment and closing costs
- Credit score floors by program and what to do if your score is below floor
- Manufactured home eligibility rules (double-wide minimum, 660 minimum credit score, FHA only on DSHA)
- Bankruptcy seasoning rules and what a Chapter 7 discharge does and does not block
Lender Seminar vs DSHA Event vs HUD-Approved Counseling: What Is the Difference?
Buyers regularly confuse three different things that all use the word “class” or “seminar” or “counseling.” They have different purposes, are run by different organizations, and produce different outcomes. The Newark Delaware first time home buyer seminar is the first column. Most buyers eventually attend all three, in some order, but they are not interchangeable.
| What you are getting | This Lender Seminar (free) | DSHA Event (free) | HUD-Approved Counseling (fee may apply) |
|---|---|---|---|
| Who runs it | Lender (John Thomas Team, PRMI) | Delaware State Housing Authority | HUD-approved counseling agency |
| Primary purpose | Learn mortgage program options, get pre-approval-ready | DSHA program overview and DSHA-side process | One-on-one or group counseling for DSHA certificate requirement |
| Covers full loan-program landscape | Yes – DSHA + FHA + VA + USDA + Conventional + Non-QM alternatives | DSHA programs primarily; brief overview of other loan types | Varies by agency; primary focus on counseling certificate |
| Issues HUD-approved certificate | No | No | Yes – this is the only path to the certificate DSHA requires when applicable |
| Complimentary soft credit pull | Yes – mortgage-grade FICO from all 3 bureaus | No | No |
| Pre-approval letter available after | Yes – on request, after we run application | No | No |
| Newark-specific market context | Yes – 19711, 19713, 19702 ZIPs; UD, ChristianaCare, Christiana Hospital scenarios | Statewide | Varies by agency location |
| Format | Live Zoom, 2 hours | Varies | Varies (group or one-on-one) |
| Required for DSHA financing | No (educational only) | No (educational only) | Often yes – check program guidelines |
The short version: if you want to understand which loan program fits your situation and walk out with a credit score and a clear next step, attend the lender seminar. If you want DSHA’s side of the process, attend a DSHA event. If your loan program requires HUD-approved counseling certificate, complete that separately through an approved agency. Doing all three is common and there is no required order, though attending the lender seminar early is the most useful sequencing because it tells you which loan program (and therefore whether the HUD counseling is required at all) fits your situation.
What Is a Soft Credit Pull and Why Does the Newark Seminar Include One?
A soft credit pull is a credit inquiry that does not appear on your credit report as a hard inquiry and does not lower your FICO score. Every Newark Delaware first time home buyer seminar attendee can request a complimentary soft credit pull, and most do. The reason this matters is that the score you see on Credit Karma, Experian’s app, or your bank’s free credit-monitoring tool is almost always a VantageScore. VantageScore is a real credit scoring model, but it is not the model mortgage lenders use. Mortgage lenders pull all three bureaus (Equifax, Experian, TransUnion) and use the mortgage-grade FICO models (FICO 2, 4, and 5). Those numbers often differ from VantageScore by 20 to 50 points in either direction. Sometimes more.
What this means for you: if you walked into the Newark seminar thinking your credit score was 680 because that is what Credit Karma showed, and the soft pull comes back at 645 mortgage-grade, you now know the score that DSHA, FHA, and conventional underwriting will actually see. That matters because DSHA’s 620 floor, FHA’s 580 floor, and conventional’s 620 floor all reference the mortgage-grade score, not VantageScore. The reverse can happen too: a buyer who thinks they have a 600 might get a soft pull back at 645 and discover they now qualify for programs they had ruled out. Either way, you walk out of the seminar with the same number your real lender application will produce, and there is no hard inquiry on your file. Many buyers attend the seminar months before they are actually ready to buy, specifically so they can get this number without committing to anything.
Newark Housing Market Context for First Time Buyers
The Newark market sits in a particular spot in 2026. The median home price in ZIP 19713 is around $335,372, the New Castle County median household income is around $95,739, and homes typically spend around 14 days on market with roughly 21 active listings at any given time per MBS Highway Real Estate Report Card data (current as of May 2026). What that means for first time buyers: most Newark-area homes fall well under the 2026 FHA loan limit for New Castle County ($630,200 for a single-unit property), well under the DSHA Welcome Home purchase price limits, and well under the DSHA Open Door purchase price cap of $617,241. In practice, almost every entry-level Newark home is eligible for every DSHA program, every FHA loan, and every USDA-eligible-area loan in surrounding Glasgow.
The local price-to-program fit is one reason Newark generates so much DSHA volume. A buyer using DSHA Welcome Home plus the Take5 5% DPA option on a $335K Newark purchase covers most of the FHA 3.5% down payment with the DSHA assistance, then a seller credit handles closing costs. That math gets walked through with specific numbers in the seminar.
Delaware Transfer Tax and the Newark Builder-Contract Trap
The Delaware state transfer tax is 4% total on home purchases. The standard Delaware Association of Realtors contract splits that 4% as 2% buyer and 2% seller. Most Newark area resale transactions use the DAR contract, so most Newark buyers pay 2% transfer tax. On a $335,000 Newark home, that is $6,700 in transfer tax paid by the buyer at closing, on top of down payment and other closing costs.
The trap: Newark area new-construction builders write their own contracts. Many of those builder contracts require the buyer to pay the full 4% transfer tax, not the standard 2% split. On the same $335,000 purchase, that flips your transfer tax from $6,700 to $13,400 – a $6,700 swing that surprises a lot of first time buyers at the closing table. The seminar covers how to spot this clause in a builder contract before you sign, and what your options are if your builder will not negotiate it. This is one of the highest-dollar surprises in Delaware home buying and almost none of the national mortgage education resources mention it, because it is specific to how Delaware structures the transfer tax.
The Three Things Mortgage Lenders Review
Every mortgage approval comes down to three buckets. The seminar walks through each one in plain English, with the credit score floors and documentation rules that apply specifically in 2026.
- Income. Two years of documented income history is standard. W-2 employees provide pay stubs, W-2s, and recent tax returns. Self-employed buyers provide two years of business tax returns, or alternative documentation through the Self Employed Bank Statement Loan or 1099 Mortgage Loan programs. Shift differentials, overtime, bonuses, and per diem income require averaging rules; the seminar covers how those are calculated. New employer in the last 60 days may or may not be a problem depending on the situation.
- Assets. You need documented funds to cover down payment, closing costs, and reserves (post-closing cash on hand). DSHA Keys4You and Take5 can cover most of the down payment, but DSHA typically wants to see at least a small contribution from your own funds. Gift funds are allowed under specific rules. Crypto sales are allowed if you can document the source and transfer.
- Credit. Mortgage-grade FICO floor varies by program: DSHA 620 (housing counseling required if 620-659), FHA 580 (10% down at 500 to 579), VA no fixed minimum (lender overlays typically 580), USDA 640 typical, conventional 620. Manufactured homes have a separate 660 minimum credit score floor regardless of program.
Pre-Qualification vs Pre-Approval for Newark Buyers
These two terms get used interchangeably, but they are not the same thing and the difference matters. Pre-qualification is a verbal or written estimate based on stated information. You tell the loan officer what you make, what you have saved, and what you owe; the loan officer estimates what you might qualify for. Pre-qualification is fast and useful as a starting point, but no real underwriting has happened. Pre-approval is a written approval letter issued after the lender has pulled credit, collected income and asset documentation, and run the file through automated underwriting. A pre-approval letter carries weight with Newark area Realtors and sellers because it represents a real commitment subject to property approval. Sellers in competitive Newark price points often will not look at offers without pre-approval letters attached.
The seminar will not pre-approve you on the call – that requires a real application and documentation. But the soft credit pull plus the program walkthrough is enough to know whether pre-approval is realistic in your timeline. Most Newark buyers move from seminar to formal pre-approval application within 30 to 90 days when the timing is right.
The September 2024 Buyer Agency Agreement Rule Change
Effective September 16, 2024, the National Association of Realtors (NAR) settlement changed how buyer’s agent compensation works in Newark and across the country. This is one of the genuinely fresh topics in the seminar because the rule change is recent enough that many Newark buyers and many newer Realtors are still working through what it means. In plain English:
- Buyers must now sign a written buyer agency agreement with a Realtor before that Realtor can show them homes
- The buyer agency agreement spells out how the buyer’s agent will be compensated and whether the buyer is responsible for any of that compensation
- Seller-paid buyer agent commission is still allowed and still common, but it is now an offer in the buyer’s offer rather than an automatic feature of the MLS listing
- Buyers should read the buyer agency agreement carefully before signing – the agreement governs the buyer-Realtor relationship and the compensation expectation, both of which affect your closing cost math
The seminar covers this as homebuyer education, not legal advice. If you have specific questions about a buyer agency agreement you are being asked to sign, a Delaware real estate attorney is the right resource for those questions.
When the Newark Delaware First Time Home Buyer Seminar Is Not a Good Fit
WHEN THIS SEMINAR IS NOT A GOOD FIT
The Newark Delaware first time home buyer seminar is broadly useful, but there are specific scenarios where you should skip the seminar and take a different next step. Most of these are timing or process mismatches rather than disqualifications:
- You are already under contract on a Newark home and need pre-approval this week. The seminar is educational and timed for buyers 3 to 24 months out. If your closing is in 30 to 45 days, call 302-703-0727 directly and we will route you straight to application.
- You completed HUD-approved homebuyer counseling within the last 12 months. Your counseling certificate is still current for DSHA purposes. You may be ready for a one-on-one consultation instead of a 2-hour group webinar. Schedule directly at schedule.johnthomasteam.com/30min.
- You only need one specific program answer. If your question is “Can I use VA loan with DSHA Keys4You?” or “Does my Newark townhouse condo project qualify for FHA?”, a 10-minute phone call is more efficient than a 2-hour class. Call 302-703-0727 and we can answer narrow questions directly.
- You need the HUD-approved counseling certificate that DSHA requires. The lender seminar is educational and does NOT issue HUD-approved counseling certificates. If your DSHA program loan requires the certificate, register with a DSHA-approved housing counseling agency for that specific requirement. The lender seminar is still useful in parallel, but it does not substitute for the HUD-approved class.
Not Sure Which Step Is Right? Here Is the Decision Table
| Your situation | Best next step | How to start |
|---|---|---|
| 3 to 24 months out from buying in Newark or NCC | Newark Delaware first time home buyer seminar | Register for May 16 or June 13 below |
| 0 to 3 months out, ready to start application | One-on-one consultation | Schedule Appointment |
| Under contract, need pre-approval this week | Call directly | Call 302-703-0727 |
| Ready to apply now, just need the link | Apply online | Apply Online Now |
Watch the Newark Delaware First Time Home Buyer Seminar Video
The short video below covers what the seminar includes and how to register. The actual class itself is taught live on Zoom on July 18 and August 15, 2026.
Reserve Your Seat for the Next Newark Seminar
Both upcoming sessions are free, virtual on Zoom, and run from 10 AM to Noon ET. Pick whichever Saturday works for your schedule. Add to calendar links are below each session.
UPCOMING SESSION
Saturday, July 18, 2026
10:00 AM to 12:00 PM ET, Virtual on Zoom
Free 2-hour class. Complimentary soft credit pull included. No sales pitch, no obligation.
Add to calendar: Google Calendar
UPCOMING SESSION
Saturday, August 15, 2026
10:00 AM to 12:00 PM ET, Virtual on Zoom
Free 2-hour class. Complimentary soft credit pull included. No sales pitch, no obligation.
Add to calendar: Google Calendar
Glossary of Key Newark Home Buyer Terms
If you are early in the home buying process, some of the terms used in the seminar may be unfamiliar. Here are the most common ones, defined in plain English:
- Delaware first time home buyer seminar. A free educational class for people who have not owned a home in the last 3 years (DSHA’s definition) or who simply want to learn the Delaware-specific mortgage and home buying process.
- DSHA homebuyer education. Refers to homebuyer education classes related to the Delaware State Housing Authority’s loan programs. Different from HUD-approved counseling (see below).
- HUD-approved housing counseling. Counseling delivered by a HUD-approved counseling agency that issues a certificate. DSHA program loans often require this certificate; the lender seminar does NOT issue it.
- Soft credit pull. A credit inquiry that does not create a hard inquiry on your credit report and does not lower your FICO score. Mortgage-grade FICO from all three bureaus.
- Down payment assistance (DPA). A separate loan or grant that helps with your down payment. DSHA Keys4You provides 4% DPA, Take5 provides 5%, First State provides 3%, and Diamond in the Rough provides 5% paired with FHA 203k Limited.
- LTV (Loan to Value). The ratio of your loan amount to the home’s value. A 3.5% down payment on a $335,000 Newark home means a 96.5% LTV.
- DTI (Debt to Income). The ratio of your monthly debt payments (including the new mortgage payment) to your gross monthly income. Most loan programs cap DTI at 43% to 56% depending on the program and compensating factors.
- PITI. Principal, Interest, Taxes, and Insurance – the four components of your monthly mortgage payment.
- MI (Mortgage Insurance). Insurance that protects the lender if you stop paying. FHA loans carry MIP (mortgage insurance premium); conventional loans with less than 20% down carry PMI (private mortgage insurance); VA and USDA have their own structures.
About John Thomas: Your Newark Seminar Presenter
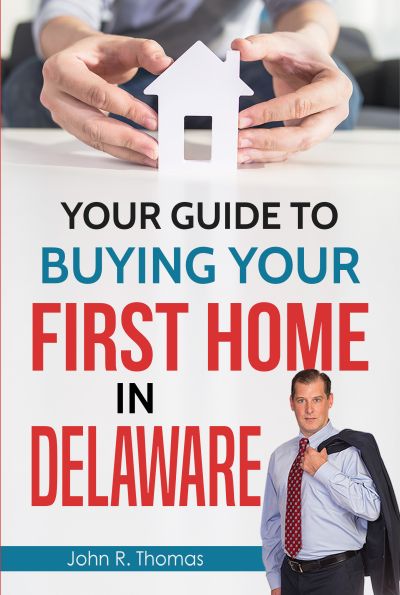
I am John Thomas, NMLS #38783, branch manager and mortgage loan officer at Primary Residential Mortgage’s Newark office at 248 E Chestnut Hill Rd. I have been licensed as a mortgage loan officer in Delaware for more than 20 years, and I have taught more than 586 Delaware home buyer seminars since 2005, educating 21,092 Delaware home buyers along the way. Before mortgage, I was a licensed physics and physical science teacher at Delcastle High School here in New Castle County, and I graduated from Glasgow High School in Newark. I hold a Bachelor of Science in Physics Education from the University of Delaware and a Master of Science in Curriculum and Instruction from Delaware State University. I am the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826), which is the textbook I use as the foundation of the seminar curriculum.
The reason I keep teaching free seminars after 20 years in the business is that Delaware mortgage rules change often enough that even people who bought a home 5 or 10 years ago need a refresher when they go to buy again. DSHA rebranded its entire program lineup in April 2026. The MCC tax credit program ended August 15, 2025. The NAR settlement changed buyer agency rules in September 2024. FHA loan limits changed in January 2026. The Delaware transfer tax math has its own quirks that national resources never cover. The seminar exists to put all of that current information in one place, in plain English, with no sales pressure, so Newark buyers can make informed decisions about how to finance their home purchase.
FAQ – Newark Delaware First Time Home Buyer Seminar
Where is the Newark Delaware first time home buyer seminar held now that it is virtual?
The Newark Delaware first time home buyer seminar is held on Zoom. You can attend from your home anywhere with internet access. Past seminars were sometimes held in person at the Hilton Wilmington/Christiana at 100 Continental Drive in Newark DE 19713, but the current monthly format is virtual. You will receive the Zoom link by email after you register at delawarehomebuyerseminar.com or by calling 302-703-0727. Many Newark buyers prefer the virtual format because there is no parking, no commute, and your spouse or partner can attend from the other end of the kitchen table without having to take time off work.
Does the Newark seminar count for the DSHA homebuyer counseling certificate?
No. The Newark Delaware first time home buyer seminar is an educational lender seminar, not a HUD-approved housing counseling course. If your DSHA loan program requires a HUD-approved counseling certificate (typically required when your credit score is between 620 and 659 for Welcome Home, and sometimes for other DSHA scenarios), you will need to complete that separately through a DSHA-approved housing counseling agency. The lender seminar covers the mortgage program landscape and helps you choose the right loan; the HUD-approved counseling fulfills the regulatory certificate requirement. Most Newark buyers who need both attend the lender seminar first because it tells them which DSHA program fits, then complete the HUD counseling for that specific program.
What is the difference between the soft credit pull at the Newark seminar and a hard credit pull when I apply for a mortgage?
A soft credit pull does not appear on your credit report as a hard inquiry and does not lower your FICO score. It returns the same mortgage-grade FICO scores from all three bureaus (Equifax, Experian, TransUnion) that your real mortgage lender will pull when you formally apply. A hard credit pull happens when you apply for credit and does appear on your credit report. Multiple hard pulls within a short window for the same purpose (rate-shopping for a mortgage within 14 to 45 days, depending on the FICO version) are typically treated as one inquiry for scoring purposes. The soft pull at the seminar gives you the mortgage-grade number months before you apply, so you can plan without committing to anything. Most Newark seminar attendees take advantage of this complimentary soft pull.
Can I attend the Newark seminar if I am buying in Bear, Middletown, Wilmington, or somewhere else in Delaware?
Yes. The seminar is taught from a Newark perspective with Newark-specific examples, but the core content (DSHA programs, FHA, VA, USDA, conventional, Delaware transfer tax, NAR buyer agency rules) applies statewide. Bear, Middletown, Hockessin, Pike Creek, Wilmington, Glasgow, New Castle, Dover, Smyrna, and Sussex County buyers regularly attend the Newark monthly virtual sessions. The session topics and program rules are identical across the Delaware Homebuyer Seminars series; the only thing that varies between sessions is which local market context the presenter weaves in for examples. Maryland buyers also attend and benefit since John Thomas is licensed in Maryland as well.
What if I have a Chapter 7 bankruptcy on my record – can I still attend the seminar and qualify for a Newark mortgage?
Yes on both counts. The seminar is open to all Delaware home buyers regardless of credit history. On qualification: a Chapter 7 bankruptcy does not block you from qualifying forever. FHA typically requires 2 years from discharge with re-established credit. Conventional typically requires 4 years from discharge. VA typically requires 2 years from discharge. USDA typically requires 3 years from discharge. DSHA follows the underlying loan-type rules. Foreclosure and short sale seasoning windows are typically longer than bankruptcy windows. The seminar covers the seasoning rules in detail, and the soft credit pull will tell you exactly where your current credit profile stands. Newark buyers in this situation often attend the seminar specifically to understand their timeline before they start house shopping.
Are Maryland buyers welcome at the Newark Delaware first time home buyer seminar?
Yes. John Thomas is licensed as a mortgage loan officer in Maryland as well as Delaware. Maryland buyers regularly attend the Newark virtual seminar because most of the core mortgage program content (FHA, VA, USDA, conventional) is federal and applies the same way in Maryland. The state-specific portions of the seminar (Delaware transfer tax, DSHA programs) are Delaware-specific, but Maryland buyers benefit from the federal program coverage and can ask Maryland-specific questions during the live Q and A portion of the class. If you are buying in Cecil County or Harford County Maryland, the Newark seminar is convenient because both counties border New Castle County.
I am self-employed or earn 1099 income – does the Newark seminar cover how to qualify with that kind of income?
Yes. Self-employment, 1099 income, and small business owner scenarios are covered in the seminar because they come up regularly in Newark area buyer profiles, especially among University of Delaware adjunct faculty, ChristianaCare contractors, and Newark area trades and service businesses. The seminar covers (a) standard two-year tax return qualification when your tax returns reflect your real income, (b) the Self Employed Bank Statement Loan when your tax returns understate income because of legitimate write-offs, and (c) the 1099 Mortgage Loan Program when you receive 1099 income with a documented two-year history. Each of these has different documentation requirements, different credit score floors, and different down payment minimums; the seminar walks through which scenario fits which profile.
How do I register for the next Newark Delaware first time home buyer seminar?
Three ways to register. (1) Online at https://delawarehomebuyerseminar.com – the registration form is at the top of the page and asks for your name, email, and which session date you want. (2) By phone at 302-703-0727. Mention the Newark seminar and the date you want when you call. (3) By scheduling a 30 minute one-on-one consultation first at https://schedule.johnthomasteam.com/30min if you would rather skip the group seminar and do everything in private. After you register, you will receive a confirmation email with the Zoom link for your session. The next two upcoming sessions are Saturday May 16, 2026 and Saturday June 13, 2026, both 10 AM to Noon ET.
Meet John Thomas: Your Newark Delaware Mortgage Loan Officer
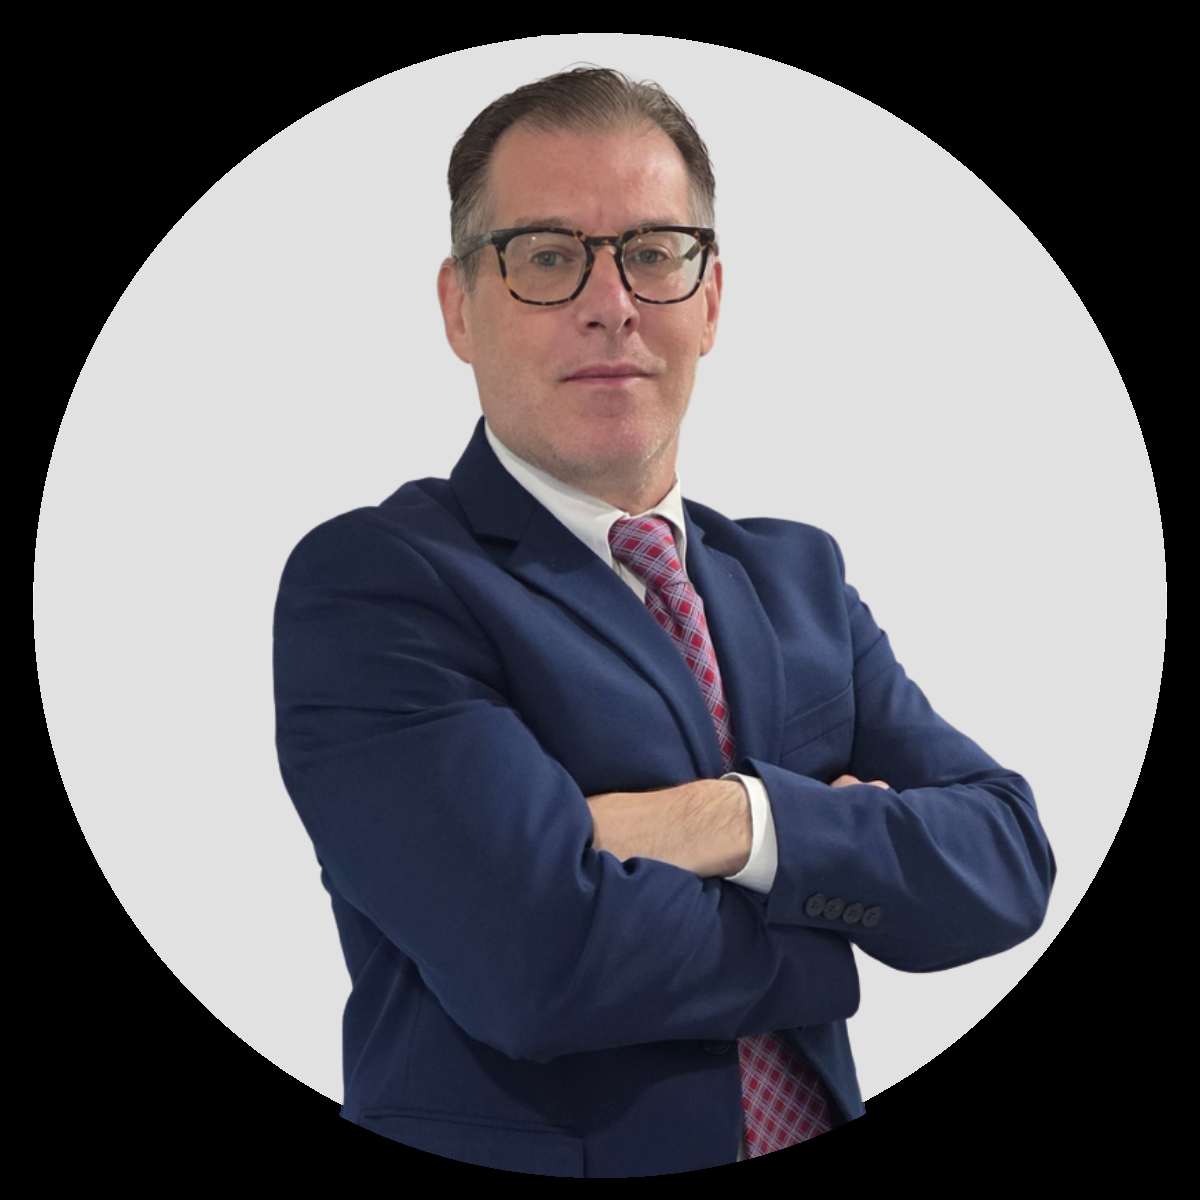
I am John R. Thomas, NMLS #38783, branch manager and mortgage loan officer at Primary Residential Mortgage’s Newark office at 248 E Chestnut Hill Rd. I have been licensed as a mortgage loan officer in Delaware for more than 20 years, and I am the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826), the textbook that anchors the Newark Delaware First Time Home Buyer Seminar curriculum.
Before mortgage, I was a licensed physics and physical science teacher at Delcastle High School in New Castle County, and I graduated from Glasgow High School here in Newark. I hold a Bachelor of Science in Physics Education from the University of Delaware and a Master of Science in Curriculum and Instruction from Delaware State University. Licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA), with active operational service in Delaware and Maryland.
20+ Years
Delaware Lending
586 Seminars
Run Since 2005
21,092 Buyers
Educated
Newark DE
Office Location
DSHA Approved
Lender
What Newark Buyers Are Saying on Google
★★★★★ Google Review
“John and his team were exceptional, responsive, and on point as it relates to funding information that was necessary. I would highly recommend him and his team. They’re very thorough and knowledgeable. Many times John slow walked information for me to understand. He’s very patient and cares about his business. I would recommend them and I would use them again.”
Patricia Canela · February 2026
★★★★★ Google Review
“I must praise the speed and patience shown by John, Sarah, Nicole, and Samantha when helping me buy my 1st (and hopefully ONLY) home. I asked a ton of questions, which they promptly responded to. Mine was an unusually complex situation, and was a race against the clock for many reasons as well, but we made it!”
Angela K Lacey · January 2026
Primary Residential Mortgage, Inc. – Newark Branch
248 E Chestnut Hill Rd, Newark, DE 19713
Phone: 302-703-0727 | Email: JohnThomasTeam@primeres.com
See John Thomas Team on Google (285 reviews, 4.8 of 5 stars) | Verify NMLS #38783 on NMLS Consumer Access
Ready to Take the Next Step on Your Newark Home Purchase?
Whether you are 18 months out and want to attend the seminar, ready for a private consultation, or already under contract and need pre-approval this week, John and the Newark team are ready to help. No sales pitch, no obligation. Pick the option that fits where you are right now.
Last Updated: May 2026. Mortgage content reviewed by John R. Thomas, NMLS #38783, DSHA-approved lender at Primary Residential Mortgage, Inc.
John Thomas, NMLS #38783 | Primary Residential Mortgage, Inc. | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
PRMI Corporate NMLS #3094 | Newark Branch NMLS #106170 | Licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA). Operational service area: Delaware and Maryland.
Copyright (c) 2026 John R. Thomas, All Rights Reserved.
