Wilmington Home Buyer Assistance Program (HAP): Closed Since 2012, and What Delaware Buyers Use Now
The City of Wilmington Home Buyer Assistance Program (HAP) is closed. In 2011 it offered up to $10,000 to income-eligible buyers of vacant homes in ZIP codes 19801, 19802 and 19805, and it stopped taking applications in January 2012 when its federal funds ran out. The City’s current homebuyer program is First Start. Current as of October 2026.
If you found the Wilmington Home Buyer Assistance Program in an old article or heard about a “$10,000 City grant” from a relative, you’re probably trying to figure out whether that money still exists. It doesn’t, but the help available to Wilmington buyers today is larger and easier to qualify for. I’m John Thomas, NMLS #38783. Below is what HAP was, when it ended, how it differs from the City’s current program, and which current options fit your purchase. If you’re buying inside the city, the Wilmington First Start program is the place to start.
Looking for the Wilmington Help That’s Open Today?
Tell us where you’re buying and roughly what you earn. We’ll check which current City, DSHA and lender programs you may qualify for and what your cash to close could look like.
Table of Contents
Is the Wilmington Home Buyer Assistance Program Still Available?
No. HAP stopped accepting applications in January 2012 after its Neighborhood Stabilization Program money was fully committed, and as of October 2026 the City of Wilmington’s Real Estate and Housing department lists First Start as its homebuyer program, with no HAP. Anyone offering you HAP funds today is working from outdated information.
When WHYY reported the suspension in January 2012, 33 buyers had qualified for a combined $277,000, with about nine more expected, and the City said it might reopen the program if it raised more money from rehabbing and selling City-owned homes (WHYY, January 11, 2012). It never came back under the HAP name. The City’s housing department today runs the First Start Homebuyer Program, which takes applications through lenders and housing counselors.
What Was the City of Wilmington HAP Program?
HAP was a City of Wilmington program, announced in May 2011, that gave income-eligible buyers up to $10,000 toward a vacant home in ZIP codes 19801, 19802 or 19805. The money started as a loan and became a grant after five years in the home, and buyers took an eight-hour counseling class.
The funding came from the federal Neighborhood Stabilization Program, which was created after the foreclosure crisis to put vacant and foreclosed homes back into use. That’s why HAP was tied to vacant property in three city ZIP codes rather than open to any Wilmington home. Applications in that first round were due June 30, 2011, with closings by August 31 (WHYY, May 20, 2011). For the right buyer it was real help, but the vacant-property rule and the short window meant most Wilmington buyers never used it.
How Is First Start Different From the Old HAP Program?
First Start offers more and covers more homes, as of October 2026: the lesser of $15,000 or 6% of the price for eligible first-time buyers anywhere inside city limits, on detached, semi-detached and row homes, forgiven after 10 years. HAP offered up to $10,000, only on vacant homes in three ZIP codes, forgiven after five years.

| HAP (2011, closed) | First Start (open) | |
|---|---|---|
| Amount | Up to $10,000 | Lesser of $15,000 or 6% of the price |
| Where | Vacant homes in 19801, 19802 and 19805 | Detached, semi-detached and row homes anywhere inside city limits |
| How it’s repaid | Loan that converted to a grant after 5 years in the home | Down payment part is a 0% conditional loan and the closing-cost part a grant; forgiven after 10 years as your primary residence, but due in full if you sell, move out or fall behind on the mortgage, City property tax or water and sewer bills before then |
| Buyer | Income limits applied | First-time buyer (no home in 3 years) within the City’s 80% or 100% of median income tiers, putting in at least $1,000 of their own money (gifts don’t count) |
| Counseling | 8-hour class | At least 8 hours with a HUD-certified agency (City list of counseling agencies), finished before you sign a sales contract |
| Funding | Federal Neighborhood Stabilization Program | Federal CDBG funds and City general funds, while funds last |
Two First Start rules catch people who remember HAP. The counseling has to be finished before you sign the sales contract, not afterward, and the City only funds the purchase after it approves your application, which your lender, agent or housing counselor submits through the City’s online portal. You don’t need a special lender; your lender only has to accept the City’s terms in writing, including a fixed-rate first mortgage of 30 years or less. Every rule and the current income limits are on our City of Wilmington First Start page.
What Can a Former HAP Buyer Use in Wilmington Today?
No single program replaced HAP. As of October 2026, buyers inside Wilmington can use City First Start, DSHA assistance of 3% to 5% of a DSHA first mortgage, and, with FHA, the NextKey program; City employees have their own up-to-$4,000 program. Buyers just outside the city use New Castle County’s DPS Program instead of First Start.
| Program | Who it’s for | Help available | Where to read the rules |
|---|---|---|---|
| City of Wilmington First Start | First-time buyers inside city limits within City income tiers | Lesser of $15,000 or 6% of the price | First Start |
| Wilmington Employee Homebuyer Assistance (Live Near Your Work) | City of Wilmington employees past probation, buying inside the city | Up to $4,000 | City employee program |
| DSHA Welcome Home or Open Door with assistance | Buyers statewide within DSHA income and price limits | First State 3%, Keys4You 4%, or Take5 5% (Welcome Home only) of the first mortgage as a 0% deferred second | DSHA loan programs |
| NextKey | FHA buyers, no income limit and no first-time rule, 600 minimum score | 3.5% or 5% of the price, forgivable or repayable | NextKey |
| New Castle County DPS | First-time buyers in the county outside the City of Wilmington, within 80% of median income | Up to $15,000 | County DPS |
DSHA in Wilmington. DSHA’s assistance comes only with a DSHA first mortgage. In New Castle County, Welcome Home’s standard income limits are $122,700 for 1-2 people and $141,105 for 3 or more, and Open Door’s are $147,240 and $184,050 (DSHA Program Notice, June 8, 2026). Wilmington has one advantage no other county town has: all six of DSHA’s New Castle County targeted census tracts are inside the city, where Welcome Home’s limits rise to $147,240 and $171,780 and the program opens to buyers who aren’t first-time buyers. To check an address, look up its census tract with the Census Geocoder and compare it with DSHA’s list, or send it to us and we’ll confirm. Our Wilmington Delaware mortgage loans page explains the tracts.
Combining programs. First Start may be combined with DSHA assistance when both programs’ rules allow it; the DSHA loan then records in second position and First Start in third. Which combination works, and whether NextKey or DSHA is the better fit beside First Start, depends on your income, the price and your first mortgage, so we check it before you write an offer.
Which Wilmington Option Fits Your Purchase?
Start with where the home is, then whether you’ve owned in the past three years, then your income. Inside the city with no recent ownership and income within the City’s tiers points to First Start; above those tiers or a repeat buyer points to DSHA Open Door or NextKey; outside the city points to the County’s DPS Program.
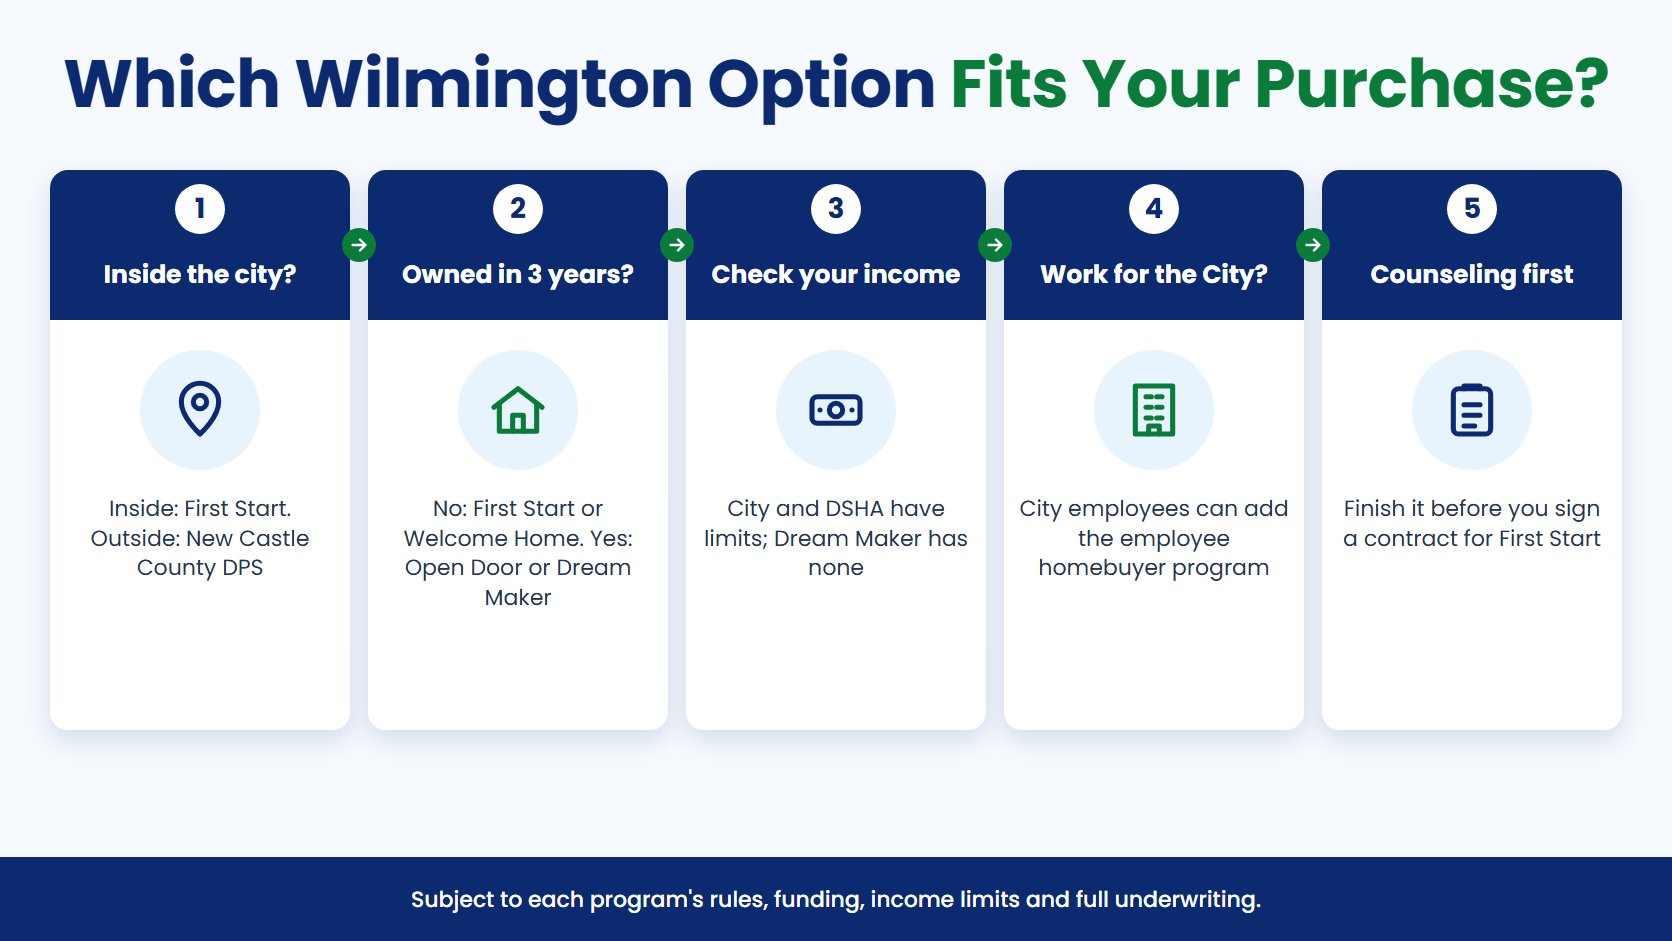
- Is the home inside the City of Wilmington? A Wilmington mailing address isn’t enough; many suburban addresses use it. Inside the city, First Start and the City’s programs apply; outside it, look at County DPS.
- Have you owned a home in the past three years? If not, First Start and DSHA Welcome Home are open to you. If you have, DSHA Open Door and NextKey don’t have a first-time rule.
- Where does your household income land? First Start counts every adult in the household against its 80% or 100% of median tiers; DSHA counts the borrowers; NextKey has no income limit.
- Do you work for the City? City employees past probation can also look at the Wilmington Employee Homebuyer Assistance Program.
- Is counseling done? For First Start, finish HUD-certified counseling before you sign a contract. Our free Wilmington first time home buyer seminar is a good first step.
In my experience, the buyers who end up disappointed are the ones who sign a contract first and ask about assistance afterward. First Start’s counseling-before-contract rule is the most common way a Wilmington buyer loses access to City money, so the order of these steps matters as much as the program you pick.
How Much Transfer Tax Does a Wilmington Buyer Pay?
The realty transfer tax on a Wilmington home is 4% of the price, as of October 2026: 2.5% to the State and 1.5% to the City of Wilmington, usually split 2% buyer and 2% seller. A qualifying first-time buyer can take up to $2,000 off the State share, and the City has its own first-time buyer exemption from its share.
Inside the city the 1.5% local share goes to the City instead of New Castle County, so the total isn’t higher than elsewhere in the county; it’s paid to a different place (County transfer tax information sheet). The State’s reduction is 0.5% of the price, up to $2,000, for buyers who have never owned a home (Delaware Division of Revenue; see our first-time buyer transfer tax exemption page). The City’s exemption is claimed on its exemption affidavit by a buyer with no interest in residential real estate inside the City for three years who moves in within 90 days; your settlement attorney confirms the amount. Builder contracts sometimes move the seller’s half to the buyer, so read that clause before you sign.
FAQ: Wilmington HAP and Today’s Alternatives
Can I still get $10,000 to buy a home in Wilmington?
Not from HAP, which closed in 2012, but often as much or more from current programs. As of October 2026, eligible first-time buyers inside the city can receive the lesser of $15,000 or 6% of the price through City of Wilmington First Start, up to $5,000 more than HAP’s cap, and DSHA assistance adds 3% to 5% of a DSHA first mortgage, with Take5 at 5% on Welcome Home. On a hypothetical $250,000 home, 5% is about $12,000 to $12,500 depending on the loan amount. Each program has income, price and funding limits, so the amount depends on your file.
Is the Wilmington HAP program the same as First Start?
No. HAP was a 2011 program funded by the federal Neighborhood Stabilization Program that paid up to $10,000 on vacant homes in 19801, 19802 and 19805 and closed in January 2012. First Start is the City’s current program: the lesser of $15,000 or 6% of the price for eligible first-time buyers anywhere inside city limits, forgiven after 10 years. An article from before 2012 that mentions City home buyer assistance is almost certainly describing HAP.
I’ve owned a home before. Is there anything like HAP for me?
Yes, though not from the City. First Start requires that you haven’t owned a home in the past three years. Repeat buyers can use DSHA Open Door with First State (3%) or Keys4You (4%) assistance, within Open Door’s New Castle County limits of $147,240 for 1-2 people and $184,050 for 3 or more as of October 2026, or the NextKey program on an FHA loan, which has no first-time buyer rule. A home in one of Wilmington’s DSHA targeted tracts can also use Welcome Home.
What if my income is too high for First Start or DSHA?
First Start has two income tiers, 80% and 100% of the area median, and counts every adult in the household. DSHA counts only the borrowers, and Open Door’s limits are higher than Welcome Home’s. If you’re above all of them, the NextKey program for FHA buyers has no income limit, and a seller credit can still cover part of your closing costs. We compare the options against your actual income before you choose.
Do I still need homebuyer counseling like HAP required?
For First Start, yes: at least 8 hours with a HUD-certified agency, finished before you sign a sales contract or apply for the mortgage, with a certificate good for one year. DSHA requires homebuyer education for borrowers with a 659 credit score or lower. The County’s DPS Program also requires counseling. Our free Wilmington first time home buyer seminar is a good place to start before you book the formal course.
Can I apply to the City of Wilmington directly for First Start?
No. Your lender, real estate agent or housing counselor submits the First Start application through the City’s online portal, and the City reviews it before it commits funds. Incomplete applications don’t hold money, and the City needs the funding request at least two weeks before closing. You can use any lender that accepts the City’s terms in writing, including a fixed-rate first mortgage of 30 years or less.
Can I combine First Start with DSHA down payment assistance?
Often, yes. First Start may be combined with DSHA assistance when both programs’ rules allow it. When they’re stacked, the DSHA loan records in second position and First Start moves to third, and First Start’s terms don’t change. How much you can combine depends on your income, the price and the first mortgage, so we confirm it before you sign a contract. Details are on the DSHA Welcome Home and First Start pages.
I work for the City of Wilmington. Is there extra help?
Yes. City of Wilmington employees who have finished probation and buy a home inside the city can apply for the City’s Employee Homebuyer Assistance Program, also called Live Near Your Work, which provides up to $4,000 toward down payment and closing costs. The City treats it as taxable income. See the Wilmington Employee Homebuyer Assistance Program page for the current limits.
Does any program help with the Wilmington transfer tax?
Partly. The tax is 4%, usually split 2% each between buyer and seller, with 1.5% going to the City of Wilmington. A first-time buyer who has never owned a home can take up to $2,000 off the State share, and the City has its own first-time buyer exemption from its share for buyers with no residential property in the City for three years. First Start and DSHA assistance can be applied to closing costs, which include your share of the tax.
Where can I see every Delaware down payment program, not just Wilmington’s?
Our Delaware down payment assistance programs guide lists every current statewide, county and city program side by side, with links to each program’s own page. Programs open and close with their funding, as HAP did, so check the date on any article you read and confirm a program is still funded before you plan around it.
About John Thomas, NMLS #38783
John R. Thomas is Branch Manager and Division Vice President with the John Thomas Team in Newark, Delaware, and has helped Delaware families buy homes for more than 20 years. Before lending full-time he taught physics and physical science at Delcastle High School in Wilmington for more than ten years. When a Wilmington buyer asks about an assistance program they read about, John’s first step is to confirm it’s still funded and that the home qualifies, before anyone plans a budget around it.
John holds a BS in Physics Education from the University of Delaware and an MS in Curriculum and Instruction from Delaware State University, and he earned the Certified Mortgage Planner designation in 2008. He is the author of Your Guide to Buying Your First Home in Delaware (see our Delaware first-time home buyer guide) and teaches the team’s free first-time buyer seminars. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access. Read more on his loan officer bio page.
Years 3,000+
Buyers Helped 1,000+
First-Time Buyers DE & MD
Service Area CMP
Certified Mortgage Planner
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com
Schedule Appointment (30 min)
See John Thomas Team on Google for reviews, directions, and local office information.
YouTube | Facebook | Instagram | TikTok | X / Twitter | LinkedIn
- You’ll hear from us within 4 business hours by phone, text and email, and we follow up for 14 days (our 4-14-24 standard).
- When your documents come in, a licensed loan officer reviews them for pre-approval within 24 hours.
- A Platinum Pre-Approval puts your full file in front of an underwriter before you make an offer; the appraisal and final approval remain.
- One Loan Concierge handles the file from contract to closing, with a Tuesday status email to everyone on the deal.
- New calls are answered Saturday and Sunday, 9 AM to 4 PM, for buyers writing weekend offers.
We start with a soft credit pull, so there’s no hit to your score. Then we check whether the home is inside the City of Wilmington, which current programs you may qualify for, depending on your credit, income and the property, and what your cash to close could be before you sign a contract.
Last Updated: October 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
John R. Thomas, NMLS #38783 | John Thomas Team with AnnieMac Home Mortgage | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
AnnieMac Home Mortgage is an Equal Housing Lender. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access.
(c) Copyright John R. Thomas, All Rights Reserved.
