DSHA Welcome Home Mortgage Loan Program in Delaware: The Complete 2026 Guide

Quick Answer for Delaware Buyers: The DSHA Welcome Home program is a 30-year fixed-rate first mortgage from the Delaware State Housing Authority for first-time homebuyers in Delaware. Eligible borrowers can pair Welcome Home with one of five down payment assistance options – Smart Start (no DPA), First State Home Loan (3%), Keys4You (4%), Take5 (5%), or Diamond in the Rough (5% with FHA 203k Limited renovation) – subject to income limits, purchase price limits, a 620 minimum credit score, and HUD-approved housing counseling for borrowers with scores between 620 and 659.
- Program: DSHA Welcome Home (under DSHA’s Delaware Mortgage Program, launched April 2026)
- Best for: First-time homebuyers in Delaware (no primary residence ownership in the past 3 years)
- 5 DPA options: Smart Start (none) / First State 3% / Keys4You 4% / Take5 5% / Diamond in the Rough 5% + FHA 203k Limited
- Maximum DPA: 5% of loan amount via Take5 or Diamond in the Rough
- 2026 income limits (New Castle County, 1-2 person household): $122,700 non-targeted / $147,240 targeted area
- 2026 income limits (Kent & Sussex, 1-2 person household): $111,400 non-targeted / $133,680 targeted area
- Minimum credit score: 620 (660 for manufactured homes); 620-659 requires HUD-approved housing counseling
- 2026 purchase price limits: $659,385 New Castle / $566,354 Kent & Sussex (higher in targeted areas)
- How to apply: Through a DSHA-approved lender. The John Thomas Team is a DSHA-approved lender in Newark – call 302-703-0727 or schedule a free 30-minute consultation
- Current as of June 2026. Income and sales price limits shown reflect the increases DSHA put in place for new reservations on or after June 8, 2026, verified against current 2026 lender bulletins and the April 2026 Delaware Mortgage Program rebrand.
Mortgage content reviewed by John R. Thomas, NMLS #38783, DSHA-approved lender with the John Thomas Team in Newark, Delaware. Last reviewed: September 2026.
Looking for DSHA Home Again? The Delaware State Housing Authority renamed the Home Again program to the DSHA Open Door loan program in DSHA’s April 2026 Delaware Mortgage Program rebrand. If you’re a repeat buyer or your qualifying income exceeds Welcome Home limits, Open Door is the program you want. If you’re a first-time buyer in Delaware, you’re in the right place – Welcome Home is the program built for you.
I’ve been originating DSHA Welcome Home loans in Delaware for over 20 years, and I’ll tell you upfront: this is the strongest first-time buyer program available in our state. If you qualify on income – and more buyers do than they realize – DSHA Welcome Home gives you a below-market 30-year fixed interest rate combined with down payment assistance of up to 5% of your loan amount. When DSHA launched the Delaware Mortgage Program in April 2026, Welcome Home didn’t just stay – it got stronger, with two new DPA products (Keys4You at 4% and Take5 at 5%) added on top of the existing options. This page walks through exactly how Welcome Home works in 2026: who qualifies as a first-time buyer, the income and purchase price limits in each Delaware county, all five DPA options compared side by side, the credit and counseling rules that trip people up, a real buyer example showing how the math works, and the steps to apply. If you’d rather just talk through your situation, my number is 302-703-0727.
See If You Qualify for DSHA Welcome Home
We’ll review your borrower income, credit, county, and purchase goal – then tell you whether Welcome Home fits, which of the five DPA options gives you the most assistance (up to 5% through Take5 or Diamond in the Rough), and exactly what you’ll need to bring to closing. No pressure, no obligation.
Table of Contents
| Feature | DSHA Welcome Home (2026) |
|---|---|
| Buyer type | First-time homebuyers only (no primary residence ownership in past 3 years) |
| Loan type | 30-year fixed-rate first mortgage (FHA, VA, USDA, or Freddie Mac Conventional) |
| Minimum credit score | 620 (660 for manufactured homes) |
| Housing counseling | Required if FICO 620-659 (8-hour HUD-approved course, ~$125) |
| DPA options | Smart Start (none) / First State 3% / Keys4You 4% / Take5 5% / Diamond in the Rough 5% |
| Maximum DPA | 5% of first mortgage loan amount |
| 2026 income limit (New Castle, 1-2 persons) | $122,700 non-targeted / $147,240 targeted |
| 2026 income limit (Kent & Sussex, 1-2 persons) | $111,400 non-targeted / $133,680 targeted |
| 2026 purchase price limit (New Castle) | $659,385 non-targeted (higher in targeted census tracts) |
| 2026 purchase price limit (Kent & Sussex) | $566,354 non-targeted (higher in targeted census tracts) |
| Income counted | Only income of borrowers on the Note and/or Mortgage (effective April 15, 2025) |
| Available statewide | Yes – all three Delaware counties |
What Is the DSHA Welcome Home Mortgage Loan Program?
DSHA Welcome Home is a 30-year fixed-rate first mortgage offered through the Delaware State Housing Authority’s Delaware Mortgage Program for first-time homebuyers in Delaware. Welcome Home isn’t itself an FHA, VA, USDA, or Conventional loan – it sits on top of one of those loan types. DSHA sets the interest rate (which is below market rate for most borrowers), then layers in optional down payment assistance through one of five DPA products.
Here’s the simplest way to understand the structure: your first mortgage is FHA, VA, USDA, or Freddie Mac Conventional – that part is the same loan structure any lender in Delaware can write. What DSHA adds is (1) a below-market interest rate set quarterly through DSHA’s bond program, and (2) the ability to combine that first mortgage with a zero-interest, no-monthly-payment second mortgage that covers your down payment and/or closing costs. The second mortgage – the DPA – only has to be repaid when you sell the home, refinance, or stop using it as your primary residence.
DSHA launched the Delaware Mortgage Program in April 2026 as a single rebrand event that retired the old “Kiss Your Landlord Goodbye” branding, renamed Home Again to Open Door, branded the previously unnamed 4% DPA as Keys4You and opened it to both Welcome Home and Open Door, and launched Take5 as a new 5% DPA exclusive to Welcome Home. None of the underlying first mortgage rules changed – Welcome Home is still for first-time buyers, Open Door is still for first-time and repeat buyers. The rebrand mostly cleaned up the DPA naming and added two new DPA products.
Who Qualifies as a First-Time Buyer Under DSHA Welcome Home?
The DSHA definition of “first-time homebuyer” is wider than most people assume. Under Welcome Home, you qualify as a first-time buyer if you have not owned a primary residence at any point in the past three years. That means owning a home four, five, or ten years ago does not disqualify you. Owning an investment property currently does not automatically disqualify you either – what matters is primary residence ownership in the three-year lookback.
Two exceptions allow buyers to use Welcome Home even if they have owned a primary residence in the past three years:
- Qualified veterans – active duty military, honorably discharged veterans, and certain eligible surviving spouses. The veteran exception waives the three-year first-time buyer rule entirely.
- Buyers purchasing in DSHA-designated targeted census tracts – Delaware has specific census tracts (concentrated in Wilmington, Dover, and parts of Sussex County) where DSHA waives the first-time buyer requirement and allows higher income and purchase price limits. If your target neighborhood happens to fall in a targeted tract, you may qualify even as a repeat buyer.
If you fall outside both exceptions and you have owned a primary residence in the past three years, Welcome Home isn’t the right program – but DSHA Open Door may be. Open Door covers both first-time and repeat buyers, has higher income limits, and pairs with three of the same DPA options (First State, Keys4You, and Smart Start). The trade-off is Welcome Home tends to have a slightly lower interest rate and exclusive access to Take5 and Diamond in the Rough.
What Are the DSHA Welcome Home Eligibility Requirements?
To use the DSHA Welcome Home loan program in Delaware, a borrower generally needs to meet all of the following:
- First-time homebuyer status – no primary residence ownership in past 3 years (or qualified veteran / targeted area exception)
- Minimum 620 credit score – 660 for manufactured homes
- Income at or below DSHA Welcome Home county limits – only income of borrowers on the Note and/or Mortgage counts (per the April 15, 2025 rule change)
- Purchase price at or below DSHA Welcome Home county limits – $659,385 in New Castle, $566,354 in Kent and Sussex (higher in targeted areas)
- Property must be in Delaware and used as the buyer’s primary residence
- HUD-approved housing counseling – required if FICO is between 620 and 659; not required if FICO is 660 or higher
- The buyer must work with a DSHA-approved lender – DSHA does not accept loan applications directly
The underlying first mortgage type (FHA, VA, USDA, or Freddie Mac Conventional) carries its own additional eligibility rules. For example, FHA requires the property meet HUD minimum property standards; VA requires a Certificate of Eligibility; USDA requires the property to be in a USDA-eligible rural area. Whoever you work with should walk through the layer-by-layer eligibility rather than just stating “you qualify for Welcome Home” – the underlying loan type matters as much as the DSHA layer.
What Are the DSHA Welcome Home Income Limits for 2026?
DSHA Welcome Home income limits for 2026 are tiered by county and household size, with higher limits available for properties in DSHA-designated targeted census tracts. The 2026 limits below reflect the increases DSHA put in place for new reservations on or after June 8, 2026 (current as of June 2026):
| County | Household size | Non-targeted limit | Targeted area limit |
|---|---|---|---|
| New Castle | 1-2 persons | $122,700 | $147,240 |
| New Castle | 3 or more persons | $141,105 | $171,780 |
| Kent & Sussex | 1-2 persons | $111,400 | $133,680 |
| Kent & Sussex | 3 or more persons | $128,110 | $155,960 |
The April 15, 2025 income calculation rule change matters here. Before April 15, 2025, DSHA counted income from all adult household members regardless of whether they were on the loan. As of April 15, 2025, DSHA Welcome Home counts only the income of borrowers on the Note and/or Mortgage. So if your spouse, parent, sibling, or roommate is not on the loan with you, their income does not count toward the DSHA limit. Household size still sets the tier (1-2 persons vs. 3 or more), but only borrower income tests against the limit. This is the single most common eligibility mistake I see – buyers assume they’re over the limit because they’re adding household income that doesn’t actually count.
What Are the Welcome Home Purchase Price Limits?
DSHA Welcome Home 2026 purchase price limits cap the home price you can buy under the program. Effective for new reservations on or after June 8, 2026, the non-targeted limits are $659,385 in New Castle County and $566,354 in Kent and Sussex Counties. Targeted area census tracts allow higher purchase price limits – $805,916 in New Castle County and $692,211 in Kent and Sussex Counties (roughly 22% above the non-targeted figures). If you’re shopping in a targeted area, your DSHA-approved lender can confirm whether a specific property falls inside a targeted tract before you write an offer.
For most New Castle County buyers, the $659,385 limit is more than enough headroom – Delaware median home price for a starter home in 2026 sits well below that ceiling. Where the purchase price limit becomes a real constraint is mainly Sussex County beach towns (Lewes, Rehoboth, Bethany), where coastal property prices can push past $566,354 even on modest properties. If you’re targeting a beach town and the purchase price limit is going to be tight, talk through it with your lender before you fall in love with a specific listing – switching from Welcome Home to a non-DSHA loan mid-contract is messy.
What Property Types Are Eligible for Welcome Home?
DSHA Welcome Home is flexible on property type as long as the buyer occupies the property as a primary residence. Eligible property types include:
- Single-family detached homes – the most common Welcome Home property
- Townhomes and rowhomes – both attached and end-unit townhomes
- 2-4 unit properties – allowed only with FHA, VA, or USDA underlying mortgage; buyer must occupy one of the units as primary residence
- Warrantable condominiums – condo project must be on the FHA, VA, or Freddie Mac approved list (or pass a project review)
- Manufactured homes – allowed under DSHA Welcome Home with three constraints: (1) minimum 660 credit score, (2) FHA underlying mortgage only, (3) double-wide or larger; manufactured homes are NOT eligible for Diamond in the Rough
Properties that are NOT eligible: investment properties, vacation homes, second homes, properties with more than four units, and any property the buyer does not intend to occupy as a primary residence. Mixed-use properties (commercial on the ground floor with residential above) are case-by-case – typically ineligible under standard DSHA programs.
What Down Payment Assistance Options Are Available with Welcome Home?
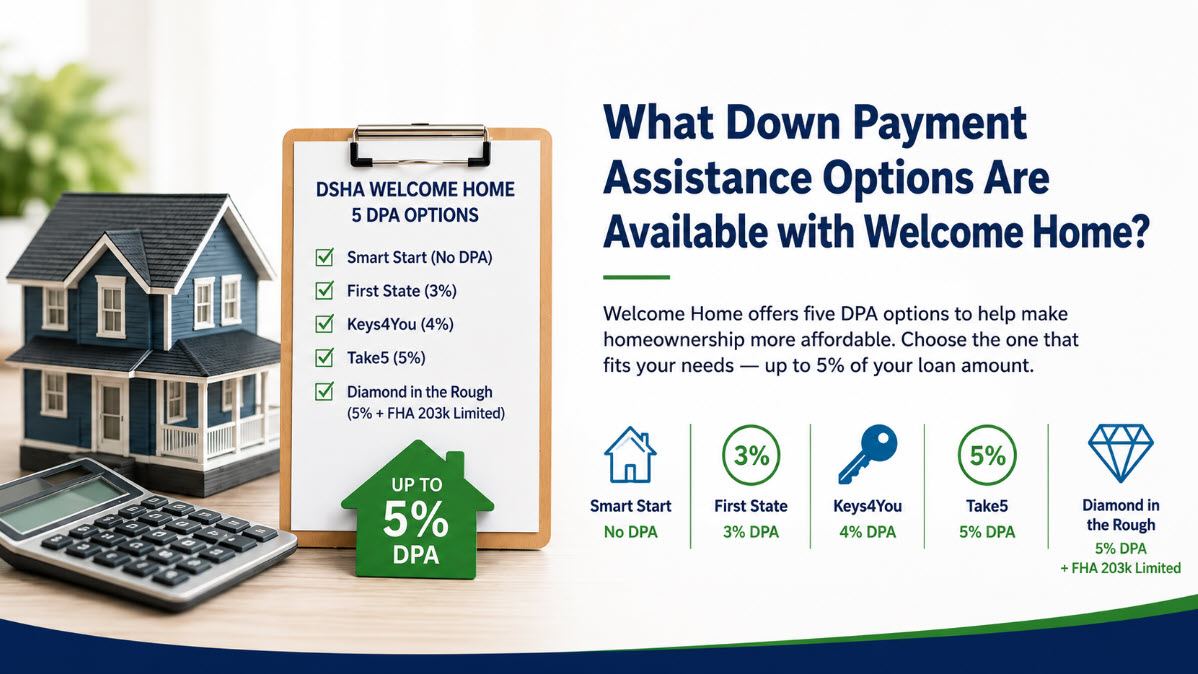
The biggest reason DSHA Welcome Home is the strongest first-time buyer program in Delaware is the DPA flexibility. Welcome Home pairs with five different down payment assistance options, and a buyer chooses the one that best fits their situation. Buyers may only use one DPA option per transaction – you can’t stack two DSHA DPAs on the same loan.
| DPA Option | Assistance amount | Available with | Best for |
|---|---|---|---|
| Smart Start | None (unassisted) | Welcome Home + Open Door | Buyers with their own savings who want the lowest possible interest rate |
| First State Home Loan | 3% of loan amount | Welcome Home + Open Door | Buyers who need moderate help and want the most common, well-understood DPA |
| Keys4You | 4% of loan amount | Welcome Home + Open Door | Buyers who need more help than 3% but don’t quite need the maximum |
| Take5 | 5% of loan amount | Welcome Home only | First-time buyers who want maximum DPA without renovation requirements |
| Diamond in the Rough | 5% of loan amount + FHA 203k Limited | Welcome Home only | First-time buyers purchasing a fixer-upper with minor repair needs |
Take5 and Diamond in the Rough are the two Welcome Home exclusives – Open Door buyers cannot use them. That’s part of why first-time buyers should usually default to Welcome Home if they qualify on income: even if you don’t think you need the maximum 5% assistance today, having Take5 and Diamond available expands your options if a particular property comes up that needs renovation work or stretches your closing-cost budget.
Real Buyer Example: Welcome Home with Take5 5% DPA
Numbers help. Here’s how the math works for a typical Welcome Home + Take5 first-time buyer in Delaware in 2026:
- Purchase price: $300,000 single-family home in New Castle County
- Underlying first mortgage: FHA, 3.5% minimum down ($10,500)
- First mortgage loan amount (after down payment): approximately $289,500
- Take5 DPA (5% of first mortgage): approximately $14,475 zero-interest deferred second mortgage
- How the $14,475 is applied: $10,500 covers the FHA down payment in full, leaving roughly $3,975 to apply toward closing costs and prepaids
- Buyer’s actual out-of-pocket at closing: closing costs minus the $3,975 leftover Take5 credit, minus any seller credit negotiated in the purchase contract – frequently $0 to a few thousand dollars depending on the deal
- Monthly payment on the Take5 second mortgage: $0 (deferred until sale, refinance, or end of primary residence use)
That’s the math that makes Welcome Home with Take5 such a strong combination for first-time buyers who qualify on income. The 5% assistance covers the entire FHA down payment AND a meaningful portion of closing costs, and you don’t owe anything monthly on the second mortgage. The Take5 only has to be repaid when you sell, refinance, or stop using the home as your primary residence – it sits silently in the background until then.
One important note on transfer tax: Delaware’s standard DAR contract splits the 4% state transfer tax 2% buyer / 2% seller, but builders often write their own contracts that require the buyer to pay the full 4%. If you’re buying new construction, ask up front who pays the transfer tax – it’s a $12,000 difference on a $300,000 home and it changes the math significantly. Welcome Home with Take5 helps cover transfer tax in the standard split scenario; in a builder-pays-nothing scenario, you may need additional seller credits or out-of-pocket cash.
What Are the Current DSHA Welcome Home Interest Rates?
DSHA Welcome Home interest rates are set by DSHA (not by individual lenders) and adjust periodically based on bond market conditions. Welcome Home rates are typically below standard FHA, VA, and Conventional market rates, and Smart Start (the unassisted Welcome Home option) carries the lowest rate within the Welcome Home tier. Adding DPA – First State, Keys4You, Take5, or Diamond – bumps the interest rate slightly, with the rate increasing by tier as the DPA percentage increases.
Welcome Home interest rates as of September 14, 2026. These are the rates on DSHA’s published rate sheet for that date, shown by DPA tier and by underlying loan type. They are not a quote, not an APR, and not a rate lock, and DSHA can change them on any business day. Call 302-703-0727 for today’s rate before you make a decision based on these figures.
| Welcome Home DPA tier | FHA / VA / RD | Conventional |
|---|---|---|
| Smart Start (no DPA) | 5.625% | 6.125% |
| First State Home Loan (3% DPA) | 5.875% | 6.375% |
| Keys4You Home Loan (4% DPA) | 6.125% | 6.500% |
| Take5 Home Loan (5% DPA) | 6.625% | 7.000% |
| Diamond in the Rough (5% DPA + FHA 203k) | 6.625% | Not available |
Source: Delaware State Housing Authority rate sheet dated September 14, 2026. Verify current rates at destatehousing.com/homeownership-loans. Diamond in the Rough is FHA 203k Limited only, which is why it has no conventional rate. APR will be higher than the interest rate shown and varies by loan amount, loan type, and fees – ask for your specific APR disclosure.
Read the table down a column and the structure of the program becomes obvious: every step up in down payment assistance costs you rate. On the FHA / VA / RD side that is a full point of spread from Smart Start at 5.625% to Take5 at 6.625%, and the same shape holds on the conventional side. That spread is the price of the assistance, financed over the life of the loan rather than paid at closing. Whether it is worth it depends entirely on whether you have the cash to close without it – which is the trade-off the next section walks through.
Here is how that trade-off plays out across the five DPA options. Smart Start has the lowest rate but no DPA. First State adds 3% DPA at a slightly higher rate. Keys4You and Take5 step up the DPA percentage with corresponding rate steps. Diamond in the Rough sits at the top of the DPA range and includes the FHA 203k Limited renovation overlay. The right choice for you depends on whether you’d rather have the lowest possible monthly payment (Smart Start) or maximize cash assistance at closing (Take5 / Diamond) – and that depends on whether you have your own savings.
DSHA Welcome Home vs. Open Door: Which Is Right for You?
The Welcome Home vs. Open Door choice is the single biggest decision DSHA borrowers face. Both are first mortgages under the Delaware Mortgage Program. Both pair with DPA. Both serve Delaware. The differences come down to four factors: who can use them, the income limits, the DPA options available, and the interest rate.
| Factor | Welcome Home | Open Door |
|---|---|---|
| Buyer eligibility | First-time buyers only (or veteran/targeted exception) | First-time AND repeat buyers – no first-time requirement |
| 2026 income limit (New Castle, 1-2 persons, non-targeted) | $122,700 | $147,240 |
| 2026 income limit (New Castle, 3+ persons, non-targeted) | $141,105 | $184,050 |
| 2026 income limit (Kent & Sussex, 1-2 persons, non-targeted) | $111,400 | $133,680 |
| 2026 income limit (Kent & Sussex, 3+ persons, non-targeted) | $128,110 | $167,100 |
| 2026 purchase price limit (New Castle, non-targeted) | $659,385 | $659,385 |
| DPA options | 5 (Smart Start, First State 3%, Keys4You 4%, Take5 5%, Diamond 5%) | 3 (Smart Start, First State 3%, Keys4You 4%) – no Take5 or Diamond |
| Maximum DPA | 5% | 4% |
| Interest rate | Typically slightly lower than Open Door at the same DPA tier | Typically slightly higher than Welcome Home at the same DPA tier |
The decision rule is straightforward. If you’re a first-time buyer and your income is at or below the Welcome Home limit, use Welcome Home. You get the lower rate, the wider DPA selection, and access to the two Welcome Home exclusives (Take5 and Diamond). If you’re a repeat buyer, OR your qualifying income exceeds the Welcome Home limit but stays under the Open Door limit, use Open Door. Open Door is built specifically to cover the buyers Welcome Home can’t.
The one wrinkle is veterans. A qualified veteran can use Welcome Home even as a repeat buyer (the veteran exception waives the first-time buyer rule), and the VA + Welcome Home combination is one of the strongest financing structures available in Delaware – VA covers the down payment, Welcome Home gives a below-market rate, and DSHA DPA can cover closing costs. If you’re a Delaware veteran, ask specifically about that combination.
Who Is DSHA Welcome Home Best For?
DSHA Welcome Home is the right program for first-time homebuyers in Delaware who fall into one of these scenarios:
- You don’t have 3.5% to 5% saved for the down payment. Welcome Home with First State, Keys4You, or Take5 covers the FHA down payment entirely and leaves additional cash for closing costs.
- You have some savings but want to keep cash in the bank. Welcome Home with Smart Start (no DPA) gets you the below-market interest rate without using your savings beyond what’s needed for the down payment.
- You’re a Delaware veteran buying your first primary residence. VA + Welcome Home is hard to beat – zero down through VA, below-market rate through DSHA, and DPA available for closing costs.
- You’re targeting a fixer-upper that needs minor repairs. Welcome Home with Diamond in the Rough pairs the program with FHA 203k Limited financing for the renovation work.
- Your household income is moderate. Welcome Home is built for buyers below DSHA’s county income limits. If your borrower income is above the limit, Open Door is the alternative.
When DSHA Welcome Home Is Not a Good Fit
I’d rather lose a Welcome Home loan to the right alternative program than push someone into the wrong loan. Here are the situations where Welcome Home is genuinely not the best choice:
- You’ve owned a primary residence within the past three years and you’re not a qualified veteran or buying in a targeted census tract. Welcome Home is closed to you in this scenario. Look at DSHA Open Door, which covers repeat buyers and pairs with three of the same DPA options (Smart Start, First State 3%, Keys4You 4%).
- Your qualifying borrower income exceeds the Welcome Home county limit. Welcome Home eligibility is hard-capped at the income limits – there’s no “we can stretch it” exception. Open Door has higher income limits – $147,240 vs. $122,700 in New Castle for 1-2 person households, and $184,050 vs. $141,105 for 3 or more – and may cover you.
- You’re targeting a beach property in Sussex County above $566,354. Welcome Home’s purchase price limit is binding. Conventional or jumbo financing through a non-DSHA lender will be the right path.
- You’re buying a manufactured home and want Diamond in the Rough. Manufactured homes are NOT eligible for Diamond – only single-wide-or-larger manufactured housing on FHA only with a 660 minimum FICO is eligible for Welcome Home at all. If you need 5% DPA on a manufactured home, look at Take5 instead (manufactured homes are eligible under Take5 with the same FHA + 660 FICO + double-wide-plus rules).
- You have 20% or more to put down on a Conventional loan and a credit score above 740. At that profile, a non-DSHA Conventional loan with no PMI may offer a better long-term cost structure than Welcome Home – DSHA’s value is concentrated on borrowers who need DPA or who benefit from the below-market bond rate. Get a side-by-side from a lender who can quote both before deciding.
- You don’t plan to live in the home as your primary residence. DSHA Welcome Home requires primary residence occupancy. Investment property buyers, vacation home buyers, and second-home buyers all need to look at conventional or DSCR financing instead.
If any of those situations describes you, call before assuming you’re stuck. The Delaware mortgage market has more programs than most buyers realize, and the right move is matching the program to the borrower – not forcing the borrower to fit one program.
Welcome Home: Pros and Cons
The honest pros and cons of DSHA Welcome Home, from someone who’s been originating these loans for two decades:
| Pros | Cons |
|---|---|
| Below-market 30-year fixed interest rate set by DSHA | Hard income limits – no flexibility above the cap |
| Five DPA options covering 0% to 5% assistance | Rates change with bond market conditions, not always predictable |
| Take5 and Diamond in the Rough exclusive to Welcome Home | Buyer must work with a DSHA-approved lender (limits choice) |
| DPA is a zero-interest deferred second – no monthly payment | HUD-approved housing counseling required if FICO 620-659 (~$125 fee + 8 hours) |
| Pairs with FHA, VA, USDA, or Freddie Mac Conventional | Manufactured homes require 660 FICO and FHA only |
| Targeted census tract option waives first-time requirement | Diamond in the Rough excludes manufactured homes |
| Veteran exception allows repeat-buyer veterans to qualify | Process slightly longer than non-DSHA loans (DSHA lender bulletin compliance) |
What Are the Closing Costs with Welcome Home?
Closing costs on a DSHA Welcome Home loan in Delaware run roughly the same as any other Delaware mortgage closing – typically 2% to 4% of the loan amount, depending on the underlying loan type, property location, and what’s negotiated in the purchase contract. The major closing cost categories on a typical Welcome Home transaction:
- Delaware state transfer tax – 4% of the purchase price total, split 2% buyer / 2% seller under the standard Delaware Association of Realtors contract. Builders sometimes write their own contracts that put the full 4% on the buyer; ask before signing on new construction.
- Lender fees – origination, underwriting, processing – typically a few hundred to about $1,500 depending on the lender
- Third-party fees – appraisal ($550-$700), credit report, flood certification, tax service
- Title and settlement – title insurance (typically required), settlement attorney or title company fee, notary, recording fees
- Prepaids – first-year homeowner’s insurance, prepaid property taxes (usually 2-3 months), prepaid mortgage interest from closing date to end of month, escrow deposit
- FHA upfront mortgage insurance premium (if FHA underlying) – 1.75% of the loan amount, typically financed into the loan rather than paid at closing
Welcome Home with First State (3%), Keys4You (4%), Take5 (5%), or Diamond (5%) can apply DPA dollars to closing costs after covering the down payment, which is why first-time buyers in Delaware so often end up at the closing table with very little out-of-pocket cash. Negotiating seller credits in the purchase contract can reduce out-of-pocket further. On well-structured Welcome Home + Take5 deals with seller credits, I’ve closed buyers with literally $0 to a few hundred dollars cash to close.
How Does the Housing Counseling Requirement Work?
DSHA requires HUD-approved housing counseling for any Welcome Home borrower with a credit score between 620 and 659. Borrowers with a 660 or higher credit score are exempt from the counseling requirement. The counseling is an 8-hour HUD-approved homebuyer education course, typically taken online, with a fee of approximately $125. The course covers budgeting, the mortgage process, homeowner responsibilities, and avoiding default – useful information regardless of whether DSHA requires it.
The counseling completion certificate is required at closing. Buyers should start the course early in the process – ideally as soon as they’re under contract, not the week before closing. The 8 hours are real hours; rushing through them at the last minute creates closing-day stress that’s easily avoided by starting early. DSHA maintains a list of approved counseling providers; ask your DSHA-approved lender for the current list when you start the loan application.
Common Mistakes First-Time Buyers Make with Welcome Home
The mistakes I see most often on DSHA Welcome Home applications, after 20+ years of originating these loans:
- Including non-borrower household income in the qualification calculation. Since April 15, 2025, only borrower income on the Note and/or Mortgage counts. Spouse-not-on-the-loan, parent, sibling, roommate income – none of it counts. Buyers regularly disqualify themselves before they even apply by adding household income that isn’t tested.
- Assuming Open Door is automatically better because it has higher income limits. Open Door is for buyers who can’t fit Welcome Home. If you fit both, Welcome Home almost always wins – lower rate, more DPA options, access to Take5 and Diamond.
- Looking up old “Kiss Your Landlord Goodbye” or pre-rebrand DSHA content. Anything published before April 2026 may reference outdated branding (Home Again as the active repeat-buyer program, no Keys4You name, no Take5). Use post-rebrand sources only when researching.
- Trying to combine DPA with the Mortgage Credit Certificate. The Delaware MCC ended August 15, 2025. Many national sites, blogs, and even accountants still reference it as active. The MCC tax credit is no longer available.
- Stacking DPA programs on the same loan. Buyers may only use one DSHA DPA option per transaction. You cannot combine First State 3% with Keys4You 4% to get 7%.
- Not factoring in the transfer tax split on builder contracts. The standard DAR contract is 2% buyer / 2% seller. New construction contracts written by builders sometimes require the full 4% from the buyer. On a $300,000 home, that’s a $6,000 swing – enough to consume your entire DPA benefit if you don’t catch it before signing.
- Starting the housing counseling course the week before closing. The course is 8 hours. Start it early.
- Falling in love with a Sussex County beach property over $566,354. The Welcome Home purchase price limit is binding. If you’re targeting beach towns, run the numbers on the price ceiling before viewings, not after.
Using Welcome Home Across Delaware’s Three Counties
Welcome Home works statewide, but the practical experience differs by county. New Castle County (Wilmington, Newark, Bear, Middletown, Hockessin, Pike Creek) has the highest income and purchase price limits, the most active inventory, and the most competition for Welcome Home-eligible properties. Kent County (Dover, Smyrna, Milford) and Sussex County (Lewes, Rehoboth, Seaford, Georgetown) share the lower limits, with Sussex beach towns specifically pressing against the $566,354 purchase price ceiling.
- New Castle County – most Welcome Home borrowers I work with are New Castle County buyers. The $659,385 purchase price limit comfortably covers most starter homes, and the $122,700 / $141,105 income limits accommodate the majority of first-time buyer income profiles in the county.
- Kent County – Welcome Home is highly competitive with conventional financing in Dover, Smyrna, and Milford. The $566,354 purchase price ceiling is rarely a constraint here. The $111,400 / $128,110 income limits cover most Kent County first-time buyer profiles.
- Sussex County – interior Sussex (Seaford, Georgetown, Bridgeville) works well within the $566,354 limit. Beach towns (Lewes, Rehoboth, Bethany, Fenwick) are where the purchase price ceiling becomes a real planning constraint. USDA loans pair particularly well with Welcome Home in rural Sussex – USDA covers the down payment, Welcome Home gives the below-market rate, and DPA can cover closing.
How Do I Apply for the DSHA Welcome Home Loan?
The DSHA Welcome Home application process runs through a DSHA-approved lender – DSHA does not accept loan applications directly. The John Thomas Team is a DSHA-approved lender in Newark, Delaware. The step-by-step process I walk first-time buyers through:
- Initial conversation (15-30 minutes). Call 302-703-0727 or schedule a free 30-minute consultation. We’ll discuss your borrower income, target county, credit score, savings situation, and whether you have a property in mind. By the end of that conversation, you’ll know whether Welcome Home fits and which DPA option to target.
- Loan application. Submit a full mortgage application either online at applywithjohnthomasteam.com or by phone with my team. We’ll collect tax returns, pay stubs, W-2s or 1099s, bank statements, and government-issued ID.
- Credit pull and pre-approval. Once we have a complete file, we run credit and underwrite to a Welcome Home pre-approval letter. This letter goes with your offers when you find a property.
- House shopping with a Realtor. Your Realtor needs to know you’re using DSHA Welcome Home so they write the offer correctly (DPA second mortgage line, transfer tax split language, DSHA-required addenda). If you don’t have a Realtor, ask for referrals to ones who routinely close DSHA loans.
- Property under contract. Once you have an accepted offer, the appraisal is ordered, the title work begins, and the loan moves into formal underwriting. If your FICO is 620-659, this is when you start the 8-hour HUD-approved housing counseling course.
- DSHA approval and clear-to-close. Underwriting issues conditions, we clear them, the file goes to DSHA for final program approval, and we move toward closing. DSHA program approval typically adds a few days to the timeline compared to a non-DSHA loan.
- Closing. Final walkthrough, signing at the title company, keys to the new home. The Welcome Home first mortgage and the DPA second mortgage close simultaneously – you sign for both at the same closing.
Total timeline from application to closing typically runs 30 to 45 days for a clean transaction. New construction can run longer because builders set the closing date based on construction progress.
The DSHA Welcome Home explainer video – John Thomas walks through the program structure, who qualifies, all five DPA options, and the application process. About 8 minutes.
The Complete Delaware First-Time Buyer Guide: John’s Book
I wrote Your Guide to Buying Your First Home in Delaware for first-time buyers who want a complete reference covering the full purchase process – not just DSHA programs, but credit, the pre-approval process, working with a Realtor, the offer and inspection process, the closing process, and what happens after you own the home. The book has been in print since 2010 and is updated periodically as Delaware programs change.
The book pairs well with this Welcome Home page – this page covers Welcome Home specifically; the book covers the broader first-time buyer process from start to finish. The two together are a complete reference for a Delaware first-time buyer.
Related Delaware Mortgage Guides
- DSHA Open Door Loan Delaware – the repeat-buyer / higher-income alternative to Welcome Home. Renamed from Home Again in DSHA’s April 2026 Delaware Mortgage Program rebrand.
- DSHA Keys4You Home Loan Delaware – the 4% DPA option, available with both Welcome Home and Open Door. Branded as Keys4You in the April 2026 rebrand.
- Take5 Home Loan Delaware – the 5% DPA option, exclusive to Welcome Home. Launched in April 2026 as part of the rebrand.
- DSHA First State Home Loan DPA Program – the 3% DPA option, available with both Welcome Home and Open Door.
- DSHA Diamond in the Rough Delaware – the 5% DPA + FHA 203k Limited renovation combination, exclusive to Welcome Home. For first-time buyers purchasing a fixer-upper.
- Delaware Down Payment Assistance Programs (DPA Hub) – the cluster’s central hub covering all Delaware DPA options, not just DSHA.
- Delaware First-Time Home Buyer Guide (Pillar) – the complete first-time buyer pillar page covering the full purchase process beyond just DSHA.
- Delaware FHA Loans – the most common underlying first mortgage type paired with Welcome Home. 3.5% minimum down, 580+ credit minimum (DSHA layers a higher 620 minimum on top).
- Delaware VA Loans – for Delaware veterans, the strongest underlying first mortgage to pair with Welcome Home (the veteran exception waives the first-time buyer requirement).
- DSHA Home Again Mortgage Loan (legacy) – the legacy page for buyers searching the old “Home Again” branding. Renamed to Open Door in DSHA’s April 2026 Delaware Mortgage Program rebrand.
- Delaware Mortgage Credit Certificate (MCC) program – the federal tax credit for Delaware first-time buyers that ended August 15, 2025. Many national sites still reference it as active. Our MCC page explains how it worked and when it ended.
FAQ: DSHA Welcome Home Mortgage Loan Program Delaware
What is the DSHA Welcome Home mortgage loan program in Delaware?
The DSHA Welcome Home mortgage loan program is a 30-year fixed-rate first mortgage offered through the Delaware State Housing Authority’s Delaware Mortgage Program for first-time homebuyers in Delaware. It pairs a below-market interest rate with one of five down payment assistance options: Smart Start (no DPA), First State Home Loan (3%), Keys4You (4%), Take5 (5%), and Diamond in the Rough (5% with FHA 203k Limited renovation). All DPA options are zero-interest deferred second mortgages with no monthly payments. Minimum credit score is 620 (660 for manufactured homes). Welcome Home requires application through a DSHA-approved lender – DSHA does not accept loan applications directly.
Who qualifies as a first-time buyer for DSHA Welcome Home?
A first-time homebuyer under DSHA Welcome Home is defined as a borrower who has not owned a primary residence at any point in the past three years. Owning a home more than three years ago does not disqualify you. Two exceptions allow repeat buyers to qualify under Welcome Home: qualified veterans (active duty, honorably discharged, eligible surviving spouses) and buyers purchasing in DSHA-designated targeted census tracts. If your borrower income exceeds Welcome Home county limits, or you have owned within the past three years and are not a qualified veteran or buying in a targeted area, the DSHA Open Door program is the alternative path for repeat or higher-income buyers.
What are the DSHA Welcome Home income limits for 2026?
DSHA Welcome Home 2026 income limits are: New Castle County non-targeted – $122,700 for 1-2 person households, $141,105 for 3 or more persons. Kent and Sussex Counties non-targeted – $111,400 for 1-2 person households, $128,110 for 3 or more persons. Targeted area limits are roughly 20% higher and waive the first-time buyer requirement. As of April 15, 2025, DSHA Welcome Home counts only the income of borrowers on the Note and/or Mortgage – household members not on the loan do not contribute to the qualifying income calculation. Household size still sets the limit tier. If qualifying income exceeds these limits, DSHA Open Door has higher thresholds: in New Castle County non-targeted, $147,240 for 1-2 person households and $184,050 for 3 or more; in Kent and Sussex, $133,680 and $167,100.
What credit score do I need for DSHA Welcome Home?
DSHA Welcome Home requires a minimum 620 credit score for most loan types. Manufactured homes require a higher minimum 660 credit score. Borrowers with credit scores between 620 and 659 must complete an 8-hour HUD-approved housing counseling course (typically a $125 fee) before closing. Borrowers with scores of 660 or higher are exempt from the housing counseling requirement. If your credit score is below 620, ask about credit improvement strategies – sometimes 30-90 days of targeted credit work can move a borrower above the 620 floor. Note that even with a 580 FICO, FHA itself allows financing – but DSHA Welcome Home layers a higher 620 minimum on top of FHA’s underwriting overlay.
Can I get DSHA Welcome Home after a Chapter 7 bankruptcy in Delaware?
Yes, DSHA Welcome Home allows buyers to qualify after a Chapter 7 bankruptcy provided the bankruptcy was discharged at least two years ago and credit has been re-established to a minimum 620 FICO (660 for manufactured homes). FHA underlying loans require a 2-year wait from discharge with re-established credit; VA underlying loans typically also use the 2-year benchmark. Chapter 13 bankruptcies have different rules – buyers may qualify before discharge in some cases with court approval and 12 months of on-time payments. Recent collections, charge-offs, or judgments will be evaluated case-by-case during underwriting and may need to be paid or addressed before closing.
Can I use gift funds with DSHA Welcome Home?
Yes, DSHA Welcome Home permits gift funds from family members or qualified donors as a source for the buyer’s contribution and closing costs. Gift funds must be properly documented with a gift letter (from the donor confirming the gift is not a loan) and a paper trail showing the funds clearing into the buyer’s account before closing. Gift funds layer on top of DSHA DPA – for example, a buyer using Welcome Home with Take5 (5% DPA) could also receive gift funds from a parent to cover closing costs not absorbed by the DPA. Gift funds from interested parties (sellers, real estate agents, builders) are NOT allowed; gifts must come from family or other approved donors.
Can DSHA Welcome Home be used for a manufactured home in Delaware?
Yes, but with three constraints. (1) Minimum 660 credit score required (higher than the standard 620 Welcome Home minimum). (2) FHA must be the underlying first mortgage type – VA, USDA, and Conventional are not allowed for manufactured homes under DSHA. (3) The home must be double-wide or larger; single-wide manufactured homes are not eligible. Diamond in the Rough is NOT available for manufactured homes – if you need 5% DPA on a manufactured home, use Take5 instead. The manufactured home must also be titled as real estate (not personal property) and meet HUD’s permanent foundation requirements.
Can I combine DSHA Welcome Home with seller credits or closing cost help from the seller?
Yes, DSHA Welcome Home allows seller credits in addition to DSHA DPA. The seller credit is negotiated as part of the purchase contract and applied at closing toward the buyer’s closing costs and prepaids. Combining Welcome Home + Take5 (5% DPA) + a 3% seller credit can result in a buyer arriving at closing with very little out-of-pocket cash – sometimes literally $0 to a few hundred dollars. Seller credit limits are set by the underlying loan type: FHA allows up to 6% seller credit, VA allows up to 4%, Conventional allows up to 3% on owner-occupied primary residences. The DSHA DPA does not count against these seller credit limits.
Can I combine DSHA Welcome Home with the Mortgage Credit Certificate?
No – the Delaware Mortgage Credit Certificate (MCC) program ended August 15, 2025 and is no longer accepting new applications. Many national sites, mortgage blogs, and even accountants still reference the MCC as active, which is why so many buyers still ask about it. The MCC tax credit is no longer available on new loans in Delaware. If you closed on a Delaware MCC before August 15, 2025, you can still claim the existing tax credit on your federal return as long as you continue to occupy the property as your primary residence and remain in the original mortgage. For details on how the program worked and when it ended, see the Delaware Mortgage Credit Certificate page.
How do I apply for the DSHA Welcome Home loan program?
Apply through a DSHA-approved lender – DSHA does not accept loan applications directly. The John Thomas Team is a DSHA-approved lender in Newark, Delaware. The process: (1) call 302-703-0727 or schedule a free 30-minute consultation at schedule.johnthomasteam.com/30min, (2) submit a loan application online at applywithjohnthomasteam.com or by phone with our team, (3) we run credit and underwrite to a Welcome Home pre-approval letter, (4) you shop with a Realtor familiar with DSHA loans, (5) once under contract, the appraisal and title work begin and the file moves into formal underwriting, (6) DSHA program approval is added to standard lender approval, (7) you close – signing the Welcome Home first mortgage and the DPA second mortgage simultaneously. Total timeline typically runs 30 to 45 days from application to closing for a clean transaction.
About the Author
John R. Thomas | NMLS #38783 DSHA Approved Lender First-Time Buyer Specialist Author
Branch Manager & Division Vice President of Sales, John Thomas Team with AnnieMac Home Mortgage
John R. Thomas is a DSHA-approved mortgage loan officer with the John Thomas Team in Newark, Delaware. With over 20 years of mortgage experience and 3,000+ Delaware buyers helped, John has been originating DSHA Welcome Home loans since the program’s earliest Revenue Bond form – through every rebrand, every DPA product update, and every income limit change. He has personally closed more than 1,000 DSHA loans across all three Delaware counties.
John holds a BS in Physics Education from the University of Delaware and an MS in Curriculum and Instruction from Delaware State University. He is the author of Your Guide to Buying Your First Home in Delaware (in print since 2010) and host of the Delaware Home Buyer Seminar. He specializes in DSHA programs, FHA, VA, USDA, and first-time homebuyer loans across Delaware and Maryland.
Stats: 20+ Years in Delaware Mortgages | 3,000+ Buyers Helped | 1,000+ DSHA Loans Closed | Reviews on Google | CMP Certified Mortgage Planner
Licensing: Licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA). NMLS #38783. Operational service area for delawaremortgageloans.net is Delaware and Maryland.
John Thomas Team with AnnieMac Home Mortgage
Contact: 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com | Schedule Appointment | About John Thomas | YouTube Channel | See John Thomas Team on Google for reviews, directions, and local office information
YouTube · Facebook · Instagram · TikTok · X / Twitter · LinkedIn
Ready to Apply for DSHA Welcome Home?
If you’re a first-time homebuyer in Delaware and you’ve made it this far, you already know more about DSHA Welcome Home than 95% of buyers do when they first call. The next step is a 15-30 minute conversation to confirm Welcome Home fits your situation, identify which of the five DPA options gives you the best outcome, and start the pre-approval. No pressure, no obligation, no cost.
Last Updated: September 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
John R. Thomas, NMLS #38783 | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net | Equal Housing Lender
Copyright John R. Thomas, All Rights Reserved.
