Gift Funds and Gift of Equity for Delaware Home Buyers (2026)
Quick Answer for Delaware Buyers: Gift funds let a family member, fiance, domestic partner, or in some cases a close friend or employer help cover your down payment or closing costs on a Delaware home purchase. A gift of equity works differently: a relative selling you their home prices it below market value, and the difference acts as your down payment. Rules vary by loan type. Conventional, FHA, VA, and USDA each have their own donor list and documentation standard. The 2026 IRS annual gift tax exclusion is 19,000 dollars per recipient.
Current as of May 2026.
If saving for a down payment is the wall between you and your first Delaware home, you are not alone. According to the National Association of Realtors 2025 Profile of Home Buyers and Sellers, 22 percent of first-time buyers received help from relatives or friends through a gift or loan toward their down payment. In Delaware, where home prices have risen faster than wages for most of the last decade, that number is meaningful. A 30,000 dollar gift from a parent or grandparent can be the difference between renting another year and closing on a home.
My name is John Thomas, NMLS #38783. I have helped Delaware families finance their homes for more than 20 years, and I have closed hundreds of loans where part or all of the down payment came from a gift. The good news is that gift funds are common, well-understood by underwriters, and fully allowed by every major loan program. The bad news is that the rules are technical and have changed a lot over the years. A donor source that was off-limits five years ago may be allowed today. A documentation standard that was acceptable in 2019 may now hold up your closing. This guide walks through the 2026 rules in plain English, by loan type, with the Delaware-specific notes that matter for your purchase.
Local Delaware Example
A first-time buyer purchasing a $300,000 home in New Castle County may use an FHA loan with a 3.5% down payment, which equals $10,500 before closing costs. If an eligible family member provides that $10,500 as a documented gift, and the buyer also qualifies for DSHA assistance, the buyer may be able to reduce the cash needed at settlement. Approval depends on credit, income, debt, property type, and full underwriting review.
We will review the donor, loan program, timing, and documentation before any gift money moves.
Table of Contents
What Is a Gift Fund and What Is a Gift of Equity?
A gift fund is money that someone gives you toward the purchase of a home with no expectation of repayment. It can pay all or part of your down payment, all or part of your closing costs, and on some loan programs it can sit in your account afterward as reserves. The key word is gift. If there is any expectation that you will pay the money back, even informally, it is not a gift. It is an undisclosed loan, and using it as down payment without telling the lender is mortgage fraud. That is why underwriters require so much documentation, and why the gift letter exists.
A gift of equity is a different mechanism that comes up when you are buying a home directly from a relative. Instead of selling you the home at its full market value, the relative sells it to you for less. The difference between the appraised value and the actual sales price is the gift of equity, and on most loan programs it counts as your down payment. You never see a check. The discount is the gift. Gift of equity is most common in family transfers where parents sell to adult children, or where one sibling buys out another, or where grandparents pass a home to a grandchild during their lifetime rather than through their estate.
Both mechanisms are allowed by every major loan program in 2026, but the rules around them differ in important ways. Below is how each program handles gifts in current 2026 guidelines.
Gift Fund Rules by Loan Program in 2026
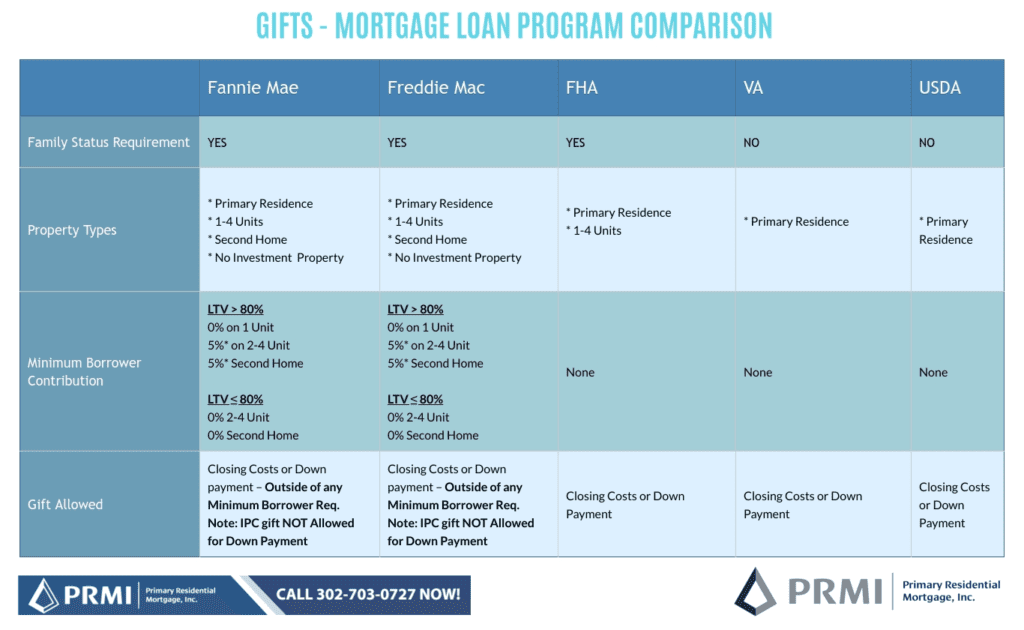
Every loan program has its own rulebook for gifts. The four programs we use most often in Delaware are conventional loans backed by Fannie Mae or Freddie Mac, FHA loans, VA loans for veterans, and USDA loans for rural and suburban Delaware. Here is how they compare in 2026.
| Rule | Conventional (Fannie/Freddie) | FHA | VA | USDA |
|---|---|---|---|---|
| Gift can cover full down payment? | Yes on a 1-unit primary residence | Yes, full 3.5 percent and more | Yes, gift can fund any voluntary down payment | Yes for closing costs (no down payment required) |
| Minimum borrower contribution? | None on most 1-unit primary residence loans; some programs require 5 percent borrower contribution on multi-unit or second homes | None; the entire Minimum Required Investment can be a gift | None | None |
| Donor pool | Family by blood, marriage, adoption, or legal guardianship; fiance, domestic partner; in many cases a non-relative with a documented close relationship | Family, employers, labor unions, charitable orgs, close friends with documented relationship, government agencies | Family, fiance, employer, nonprofit, charitable org, government agency | Generally follows conventional donor rules |
| Interested parties allowed as donor? | No (seller, agent, builder, lender) | No | No | No |
| Gift of equity allowed? | Yes, from an acceptable donor | Yes, from a family member | Yes, from a family member | Yes, from a family member |
| Can gift be used for reserves? | Yes on primary residence and second home; no on investment property | Leftover gift in account post-closing can count as reserves on automated underwrite | Yes for required reserves | Limited; check with lender |
The big takeaway: FHA has the most generous donor list and is often the right answer when the buyer is leaning heavily on gifted funds. Conventional has gotten more flexible since Fannie Mae expanded the donor definition in 2022, but it is still stricter than FHA on who counts. VA and USDA do not require a down payment in the first place, so gifts on those programs typically cover closing costs, the funding fee, or a voluntary down payment if you want one.
Want to dig deeper on each program? See our guides to Delaware conventional loans, Delaware FHA loans, Delaware VA loans, and Delaware USDA rural loans.
Gift Fund Rules by Property Type
Gift fund rules also depend on what kind of property you are buying, not just which loan program you use. A gift that is perfectly acceptable on a primary residence may be limited or completely disallowed on a second home or investment property. Here is the breakdown.
| Property Type | Conventional | FHA | VA |
|---|---|---|---|
| Primary residence (1 unit) | Full down payment can be a gift; no minimum borrower contribution on most programs | Full Minimum Required Investment can be a gift | Full voluntary down payment can be a gift |
| Primary residence (2-4 units) | Some programs require a 5 percent borrower contribution before gifts apply | Allowed within FHA multi-unit limits | Allowed; subject to VA multi-unit occupancy rules |
| Second home / vacation | Gifts allowed; some programs require a 5 percent borrower contribution | Not eligible (FHA requires owner-occupancy) | Not eligible (VA requires owner-occupancy) |
| Investment property | Not allowed. Fannie Mae does not permit gift funds on investment property transactions. | Not eligible (FHA requires owner-occupancy) | Not eligible (VA requires owner-occupancy) |
The investment-property exclusion catches a lot of buyers off guard, especially family members trying to help an adult child buy their first rental property. On Fannie Mae’s rules, gift funds are explicitly prohibited on investment-property purchases. If your strategy is to buy a rental, you will need to source the down payment from your own funds, a documented loan secured by other assets, or partnership financing, not from a family gift.
Who Can Give You a Gift on a Delaware Mortgage?
The 2019 version of this article said gifts had to come from a parent, grandparent, or sibling. That was never quite right, and it is definitely not right today. In 2026 the donor pool is much broader, especially on FHA loans. Here is who is generally acceptable across the four major programs.
Conventional loans (Fannie Mae and Freddie Mac)
- Your spouse, domestic partner, fiance, or fiancee
- Your child, including biological, adopted, step, or foster
- Your parent, grandparent, or great-grandparent, including biological, adoptive, step, or foster
- Your sibling, including step, half, foster, or adopted
- Your aunt, uncle, niece, or nephew, including step relatives
- Your in-laws (parents, grandparents, siblings, and future in-laws if you are engaged)
- A godparent, a relative of your domestic partner, a former relative
- In some scenarios, a non-relative who has a long-documented relationship with you that is family-like or mentorship in nature
FHA loans
- Family members as defined by HUD: parents, grandparents, children, siblings, aunts, uncles, stepparents, in-laws, spouses, and domestic partners
- Your current employer, as part of a housing assistance or retention program
- Your labor union
- A close friend with a clearly documented interest in you (not in the property)
- A charitable organization
- A government agency or public entity running a homeownership assistance or first-time buyer program
VA loans
The VA Lenders Handbook is permissive: any donor who is not affiliated with the builder, developer, real estate agent, or other interested party to the transaction can give you a gift. In practice this means family, fiance, employer, nonprofit, charitable organization, government agency, and in many cases a close friend with documented relationship.
USDA loans
USDA generally follows conventional donor rules. Family and family-like relationships are the usual sources. Interested parties to the transaction are not allowed.
Who is NEVER an acceptable donor on any program
The seller. The real estate agent on either side. The builder. The developer. The lender. Any party with a financial interest in the transaction closing. If the donor has a stake in whether the deal closes, the gift is not a gift in the eyes of underwriting. It is an inducement, and it has to be subtracted from the sales price under FHA rules or restructured under conventional rules.
Sellers can contribute to closing costs through a seller concession written into the contract, but that is a completely separate mechanism with its own caps and its own paper trail. It is not a gift and cannot be used for down payment.
What the Gift Letter Has to Say
Every gift requires a signed gift letter. The letter is the donor’s written, dated statement to the lender that the money is a gift, not a loan. Without a complete gift letter, the funds cannot be used. With an incomplete letter, your underwriter will add a condition to the loan approval and your closing date will slide while you chase down the missing piece. Here are the seven elements every gift letter has to contain.
- Donor name, address, and phone number. Full legal name, current address, contact phone.
- Donor relationship to the borrower. “Mother of borrower.” “Maternal grandfather of borrower.” “Fiance of borrower.” Specific enough that underwriting can verify the relationship meets program rules.
- The exact dollar amount of the gift. Not “approximately” or “up to.” A specific number.
- The address of the property being purchased. Full street address, city, state, ZIP.
- An explicit statement that no repayment is expected. This is the legal heart of the letter. Without this line, the funds are presumed to be a loan.
- The source of the donor’s funds. Bank account, retirement account, sale of an asset, savings. The letter does not have to disclose dollar balances, but it does have to identify where the money came from.
- The donor’s signature and date. Wet signature or e-signature, either is fine, but it has to be signed.
If your donor is married, lenders often want both spouses to sign even if only one is the named donor, because the funds may be joint marital property. If you are getting a gift from in-laws while you are still engaged, the gift letter is allowed but the relationship has to be documented (engagement evidence) before closing.
Gift Letter Template You Can Use
Here is a template that meets the requirements of every major loan program. Your donor can copy and paste this into a Word document or email, fill in the bracketed fields, sign, and date it. Once you have the signed letter, send it to your loan officer along with the donor’s bank statement or canceled check showing the source of funds. Talk to me before sending if anything about the donor relationship or fund source is unusual; a quick review up front prevents most underwriting conditions later.
Gift Letter
Date: [Month Day, Year]
To: [Lender Name]
[Lender Address]
Re: Gift of funds for the purchase of property located at [Property Address, City, State, ZIP]
I, [Donor Full Legal Name], residing at [Donor Address, City, State, ZIP], confirm that I am giving the sum of $[Gift Amount] ([Amount Spelled Out] Dollars) to [Borrower Full Legal Name] for use toward the purchase of the property listed above.
My relationship to the borrower is: [e.g., parent, grandparent, sibling, fiance, fiancee, domestic partner, in-law, employer, etc.]
The source of these gift funds is: [e.g., my personal checking account, savings account, retirement account, sale of an asset, etc.]
I confirm that this is a true gift and no repayment is expected or required from the borrower, in any form, at any time. No part of this gift has been or will be obtained from any person or entity with an interest in the sale of the property (including the seller, real estate agent, builder, or loan officer).
The funds will be transferred to the borrower’s account via [check, wire transfer, electronic transfer] on or before [Date].
Signed: ___________________________________
[Donor Full Legal Name]
Phone: [Donor Phone]
Email: [Donor Email]
If your donor is married, both spouses typically sign even if only one is named as the giver. If anything about the donor situation is non-standard (former relative, godparent, non-relative with documented close relationship), let me look at the template before it goes out so we tailor the relationship language to what the underwriter on your loan program will accept.
The Paper Trail: How Lenders Verify the Money
The gift letter is only half the documentation. The other half is the paper trail proving that the money actually moved from the donor’s account to yours. This is where a lot of gifts get tripped up, almost always because the donor wants to be helpful and hands over cash. Cash is the one form of gift you cannot use, because there is no way for underwriting to confirm where it came from.
Acceptable proof of transfer in 2026 generally includes any of the following:
- The donor’s bank statement showing the withdrawal, paired with your bank statement showing the deposit
- A copy of the donor’s canceled check (front and back), paired with proof of deposit into your account
- A copy of the donor’s withdrawal receipt, paired with evidence of deposit
- A wire transfer confirmation from donor account to your account
- An electronic transfer record showing the funds moved from the donor’s named account to your named account
The FHA actually loosened its documentation requirements in 2024, opening up more options for proving the transfer. Conventional and VA documentation rules have stayed largely consistent. What has not changed across any program is the underlying principle: every dollar has to be traceable from a named, eligible donor to the borrower, and large deposits during the loan process that cannot be sourced will be excluded from your available funds.
Practical tip: have your donor wire the funds directly to your bank account, ideally before you start the loan application. A direct wire creates the cleanest paper trail and avoids the seasoning questions that come with deposits made during underwriting.
Seasoning and the 60-day rule
Lenders typically pull two months of bank statements during underwriting. Funds that have been sitting in your account for the full 60 days covered by those statements are considered seasoned and generally do not require additional documentation. Funds that arrive during that window, including gift money, are not seasoned and have to be sourced with the gift letter and the donor paper trail described above.
Two timing scenarios come up most often. First, if your donor transfers the gift more than 60 days before your loan application, the money may simply appear as part of your existing assets and underwriting may not even ask about it. The gift letter is still a good idea so the source is documented in case any question arises. Second, if the gift comes in during the loan process (after application but before closing), the gift letter and proof of transfer should go to your loan officer the same day. Large unexplained deposits during the loan window trigger automatic conditions.
The donor can also wire funds directly to the title company at closing, bypassing your bank account entirely. This is sometimes the cleanest option for a large gift that arrives close to closing. The gift letter is still required, but no deposit ever shows up on your bank statement to explain.
Gift of Equity Explained With an Example
A gift of equity comes up most often in family-to-family home sales. Picture this scenario: your parents own a home in Newark, Delaware that is appraised at 350,000 dollars. They are downsizing, and they want you to have the house. Instead of selling it to you at full market value, they sell it to you for 280,000 dollars. The 70,000 dollar discount is the gift of equity. On a Fannie Mae conventional loan, that 70,000 counts as a 20 percent down payment on the 350,000 dollar appraised value, even though you are only financing 280,000.
The transaction has to be set up correctly for this to work. A few key rules:
- The home must be appraised at the higher (market) value. The appraisal is what proves the equity gift exists.
- The contract must show the actual sales price, not the appraised value. Lender will use both numbers.
- A gift of equity letter is required, just like a regular gift letter, but adapted for an equity gift rather than a cash gift.
- The settlement statement at closing has to list the gift of equity as a credit to the buyer.
- The donor in a gift of equity must be an acceptable donor under the loan program’s regular gift rules. On FHA and most conventional programs that means a family member.
- A gift of equity does not require a paper-trail transfer, because no money changes hands. But it does require a clean appraisal and clean contract structure.
Gift of equity is not the same as buying a home below market on the open market. It only works in a family transfer, and the relationship has to be documented and acceptable under the program rules.
IRS Gift Tax in 2026: What Donors and Recipients Need to Know
Tax treatment of gifts is the area where the 2019 version of this article was most outdated, and where I see the most confusion among buyers. Here is the current 2026 picture in plain English. None of this affects whether you can use the money for your mortgage. The mortgage process and the tax process are separate. But you and your donor should both understand the tax piece so nobody is surprised at tax time.
The donor is the one with the tax issue, not the recipient
When you receive a gift, it is not taxable income to you. You do not report it on your tax return. The federal gift tax applies to the donor, not the recipient. That is the opposite of what the 2019 version of this article said, and it is a point a lot of buyers get wrong.
The 2026 annual gift tax exclusion is 19,000 dollars per recipient
A donor can give up to 19,000 dollars to any one person in calendar year 2026 with no IRS reporting required at all. Married couples can combine their exclusions and give up to 38,000 dollars to a single recipient without any reporting. So if both your parents jointly give you 38,000 dollars in 2026, that falls entirely within the annual exclusion. No Form 709. No tax owed. Nothing to disclose to the IRS.
Above the annual exclusion, the donor files Form 709, but usually owes no tax
If a single donor gives you 30,000 dollars, that is 11,000 dollars over the annual exclusion. The donor has to file IRS Form 709 (the gift tax return) for that year, but in almost every case they will not actually pay gift tax. The 11,000 dollar overage is simply applied against their lifetime gift and estate tax exemption, which sits at 15 million dollars per individual for 2026. For the vast majority of families, the lifetime exemption is so large that the annual filing is more of a paperwork item than a tax bill.
Gift of equity is treated differently
A gift of equity is technically a discount on a sale, not a cash transfer. For the donor (the family member selling you the home), the gift of equity may have capital gains implications if the home has appreciated, because they are still treated as selling the home at fair market value for capital gains purposes. The annual gift tax exclusion may also apply to the equity gift portion. This is genuinely complicated and one of the few places I tell clients straight up: talk to a CPA. The mortgage side is clean. The tax side is fact-specific to your donor’s situation.
I am a mortgage professional, not a CPA or tax attorney. Anything in this section is general information for planning purposes. For tax advice specific to your situation, work with a qualified tax professional.
How Gift Funds Work With DSHA Down Payment Assistance in Delaware
This is the Delaware-specific piece that most national gift-fund articles skip. The Delaware State Housing Authority (DSHA) runs a portfolio of down payment assistance programs that you can stack with a gift from family. Used together, a DSHA program plus a family gift can sometimes cover your entire down payment and most of your closing costs, leaving you to bring only a small amount to closing.
DSHA rebranded its program lineup in April 2026. The current active DSHA stack as of May 2026 includes:
- DSHA Welcome Home first mortgage track (first-time buyers)
- DSHA Open Door first mortgage track (repeat buyers)
- DSHA First State 3 percent down payment assistance
- DSHA Keys4You 4 percent down payment assistance (rebranded April 2026)
- DSHA Take5 5 percent down payment assistance (Welcome Home only)
- DSHA Diamond in the Rough 5 percent plus FHA 203(k) renovation (Welcome Home only, 640 minimum score)
The general DSHA minimum credit score is 620 (660 for manually underwritten or manufactured home loans). Diamond in the Rough has a higher 640 minimum. Income limits vary by county and household size and are published by DSHA.
The interaction with gift funds works like this: DSHA assistance pays your down payment (or a chunk of it) through a second-lien program. A gift from family can pay the rest of your down payment, your closing costs, prepaids like the first year of homeowners insurance, or the escrow setup. As long as your donor is an acceptable source under the underlying first-mortgage program (Welcome Home and Open Door both use FHA, VA, USDA, or conventional underwriting as the underlying first lien), the gift is allowed.
One Delaware-specific note worth flagging: if you are a Delaware first-time buyer, you may also qualify for the Delaware first-time buyer state transfer tax exemption, which reduces your share of the 4 percent state and county transfer tax. That is a separate savings layer on top of any gift or DSHA assistance, not a substitute for them.
What We Check Before You Move Gift Money
Before your donor sends any funds, a 15-minute call with us covers the questions that prevent the underwriting conditions and closing delays that come up most often on gift-funded files. Here is exactly what we review.
- Is the donor eligible under your loan program? Conventional, FHA, VA, and USDA each have different donor lists. We confirm before the gift letter is signed, not after.
- Can the gift cover what you need it to cover? Down payment, closing costs, prepaids, or reserves: not all programs allow gifts toward all four categories. We match your situation to the rules.
- Does the gift letter say what underwriting needs it to say? We review the relationship language, the repayment disclaimer, the source of funds, and the property identification before your donor signs.
- How and when should the funds move? Wire to your account, wire to the title company at closing, or check; with seasoning timing that makes sense for your loan calendar.
- What paper trail will the underwriter need? Donor bank statement, canceled check, wire confirmation, or electronic transfer record: we identify the cleanest option for your donor’s banking setup.
- Can the gift stack with DSHA assistance or other programs? If you might also qualify for DSHA, the order of operations matters; we plan the stack so the gift and the assistance both apply.
None of this is hard once it is mapped out, but doing it backwards or skipping a step is what causes last-minute closing conditions. Call 302-703-0727 or schedule a 30-minute consultation before your donor moves any money.
Common Mistakes That Delay or Kill the Loan
I have seen the same five or six gift-fund mistakes derail otherwise clean loans. Here is what to watch for.
- Cash deposits. Your donor hands you 20,000 dollars in cash. You deposit it. Underwriting sees a large unsourced cash deposit and excludes it from available funds. Always have the donor wire or write a check.
- Treating a gift as an informal loan. You and your donor have a private understanding that you will pay them back when you can. This is mortgage fraud, full stop, and it shows up if the lender ever pulls your bank statements later. Either get the gift in writing as a real gift, or do not use it.
- Accepting a gift from an ineligible donor. The most common version is the seller offering to gift you a portion of the down payment. That is not allowed on any program. It is an inducement to purchase and it has to be restructured as a seller concession (which has its own caps and rules).
- Submitting an incomplete gift letter. Missing relationship description, missing repayment disclaimer, missing signature, missing property address. Any of these adds a condition to your loan and pushes closing.
- Deposits during the underwriting window with no paper trail. Once you are in the loan process, every large deposit gets scrutinized. If a gift comes in during underwriting, get the gift letter and proof of transfer to your loan officer the same day. Do not wait.
- Assuming the rules are the same across programs. They are not. Your friend’s FHA loan let them use an employer gift; your conventional loan probably will not. Always confirm what is allowed before you commit to a donor.
When Using a Gift Is Not a Good Fit
Gift funds are a powerful tool, but they are not the right move in every situation. Reconsider, or talk through the alternative with us, if any of the following apply:
- The “gift” really is a loan and you and your donor both know it. Forcing it through as a gift is fraud and the consequences are much worse than just disclosing the loan.
- The donor is having second thoughts. A gift you regret accepting can poison a family relationship for years. If the donor is hesitant, do not push.
- The donor is in financial difficulty themselves. Drawing down their retirement or emergency fund to gift you a down payment can create stress that outlasts the closing.
- The only available donor is an interested party to the transaction (seller, agent, builder). Restructure as a seller concession or look at DSHA assistance instead.
- You are buying an investment property. Fannie Mae does not allow gift funds on investment property transactions. If your strategy is buying a rental, a gift is not the route.
- The gift would cover your down payment but you still cannot comfortably afford the monthly payment. The gift solves the closing-day problem, not the every-month problem. If your monthly housing budget is not sustainable, the gift just delays a harder conversation.
If any of these scenarios fit your situation, give me a call before you commit. There are almost always alternatives, whether that is a different loan program, a DSHA stack, a co-borrower structure, or simply waiting another six months while you build savings. The goal is getting you into a home you can keep, not just a home you can close on.
Gift Funds and Gift of Equity FAQ
Who counts as an acceptable donor on a conventional loan in 2026?
On a conventional loan backed by Fannie Mae or Freddie Mac, acceptable donors include your spouse, fiance, fiancee, domestic partner, child (including step, foster, or adopted), parent, grandparent, sibling, aunt, uncle, niece, nephew, in-laws (including future in-laws if you are engaged), godparent, relatives of your domestic partner, and former relatives. Since Fannie Mae expanded the donor pool in 2022, certain non-relatives with a documented long-standing family-like or mentorship relationship may also qualify. Sellers, real estate agents, builders, developers, and lenders cannot give you a gift on a conventional loan because they are interested parties to the transaction.
Who counts as an acceptable donor on an FHA loan?
FHA has the broadest donor list of any major program. Acceptable donors include family members (parents, grandparents, children, siblings, aunts, uncles, stepparents, in-laws, spouses, domestic partners), your current employer as part of a housing assistance or retention program, your labor union, a close friend with a clearly documented relationship to you, a charitable organization, and a government agency or public entity running a homeownership assistance program. The one absolute exclusion across FHA, just like every other program, is anyone with a financial interest in the transaction closing.
How much of my down payment can come from a gift?
On a one-unit primary residence with a conventional, FHA, or VA loan, 100 percent of your down payment can come from gift funds. There is no minimum borrower contribution. On a conventional multi-unit property or a second home, some programs require a 5 percent contribution from the borrower’s own funds before the rest can come from gifts. USDA loans typically have no down payment requirement at all, so gifts on USDA are usually directed at closing costs and prepaids rather than down payment.
What is the difference between a gift fund and a gift of equity?
A gift fund is cash that a donor transfers to you to help cover your down payment or closing costs. A gift of equity is a discount on the sale price when you are buying a home from a family member. The relative sells the home to you below its appraised market value, and the difference between the appraisal and the sales price is the gift of equity. The gift of equity counts as your down payment without you ever writing a check. Both mechanisms require a signed gift letter; gift funds also require a paper trail showing the money moved between accounts.
Will I owe taxes if my parents give me 30,000 dollars toward my down payment?
No, the recipient of a gift does not owe federal income tax on the gift itself. Your parents are the ones with a potential filing obligation. The 2026 annual federal gift tax exclusion is 19,000 dollars per donor per recipient. If both your parents jointly give you 30,000 dollars, that is within their combined annual exclusion of 38,000 dollars and no filing is required. If one parent gives you the full 30,000, they have to file IRS Form 709 for that year. In almost all cases they will not actually owe gift tax because the overage simply draws against their lifetime exemption of 15,000,000 dollars per individual. Talk to a CPA for advice specific to your family’s tax situation.
Can my real estate agent or builder give me gift money?
No. Anyone with a financial interest in your transaction closing is considered an interested party and cannot give you gift funds on any major loan program. That includes the seller, the listing agent, the buyer’s agent, the builder, the developer, and the lender. If a gift comes from an interested party, FHA treats it as an inducement to purchase and subtracts it from the sales price; other programs require it to be restructured as a seller concession with its own caps. Sellers can contribute to closing costs through a properly written seller concession, but that is not the same thing as a gift and cannot be used for the down payment.
Can my fiance or fiancee gift me money before we are married?
Yes, on most programs. Fannie Mae, Freddie Mac, FHA, and VA all accept gifts from a fiance, fiancee, or domestic partner. You will need to document the relationship, typically with an engagement disclosure or evidence of the domestic partnership. The gift letter should clearly state the relationship as fiance or fiancee, and the lender will treat the funds the same as a family gift for documentation purposes. Future in-laws (your fiance’s parents, grandparents, siblings) are also acceptable donors on a conventional loan as long as the engagement is documented.
How do gift funds work with DSHA down payment assistance in Delaware?
DSHA down payment assistance programs (Welcome Home, Open Door, Keys4You, First State 3 percent, Take5, Diamond in the Rough) provide a second-lien down payment loan or grant on top of your first mortgage. A family gift can stack on top of DSHA assistance to cover the rest of your down payment, your closing costs, and prepaid items like homeowners insurance and escrow setup. The gift has to follow the donor rules of your underlying first-mortgage program (FHA, VA, USDA, or conventional). Combined with DSHA, a gift may reduce the cash needed at closing, depending on program eligibility and full underwriting review. Call us at 302-703-0727 and we can map out the stack for your specific scenario.
Do gift funds have to be seasoned for 60 days before closing?
Not necessarily. Seasoned funds (money that has been sitting in your account for the 60 days covered by the bank statements your underwriter pulls) generally do not require additional documentation. Gift funds that arrive during that 60-day window are not seasoned and have to be sourced with a signed gift letter and a clear paper trail showing the transfer from donor to borrower. The 60-day rule is about documentation, not about whether you can use the gift. If your donor wires the gift directly to the title company at closing instead of into your bank account, no seasoning question arises at all because the funds never appear on your statements. Always get the gift letter completed whether the gift is seasoned or not.
Can I use gift funds on an investment property purchase?
No. Fannie Mae does not permit gift funds on investment property transactions. If you are buying a rental property, the down payment has to come from your own funds, a documented loan secured by other assets you own, or partnership financing. FHA and VA both require owner-occupancy, so they do not finance investment properties to begin with. The investment-property gift fund exclusion catches a lot of family members off guard, especially parents trying to help an adult child buy their first rental. If a rental purchase is the goal, talk to us early about alternative down payment sources so the strategy is set up correctly from the start.
Ready to Talk Through Your Gift Fund Strategy?
Every gift fund scenario is a little different. The donor relationship, the loan program, the documentation, the timing, the interaction with DSHA or other assistance, the tax piece: it all needs to line up. The fastest way to know whether your specific scenario works is to talk it through with a loan officer who has handled gift-funded closings hundreds of times. Call me directly at 302-703-0727, schedule a 30 minute consultation, or apply online to get a pre-approval started.
About the Author
NMLS #38783 Verified 21+ Years Experience Certified Mortgage Planner DE / MD / 17-State License
John R. Thomas, NMLS #38783 is a Certified Mortgage Planner and Senior Loan Officer leading The John Thomas Team. With more than 21 years in the mortgage industry, John has helped thousands of Delaware and Maryland families finance their homes through FHA, VA, USDA, conventional, DSHA, and renovation programs. He has closed hundreds of gift-funded purchases and is one of Delaware’s most-referenced specialists for first-time home buyer financing.
John holds a Bachelor of Science in Physics Education from the University of Delaware and a Master of Science in Curriculum and Instruction from Delaware State University. His teaching background is the reason every loan starts with education: clients leave the first call understanding how their loan works, what their options are, and what they will owe before they sign anything. He is licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA) and serves clients primarily across Delaware and Maryland.
The John Thomas Team
248 E Chestnut Hill Rd, Newark, DE 19713
Phone: 302-703-0727 | Email: team@johnthomasteam.com
See The John Thomas Team on Google | Verify NMLS #38783 on NMLS Consumer Access
Facebook | Instagram | YouTube | LinkedIn | TikTok
Mortgage content reviewed by John R. Thomas, NMLS #38783.
Last Updated: May 27, 2026
The John Thomas Team | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | NMLS #38783 | Licensed by the Delaware State Bank Commissioner | Equal Housing Lender | (c) 2026
John R. Thomas, NMLS #38783 | John Thomas Team with AnnieMac Home Mortgage | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
AnnieMac Home Mortgage is an Equal Housing Lender. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access.
(c) Copyright John R. Thomas, All Rights Reserved.
