
Last updated: April 1, 2026
VA One-Time Close Construction Loan (2026 Guide)
If you’ve earned VA loan benefits and want to build a custom home instead of buying an existing one, the VA One-Time Close Construction Loan makes it possible. Also known as a VA construction-to-permanent or single-close construction loan, this program lets eligible veterans, active-duty service members, and surviving spouses finance the land, construction, and permanent mortgage in one loan—with no down payment required.
Who is Eligible? The John Thomas Team specializes in VA One-Time Close Construction Loans in Delaware and Maryland. Whether you’re building in New Castle County, Kent County, Sussex County, or anywhere across Maryland’s Eastern Shore and suburbs, we guide veterans through the entire process — from pre-approval to move-in.
I’m John Thomas (NMLS 38783), a mortgage loan officer specializing in VA and construction financing. My team helps veterans nationwide navigate the build-your-own-home process using this powerful VA benefit. Call me at 302-703-0727 to talk to a VA Lending Specialist about a VA Construction Loan or get started online at APPLY ONLINE
Quick Answer: What is a VA One-Time Close Construction Loan?
A VA One-Time Close Construction Loan combines land purchase, construction financing, and a permanent 30-year VA mortgage into a single loan with one closing. Eligible veterans in Delaware and Maryland can build a custom home with $0 down payment, no monthly PMI, and a rate locked before construction begins — with no re-qualification required when the home is complete.
Who qualifies: Veterans, active-duty service members, National Guard/Reserve, surviving spouses with a valid COE |
Min. credit score: 620 |
Down payment: $0 with full entitlement |
Available in: Delaware & Maryland (and most U.S. states)
Table of Contents
What is a VA One-Time Close Construction Loan?
A VA One-Time Close (OTC) Construction Loan combines three phases into one transaction:
- Land purchase or payoff (if you already own land)
- Construction financing, paid to your licensed builder in draws
- Conversion to a permanent VA mortgage after completion
You close once, qualify once, lock your rate up front, and move in when the home is complete—without re-qualifying or paying a second set of closing costs.
Can You Buy Land and Build with a VA Loan?
Yes. A VA One-Time Close Construction Loan allows eligible veterans to finance both the land purchase and the cost of construction in a single loan. If you already own the land, its value may be used as equity toward the overall project.
This is one of the biggest advantages of a VA construction loan — instead of needing separate financing for land and construction, everything is combined into one closing with one long-term mortgage. This structure is often referred to as a construction-to-permanent loan, where the land purchase, construction financing, and permanent mortgage are all combined into one transaction. You can already own the land as well and use a VA OTC to build the home.
Key Benefits of VA OTC Construction Loan
Like most other VA home loans, VA one-time close construction loans require the borrower to occupy the home once it’s finished. The Veteran must also be the primary occupant of the home, with provisions being made for those who are called to active duty service, deployments and other types of military duty that requires the Veteran to be away.
Another thing you must know: most VA loan transactions will require a VA loan funding fee. However, Veterans who are eligible to receive VA disability benefits may get the dual benefit of no down payment and no VA loan funding fee.
- Zero down payment: finance up to 100% of land + build costs + closing costs if supported by appraised value.
- Single closing: one set of documents for land, construction, and permanent mortgage.
- Fixed-rate protection: lock your interest rate before construction begins with Float Down Option at End of Construction.
- No monthly mortgage insurance (PMI).
- Minimum 620 Credit Score but can go lower with compensating factors.
- No DTI Limit — must meet VA Residual Income Requirement.
- PRMI will allow use anywhere in the U.S. for a primary residence except New York.
- No mortgage payments during construction. Payments begin when home is complete and Certificate of Occupancy (CO) is issued.
- No Loan Limits for 100% financing with Full VA Entitlement.
- No Re-Qualification at the end of construction for the permanent VA Loan.
Who Is Eligible
- Eligible veteran, active-duty, National Guard/Reserve, or surviving spouse with a valid Certificate of Eligibility (COE)
- Primary residence only (1–4 units if you will occupy one unit)
- Credit score: 620 minimum (can go lower with compensating factors)
- Debt-to-income: up to 50% but can go higher if residual income requirements are met
- Builder must be licensed, insured, and experienced
- Property must meet VA Minimum Property Requirements (MPRs) upon completion
VA Residual Income Requirements for Construction Loans
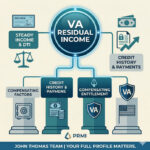
Unlike conventional loans that rely solely on your debt-to-income ratio, VA loans use a two-part qualification test: DTI ratio AND residual income. Residual income is the money left each month after paying estimated taxes, the full housing payment, and all major debts. It is often the real approval gate on a VA loan.
For VA construction loans, residual income is calculated using the estimated permanent mortgage payment — not construction draws — so your underwriter models what your monthly payment will look like once the home is complete and you move in. Veterans building in Delaware and Maryland fall under the Northeast region residual income thresholds set by the VA.
As a general benchmark, a Northeast region family of four with a loan over $80,000 needs at least $1,025/month in residual income after all obligations are paid. If your DTI exceeds 41%, most lenders require your residual income to be at least 20% above the minimum threshold to compensate. Having strong residual income can offset a higher DTI — and this is why two borrowers with identical credit scores can qualify very differently.
Call 302-703-0727 to run your residual income numbers before committing to a build budget — knowing your ceiling early prevents costly surprises during underwriting.
How the Process Works (Step-by-Step)
- Pre-approval & COE: Verify VA eligibility and get pre-approved with a lender experienced in VA OTC construction.
- Select lot and builder: Choose a licensed, insured contractor; finalize plans, specs, and budget. Build on owned land or purchase land at closing.
- Underwriting & appraisal: Lender reviews the package; VA appraiser values the proposed construction.
- Single closing: Close once on the combined land + construction + permanent loan. Funds go into a construction escrow.
- Construction & draws: Lender releases funds in stages after inspections. Payments may be interest-only or deferred until completion depending on program.
- Final inspection & conversion: After certificate of occupancy, the loan converts to a standard VA mortgage without re-qualification.
How Construction Draws Work
After closing, funds are held in a construction escrow and released to your builder in stages as work is verified. Each draw is tied to a construction milestone — typically foundation, framing, rough mechanicals, drywall, and final completion. Before each draw is released, the lender is required by the VA to obtain your written approval per VA Circular 26-18-7. You are not a passive bystander — you sign off on each stage.
The interest reserve — the interest that accrues during the construction period — is typically included in the builder’s contract and financed into the total loan amount. This is why you make no out-of-pocket mortgage payments while your home is being built. If the build runs significantly longer than the approved timeline, the reserve can be depleted and the borrower may become responsible for the remaining interest — another reason to choose a builder with a proven track record of finishing on schedule.
Typical Loan Terms and Requirements (2026)
| Feature | VA One-Time Close |
|---|---|
| Loan type | 30-year fixed rate |
| Down payment | 0% (up to 100% financing based on reasonable value) |
| Max LTV | Up to 100% of reasonable value |
| Minimum credit score | Typically 620 (can go lower with compensating factors) |
| Loan amount limits | No VA loan limit with full entitlement; appraisal and lender guidelines apply |
| Construction period | Commonly up to 12 months; extensions may be possible |
| Prepayment penalty | None |
| Property type | 1-unit primary residence; some lenders allow up to 4 units |
| Land | Purchase land or build on land you already own |
VA Funding Fee for Construction Loans
The standard VA Funding Fee applies to construction loans like purchase loans and can be financed into the loan amount.
- First-time use (0% down): 2.15%
- Subsequent use (0% down): 3.30%
- Exemptions: veterans with qualifying service-connected disabilities
If you already own the land, its appraised value may count toward your equity position and can reduce or eliminate your VA funding fee. There is no monthly mortgage insurance on VA loans.
Builder and Property Requirements
- Builder must be licensed, insured, and provide a one-year builder’s warranty
- Plans must comply with state/local codes and VA MPRs
- Permanent foundation and standard utilities required
- Manufactured/modular may be eligible if permanently affixed and meets HUD/VA standards
- Construction period must meet lender and program timelines
- VA no longer requires builders to be registered with the VA
- No self-build allowed — the veteran cannot be their own builder
Fixed-Price Contract Requirement
VA construction loans require a fixed-price or fixed-cost construction contract — cost-plus contracts are not eligible. All labor, materials, permits, and site work needed to reach a certificate of occupancy must be included in the contract price before closing. This protects both the veteran and the lender from open-ended cost exposure during the build. Lock your scope early — change orders after closing require lender approval and can delay draws.
Can You Build a 2–4 Unit Property with a VA Construction Loan?
Yes, you can build a multi-unit property with a VA Construction Loan, but the Veteran must occupy one of the units as their primary residence. There are extra requirements from the VA to qualify to build a 2–4 unit property:
- Must have a 660+ Credit Score
- Cannot solely qualify from future rents on other units
- Must have 6 months reserves for VA Loan on 2–4 unit property
- If no previous rental experience, VA requires the Veteran to hire a property management company
- Land must be zoned for multi-unit density
- Builder must have experience building multi-unit properties
Property Types: What Is and Is Not Eligible
Property types typically eligible:
- Detached site-built (stick-built) homes — most common path
- Modular and hybrid modular construction
- Log homes — eligible as long as appraiser can get comparable sales
- Barndominiums — eligible as long as appraiser can get comparable sales
- Manufactured homes — eligible if permanently affixed and meets HUD/VA standards
- 2–4 unit owner-occupied properties (see requirements above)
Property types generally not eligible:
- Container homes and tiny homes
- Pre-starts — properties where permanent structural work (slab, footers, foundation) has already begun before closing
- Vacation homes or investment properties
- Properties exceeding approximately 10 acres
- Mixed-use or commercial properties
One-Time vs Two-Time Close vs Conventional
| Feature | VA One-Time Close | Two-Time Close | Conventional Construction |
|---|---|---|---|
| Closings | 1 | 2 | 2 |
| Re-qualification | No | Yes | Yes |
| Down payment | 0% (if eligible) | 0–5% (varies) | 5–20% |
| Rate lock | Before construction | Often after construction | Often after construction |
| PMI | No | No | Yes (if applicable) |
| Eligible borrowers | Veterans/eligible borrowers | Veterans/eligible borrowers | All qualified borrowers |
Challenges and Considerations
- Limited lender availability: not all lenders offer VA OTC construction
- More documentation required: plans, specs, draw schedule, builder package
- Appraisal timing: proposed-construction appraisals can take longer
- Change orders and cost overruns require lender approval and reserves
- Timeline risk: weather, supply, or labor issues can delay completion
VA Construction Loans in Delaware and Maryland
The John Thomas Team works directly with veterans building in New Castle County, Kent County, and Sussex County in Delaware, and throughout Maryland including Cecil County, Harford County, Baltimore County, and the Eastern Shore. Understanding the local market matters — lot availability, county permit timelines, local builder relationships, and zoning requirements all affect how smoothly a VA construction loan closes.
Delaware veterans benefit from a relatively streamlined permitting process compared to many other states, and buildable lots — particularly in Kent and Sussex counties — remain more accessible than in high-density markets. Maryland veterans building near the Pennsylvania border or in more rural counties will often find more lot availability than in the DC suburbs, where zoning complexity can add time to the approval process.
One advantage the John Thomas Team offers veterans in both states: we have worked with builders throughout Delaware and Maryland on VA construction files and can help you identify contractors who understand the VA draw process, maintain proper licensing and insurance, and have a track record of delivering on time. Call 302-703-0727 to talk through your specific county and build scenario before you start shopping lots.
Conventional One-Time Close Construction Loan — compare VA vs conventional for non-veterans or higher loan amounts
Jumbo One-Time Close Construction Loan — for high-value builds above standard limits
PRMI Land Loans — purchase your lot now, build later
Why Work with John Thomas
As a VA Construction Loan specialist, I help veterans in Delaware, Maryland and nationwide understand how to use their benefits to build, not just buy. My team coordinates with experienced builders, manages construction draws and inspections, and helps you close once—on time and without surprises.
Find out why so many veterans choose to work with Loan Officer and VA Home Loan Expert John Thomas, Call 302-703-0727 or apply online to see what you qualify for today.
VA Construction Loan Specialist | John Thomas Team at Primary Residential Mortgage
NMLS #38783 | Licensed in Delaware & Maryland | PRMI License: DE State Bank Commissioner #010608
Licensed DE & MD
VA Loan Specialist
Construction Loan Expert
Certified Mortgage Planner
John Thomas is a Delaware-based Senior Loan Officer and Certified Mortgage Planner with Primary Residential Mortgage (PRMI) specializing in VA loans and construction financing for veterans throughout Delaware and Maryland. With 20+ years of experience and over 3,000 buyers served, John’s team manages the entire VA One-Time Close process — from pre-approval and builder coordination through construction draws and the final certificate of occupancy — so veterans close once, on time, without surprises.
John is also the author of Your Guide to Buying Your First Home in Delaware — available on Amazon — and conducts monthly homebuyer seminars attended by over 3,000 Delaware residents.
VA One-Time Close Construction Loan — Key Facts (2026)
| Down Payment | $0 with full VA entitlement (100% financing) |
| Number of Closings | 1 (land + construction + permanent mortgage) |
| Rate Lock | Before construction begins (float-down option available) |
| Mortgage Payments During Build | None — payments start after CO is issued |
| Mortgage Insurance (PMI) | None |
| Min. Credit Score | 620 (lower with compensating factors) |
| Loan Limits | No limit with full entitlement |
| VA Funding Fee (1st use, 0% down) | 2.15% (waived for veterans with service-connected disability) |
Questions? Call 302-703-0727 or apply online to speak with John Thomas, VA Construction Loan Specialist.
FAQ – VA One-Time Close Construction Loan: Quick Answers
As a VA-certified construction lender, the John Thomas Team provides 100% financing for veterans building new homes in Delaware and Maryland. Our “Single-Close” process locks your rate upfront and requires $0 down for land and construction.
Can I use a VA One-Time Close loan to buy land and build?

Yes. You can purchase land at closing or build on land you already own. The land value is included in the appraisal and financing.
Do I need a down payment?
Qualified veterans can finance up to 100% of the land and construction costs plus closing costs if the appraised value supports it.
Can I act as my own builder?
No, you are not allowed to be your own builder on any One-Time Close Construction Loan. You must hire an experienced builder.
Are manufactured or modular homes eligible?
Yes, if built to HUD/VA standards, placed on a permanent foundation, and approved by the lender then it will be eligible for a VA OTC Construction Loan.
Do I make payments during construction?
No mortgage payments are required during construction. Mortgage payments start once home is complete and CO has been issued.
What happens if construction goes over budget?
Lenders often require a contingency reserve (for example, 5–10%) for unexpected costs. Change orders must be approved before additional draws are released.
How long does construction take?
Most projects take 6–12 months, depending on weather, materials, permitting, and builder capacity.
What is a “One-Time Close” VA Loan?
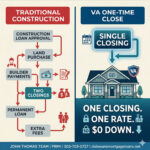
A VA One-Time Close (OTC) loan is a single mortgage that covers the purchase of the land, the construction phase, and the permanent 30-year mortgage.
One Closing: You sign papers once before construction begins.
One Rate: Your interest rate is locked upfront with a “float-down” option if rates drop.
No Payments: You typically make no mortgage payments during the construction period.
Can I build a home with a VA loan and no down payment?
Yes. With full VA entitlement, you can finance 100% of the land purchase and construction costs with $0 down. In 2026, there are no standard loan limits for veterans with full entitlement, meaning you can build a high-end custom home with no out-of-pocket down payment, subject to credit and income qualification.
What are the credit requirements for a VA construction loan in 2026?
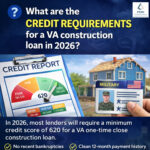
While many national lenders require a 640+ or 660+ score for construction, the John Thomas Team reviews the full profile. We look for “suitable credit” and focus heavily on VA Residual Income guidelines to ensure the veteran can comfortably afford the new home once built.
Related Programs and Resources
- VA Purchase Loan Program — learn more about standard VA purchases
- FHA One-Time Close Construction Loan — compare FHA vs VA construction
- USDA Construction Loan — rural build options
- VA Lenders Handbook – Chapter 7 (Construction Loans)
- VA Funding Fee Chart (official)
- VA Circular 26-18-7 (Construction Guidance)
