Delaware First Time Home Buyer Seminars: Free Monthly Class With John Thomas

Delaware first time home buyer seminars are free, 2-hour virtual classes taught monthly by John Thomas (NMLS #38783), author of Your Guide to Buying Your First Home in Delaware. The seminar covers DSHA Welcome Home, Open Door, Keys4You, Take5, Diamond in the Rough, First State, plus FHA, VA, USDA, and Conventional loans. Every attendee receives a complimentary soft credit pull – no hard inquiry, no FICO score impact. Current as of June 2026.
Quick Answer for Delaware Buyers
- Q: What is the Delaware First Time Home Buyer Seminar? A: A free 2-hour virtual webinar where you learn the full Delaware home buying process from a 20+ year Delaware mortgage lender.
- Q: Who teaches it? A: John Thomas, NMLS #38783, branch manager at Primary Residential Mortgage in Newark, DE, and author of Your Guide to Buying Your First Home in Delaware.
- Q: Will it affect my credit? A: No. Every attendee receives a complimentary soft credit pull. Soft pulls do not affect your FICO score and are not a hard inquiry.
- Q: How much does it cost? A: Free. No registration fee, no obligation, no sales pitch at the end.
- Q: How long has John been teaching this seminar? A: Since 2005. 586 seminars run. 21,092 Delaware buyers educated.
- Q: When are the next seminars? A: Saturday July 18, 2026 and Saturday August 15, 2026, both at 10:00 AM ET virtual.
- Q: Who should attend? A: Anyone in Delaware or Maryland considering buying a home in the next 3-24 months.
I’m John Thomas, NMLS #38783, branch manager at Primary Residential Mortgage in Newark, Delaware. I’ve been teaching the Delaware First Time Home Buyer Seminar – sometimes called a Delaware home buyer workshop, first-time buyer class, or homeownership webinar – since 2005. 586 sessions and 21,092 Delaware buyers later, the format has changed but the goal hasn’t: send you home understanding exactly how Delaware mortgage programs work, what you qualify for, and what your real next step is. No sales pitch, no pressure, no obligation. Just two hours of straight answers about buying a home in Delaware. If you’ve been wondering whether you can actually afford to buy, what DSHA’s down payment assistance really covers, or whether the home buying process is going to be as complicated as everyone says – the seminar exists for exactly that conversation.
Reserve Your Seat at the Next Free Delaware Home Buyer Seminar
Saturday July 18, 2026 – 10:00 AM ET – Virtual Webinar
Saturday August 15, 2026 – 10:00 AM ET – Virtual Webinar
Get Help From John Thomas – NMLS #38783
Have questions before the seminar? Call or schedule a one-on-one consultation with John. Team aims to respond within one business day.
Important – Is This DSHA-Required Counseling?
No. The Delaware First Time Home Buyer Seminar is educational only – it is not a HUD-approved housing counseling class and does not by itself fulfill the homebuyer education requirement that DSHA may require for certain programs and credit profiles.
If you are using a DSHA program that requires HUD-approved counseling (typically borrowers with FICO scores between 620 and 659 on Welcome Home, or as required by your specific program), you may still need to complete a separate counseling session through an agency on DSHA’s approved counselor list. The seminar will walk you through how to find a HUD-approved counselor in Delaware and what to expect.
What the seminar does cover: the full Delaware home buying process, current 2026 DSHA program details, credit, budgeting, down payment assistance, and what your real next step is. Most attendees still need the seminar even if they will later complete formal counseling separately – the two are not interchangeable.
Not Sure Which Step Is Right for You?
| Your Situation | Best Next Step | Action |
|---|---|---|
| 3-24 months out from buying | Free seminar + soft credit pull | Reserve your seat |
| 0-3 months out, ready to start | 30-minute one-on-one consultation | Schedule appointment |
| Already under contract, need pre-approval today | Call John directly | 302-703-0727 |
| Ready to apply for a Delaware mortgage | Start the secure online mortgage application | Apply online |
Table of Contents
Upcoming Delaware First Time Home Buyer Seminars
Below are the next confirmed Delaware first time home buyer seminars. Both sessions run 2 hours and are delivered as live virtual webinars – register through delawarehomebuyerseminar.com.
Saturday, July 18, 2026 – 10:00 AM ET
Format: Virtual Webinar (live, Zoom-based)
Duration: 10:00 AM – 12:00 PM ET (2 hours)
Cost: Free
Presenter: John Thomas, NMLS #38783, author of Your Guide to Buying Your First Home in Delaware
Includes: Complimentary soft credit pull for every attendee (no hard inquiry, no FICO impact)
Reserve your seat – July 18, 2026 seminar
Add to calendar: Google Calendar – iCal / Outlook
Saturday, August 15, 2026 – 10:00 AM ET
Format: Virtual Webinar (live, Zoom-based)
Duration: 10:00 AM – 12:00 PM ET (2 hours)
Cost: Free
Presenter: John Thomas, NMLS #38783, author of Your Guide to Buying Your First Home in Delaware
Includes: Complimentary soft credit pull for every attendee (no hard inquiry, no FICO impact)
Reserve your seat – August 15, 2026 seminar
Add to calendar: Google Calendar – iCal / Outlook
Future monthly dates are posted at delawarehomebuyerseminar.com as they are scheduled. Phone registration is also available: 302-703-0727.
Watch the Full 2-Hour Delaware Home Buyer Seminar
If you cannot attend a live session, the full 2-hour 38-minute Delaware First Time Home Buyer Seminar 2026 is available on YouTube below. Watching the recording is a good way to preview what the live seminar covers before you register – many attendees watch the recording first, then bring specific questions to the live session.
Recording uploaded May 13, 2026. Duration: 2 hours 38 minutes. The recording covers DSHA programs, FHA, VA, USDA, conventional loans, down payment assistance, credit, budgeting, and the full Delaware home buying process. Note: Watching the recording does not replace registering for a live session if you want the complimentary soft credit pull or want to ask live questions during the Q&A.
What You Will Learn at the Delaware Home Buyer Seminar
The seminar walks through every major step of buying a home in Delaware – in the order you will actually face them. It is built around 14 core topics that map to the questions Delaware buyers ask most often.
- How to build a Delaware home buying budget – how to back into your maximum monthly mortgage payment from your real take-home pay, with Delaware property tax and homeowners insurance built in.
- Credit scoring fundamentals + how to improve your score – the five factors of FICO, what actually moves your score, and what to stop doing once you start the mortgage process.
- The full Delaware home buying process – from pre-approval through underwriting, appraisal, title, and closing. Where buyers get stuck and how to avoid it.
- Delaware mortgage program comparison – FHA, VA, USDA, Conventional, Jumbo, and Non-QM options side-by-side. Which program fits which buyer.
- DSHA Welcome Home and Open Door – the two DSHA first-mortgage tracks after the April 2026 program rebrand. Welcome Home is first-time buyers only; Open Door covers first-time and repeat buyers.
- DSHA down payment assistance – Keys4You (4%), Take5 (5%, Welcome Home only), First State (3%), Diamond in the Rough (5% + FHA 203k Limited, Welcome Home only), Smart Start (unassisted). Which DPA pairs with which first mortgage.
- 2026 DSHA income limits by county + purchase price caps – what household composition and county determine your eligibility, and what changed under the April 15, 2025 income calculation rule (only borrowers on the Note/Mortgage count for Welcome Home, not all household adults).
- 2026 Delaware FHA loan limits – $630,200 for one-unit New Castle County, $541,287 for Kent and Sussex Counties. What this means for your purchase price ceiling.
- Delaware transfer tax explained – the standard 2% buyer / 2% seller split under the DAR contract, plus the builder-contract warning (some Delaware builders write contracts requiring the buyer to pay the full 4%, which can change your closing-cost math by $5,000-$10,000 on a typical Delaware purchase).
- What replaced the Delaware Mortgage Credit Certificate (MCC) program – the MCC ended August 15, 2025. The seminar covers what filled the gap and how DSHA’s current programs deliver similar benefits.
- Tax advantages of owning a Delaware home in 2026 – mortgage interest deduction, property tax deduction, and the One Big Beautiful Bill Act (OBBBA) changes that took effect in 2025-2026.
- How to choose a Delaware mortgage lender – what to verify (NMLS, local office, Delaware-specific program approval), what to ask, and how to spot a lender who will hand you off to a national call center mid-loan.
- How to choose a Delaware real estate agent – what experience to look for in a Delaware buyer’s agent and how the buyer-agent relationship works under current real estate rules.
- Negotiating seller-paid closing costs – how much you can ask for under each loan program (FHA, VA, USDA, Conventional, DSHA) and when sellers actually agree to pay.
Plus a live Q&A at the end where you can ask anything specific to your situation.
Every Attendee Gets a Complimentary Soft Credit Pull – No FICO Impact
What is a soft credit pull? A soft credit pull (also called a soft inquiry) is a credit check that does NOT affect your FICO score and does NOT appear as an inquiry on your credit report visible to other lenders. It is the opposite of a hard credit pull, which lenders run when you formally apply for a mortgage and which typically causes a small temporary FICO dip of 2-5 points per inquiry.
One thing that genuinely sets this seminar apart: every attendee receives a complimentary soft credit pull as part of attending. This is not a hard inquiry – it does not affect your FICO score and does not appear as an inquiry on your credit report visible to other lenders.
Soft pulls let you see exactly where your credit currently stands so you can plan around it. If your scores are already in the ballpark for the programs you want, we can talk about what is the right next step. If your scores are not quite there yet, we can talk about what specifically would move them up the most before you actually start a mortgage application. Either way you walk away with real numbers instead of guesses.
This matters because most Delaware buyers I talk with have never seen a real soft pull of their credit before. The free credit-monitoring apps (Credit Karma, Experian free, etc.) typically use VantageScore, which can be 20-100 points off from the FICO score mortgage lenders actually use. The seminar’s soft pull uses mortgage-grade FICO scores from all three bureaus – the same model your lender will use when you apply for real.
The 3 Things Mortgage Lenders Review
Most mortgage decisions come down to three areas. Once you understand these three, the whole approval process makes more sense – and you can see exactly where you stand before you start touring homes.
Income: Can your income support the monthly payment? Lenders look at steady employment history (typically 2 years), the type of income (W-2 wages, self-employment, overtime, bonuses, commission), and whether the income is likely to continue. Self-employed buyers usually need 2 years of tax returns; W-2 buyers typically need recent pay stubs plus W-2s.
Assets: Do you have enough funds for the down payment, closing costs, and any required reserves? Eligible asset sources include checking, savings, money market, CDs, retirement accounts (401k, 403b, TSP, IRA), and documented gift funds from family. Every large deposit on your bank statements needs to be sourced.
Credit: Does your credit profile fit the loan program? Lenders look at FICO scores from all three bureaus, payment history, account types, balances vs limits, and recent inquiries. Minimum scores vary by program – DSHA Welcome Home typically requires 620, FHA can go to 580 with 3.5% down (some products allow lower depending on overall profile), VA has no fixed minimum set by VA itself though lenders set overlays.
You may still qualify even if one area is not perfect. The goal at the seminar is to review the full picture and match your situation to the program that fits best, not to find one perfect number that gates everything. Approval depends on full underwriting review and program guidelines. Current as of May 2026.
What You’ll Know Before You Start Looking at Homes
Before you start touring homes, the goal is to know your numbers first. In the seminar, John walks through:
- how much home you may be able to afford
- how much down payment you may need for different loan programs
- what your estimated monthly payment may look like at different price points
- which loan programs may fit your credit, income, assets, and timeline
- when to move from education into mortgage pre-approval
Pre-qualification vs pre-approval: these are different steps that get confused often. Pre-qualification typically involves a credit check and a verbal review of your income and assets – it gives you a general estimate but does not verify documentation. Pre-approval involves the full mortgage application, verified income, verified assets, and a credit review against loan-program guidelines. Pre-approval gives you stronger shopping confidence than pre-qualification, but it is not the same as final loan approval – final approval depends on full underwriting review, property appraisal, and program guidelines.
You do not have to guess at any of this. Once you understand your numbers, it is easier to shop with confidence and avoid falling in love with a home that does not fit your budget.
Example: How Down Payment Assistance Can Change the Cash Needed
Numbers help more than abstractions. Here is a real example John walks through in the seminar:
A $400,000 Delaware Home Using FHA Financing
Without down payment assistance:
- 3.5% FHA down payment: approximately $14,000
- Estimated closing costs and prepaid items: approximately $15,000
- Total estimated cash needed before assistance: approximately $29,000
With DSHA Take5 (5% DPA) + seller-paid closing costs:
- DSHA Take5 down payment assistance: up to $20,000 (5% of $400,000) for eligible Welcome Home buyers
- Negotiated seller-paid closing costs: example $5,000
- Estimated total cash needed at closing: approximately $4,000
This is an illustrative example showing how DPA and seller-paid closing cost negotiation can reduce buyer cash-to-close. Actual amounts depend on DSHA program eligibility, full underwriting review, purchase price, property type, the specific FHA loan terms, and seller-negotiated terms. DSHA Take5 is available with Welcome Home first mortgages only, subject to DSHA income limits and purchase price limits. Current as of May 2026.
A buyer who does not have $29,000 saved may still have options. The seminar covers DSHA Keys4You (4%), First State (3%), Take5 (5%, Welcome Home only), Diamond in the Rough (5% + FHA 203k Limited, Welcome Home only), and Smart Start (unassisted) so you can see which programs your situation fits – and what cash you would actually need at closing for each.
Glossary for Delaware Home Buyers
Nine terms that come up repeatedly in the seminar – defined plainly so you can follow along whether you have heard them before or not.
- Delaware first time home buyer seminar: A free, 2-hour educational class taught by John Thomas covering Delaware mortgage programs, credit, budgeting, DSHA down payment assistance, and the full home buying process. Open to first-time and repeat buyers. Also called a Delaware home buyer class, first-time buyer workshop, or homeownership webinar.
- DSHA homebuyer education: The educational requirement set by the Delaware State Housing Authority for borrowers using certain DSHA programs (typically Welcome Home borrowers with FICO scores between 620 and 659, and as required by specific program rules). Satisfied through a HUD-approved housing counseling agency on DSHA’s approved counselor list, not through this lender-led seminar.
- HUD-approved housing counseling: One-on-one or group counseling provided by a nonprofit agency certified by the U.S. Department of Housing and Urban Development. HUD-approved counselors are trained to help buyers understand affordability, credit, budgeting, and program eligibility. DSHA maintains a list of HUD-approved counseling agencies operating in Delaware.
- Soft credit pull: A credit check that does NOT affect your FICO score and does NOT appear as an inquiry on your credit report visible to other lenders. The seminar includes a complimentary soft credit pull using mortgage-grade FICO scores from all three bureaus. Opposite of a hard credit pull, which causes a small temporary FICO dip.
- Down payment assistance (DPA): Funds provided by a state housing authority, county, city, or employer to help cover a home buyer’s down payment and/or closing costs. In Delaware, DSHA offers Keys4You (4%), Take5 (5%, Welcome Home only), First State (3%), Diamond in the Rough (5% + FHA 203k Limited, Welcome Home only), and Smart Start (unassisted). DPA can be a grant, a deferred second loan, or a forgivable loan depending on the program.
- LTV (Loan-to-Value ratio): The mortgage loan amount divided by the home’s value or purchase price, expressed as a percentage. A $193,000 loan on a $200,000 home is 96.5% LTV. Lower LTV typically means a smaller down payment requirement is met. LTV affects which loan programs and which mortgage insurance options apply.
- DTI (Debt-to-Income ratio): Your monthly housing payment and other monthly debt obligations divided by your gross monthly income. Lenders typically look at two DTI numbers: the front-end ratio (housing payment only) and the back-end ratio (housing payment plus all other debts). Maximum allowed DTI varies by loan program – FHA generally allows higher ratios than conventional, but all programs have limits.
- PITI: The four components of a typical monthly mortgage payment – Principal, Interest, Taxes, and Insurance. Property taxes and homeowners insurance are usually collected monthly by the lender and held in escrow, then paid on your behalf when due. Some Delaware buyers pay HOA fees and mortgage insurance separately on top of PITI.
- MI (Mortgage Insurance): An insurance premium required by some loan programs that protects the lender if the borrower defaults. FHA loans require an Upfront MIP (financed into the loan) plus a monthly MI premium that typically stays for the life of the loan. Conventional loans with less than 20% down require Private Mortgage Insurance (PMI), which can typically be removed once you reach 20% equity. VA and USDA have their own funding fee structures rather than ongoing MI.
Seminar vs One-on-One Consultation – Which Should You Choose?
The seminar and a one-on-one mortgage consultation are different tools for different stages of the home buying journey. Here is when each makes sense:
| What You Get | Free Seminar (Group) | One-on-One Consultation |
|---|---|---|
| Format | 2-hour virtual webinar with Q&A | 30-minute phone or virtual call |
| Best for | Buyers 3-24 months out who want the full Delaware mortgage landscape | Buyers 0-3 months out who already know they want to apply |
| Cost | Free | Free |
| Coverage | All 14 topics + DSHA programs + soft credit pull + Q&A | Your specific scenario – credit, income, target purchase price, timeline |
| Soft credit pull | Yes – included for every attendee | Available on request when you are ready to pre-qualify |
| Pre-qualification | No – seminar is educational only | Yes – we can issue a pre-approval letter the same day in many cases |
| Sales pressure | None | None |
| Next step after | One-on-one consultation when you are ready | Pre-approval and house shopping |
If you are not sure which fits your timeline, start with the seminar. If you find out during the seminar that you are closer to ready than you thought, we can move you into a one-on-one consultation right after. The two tools are designed to work together, not as substitutes.
Lender Seminar vs DSHA Event vs HUD-Approved Counseling – What is the Difference?
Delaware buyers often hear three different terms used interchangeably – “home buyer seminar,” “DSHA homebuyer event,” and “HUD-approved housing counseling.” They are three different things with three different purposes. Here is how they compare:
| Feature | Lender Seminar (this page) | DSHA Homebuyer Event | HUD-Approved Housing Counseling |
|---|---|---|---|
| Who runs it | John Thomas, NMLS #38783 – Delaware mortgage lender | Delaware State Housing Authority (DSHA) | HUD-certified nonprofit counseling agency on DSHA’s approved list |
| Purpose | Educational overview of Delaware mortgage programs + decision framework + soft credit pull | Awareness of DSHA programs and Delaware homeownership resources | Fulfill HUD/DSHA-required homebuyer education for specific program eligibility |
| Format | Free 2-hour live virtual webinar, monthly | Free events at DSHA-affiliated locations, scheduled by DSHA | Formal counseling sessions through a certified counselor (group or one-on-one) |
| Satisfies DSHA counseling requirement? | No – educational only | Varies by event format; typically no | Yes – issues a HUD-approved counseling certificate |
| Soft credit pull included? | Yes – complimentary, no FICO impact | No | No (counselor may review credit reports you provide) |
| Cost | Free | Free | Usually free; may charge a nominal fee at some agencies |
| Mortgage program depth | FHA, VA, USDA, Conventional, all 7 DSHA programs, Non-QM | DSHA programs only | Varies – depends on the counselor’s scope |
| Best for | Buyers 3-24 months out who want the full Delaware mortgage landscape and a credit baseline | Buyers specifically interested in DSHA programs | Buyers who need an official counseling certificate for DSHA, USDA, or other program eligibility |
Most Delaware buyers benefit from doing all three – the lender seminar gives you the full mortgage landscape, the DSHA event reinforces program-specific details, and HUD-approved counseling provides the formal certificate required for certain programs. They are not redundant; they each cover different ground. Start with the lender seminar to get oriented, then decide whether DSHA event attendance or formal counseling makes sense for your specific program path.
Delaware Mortgage Programs the Seminar Covers
The seminar walks through every Delaware mortgage program available in 2026, with eligibility, dollar amounts, and pairing rules. Each program has its own page on this site if you want to dig deeper after the seminar:
DSHA First Mortgage Programs (post-April 2026 rebrand)
- DSHA Welcome Home – first-time buyers only. Pairs with all DSHA DPA options.
- DSHA Open Door – first-time buyers AND repeat buyers. Higher income limits than Welcome Home. Pairs with First State (3%) and Keys4You (4%).
DSHA Down Payment Assistance Programs
- Keys4You (4% DPA) – pairs with both Welcome Home and Open Door. Only 4%+ DPA available to repeat buyers in Delaware – a meaningful SEO and program moat.
- Take5 (5% DPA) – Welcome Home only (first-time buyers).
- First State (3% DPA) – pairs with both Welcome Home and Open Door.
- Diamond in the Rough (5% DPA + FHA 203k Limited) – Welcome Home only. Combines DPA with renovation financing.
- Smart Start (unassisted) – DSHA first mortgage without DPA. Useful when income limits or down payment situation does not fit the assisted tracks.
Government and Conventional Loan Programs
- Delaware FHA Loans – 3.5% down with 580+ FICO, 580+ for VA-style overlays. 2026 NCC loan limit $630,200; Kent + Sussex $541,287.
- Delaware VA Loans – 0% down for eligible veterans and active-duty military.
- Delaware USDA Rural Housing Loans – 0% down for eligible properties in USDA-designated rural Delaware areas (most of Kent and Sussex counties, plus parts of New Castle).
- Delaware Conventional Loans – 3-5% down with PMI, or 20% down without PMI.
Legacy and Discontinued Programs (Mentioned for Context)
- Delaware Mortgage Credit Certificate (MCC) Program – ended August 15, 2025. The seminar covers what replaced it and how current DSHA programs deliver comparable buyer benefits.
Delaware Transfer Tax and the Builder-Contract Trap
Delaware transfer tax is 4% total of the purchase price – the highest in the region. Under the standard Delaware Association of Realtors (DAR) contract, this is split equally: 2% paid by the buyer, 2% paid by the seller. On a $400,000 home that means the buyer’s transfer tax is $8,000 and the seller’s is $8,000.
Here is where it can get expensive if you are not paying attention: Delaware home builders write their own contracts. Some new construction contracts require the buyer to pay the full 4% transfer tax – $16,000 on that same $400,000 home instead of $8,000. The seminar covers the transfer tax exemption available to qualifying Delaware first-time buyers, and how to read a builder contract before you sign so you know exactly what you are agreeing to.
See also: Delaware First-Time Home Buyer Transfer Tax Exemption for the full breakdown of how to qualify.
Upfront Costs to Budget Before You Find a Home
Closing costs and down payment are the big numbers everyone focuses on, but several smaller costs come up earlier in the process – before you even make an offer. Knowing about these in advance prevents surprises:
- Earnest money deposit (EMD): A good-faith deposit paid when your offer is accepted, typically 1-3% of the purchase price in Delaware (varies by market and seller). EMD is held in escrow by the title company or real estate brokerage and applied to your closing costs at settlement if the deal proceeds.
- Home inspection: Typically $400-$600 for a standard single-family home inspection in Delaware (more for larger homes, additional inspections like radon, termite, or septic). Paid directly to the inspector, usually within 7-10 days of contract acceptance during the inspection period.
- Appraisal fee: Typically $500-$700 for a standard residential appraisal in Delaware. Usually paid upfront by the borrower (sometimes via credit card at order time) and credited at closing if you proceed. Required by the lender to confirm the home’s value supports the loan amount.
- Homeowners insurance quote: No cost to get quotes, but you will need an active policy in place before closing. Annual premiums in Delaware typically range from $800-$1,500 for standard single-family coverage depending on home value, location, and coverage selected.
- Pre-approval credit pull: Free during the seminar (soft pull, no FICO impact). The hard credit pull that happens later when you formally apply for pre-approval is also typically free from the lender, but it does cause a small temporary FICO dip.
The seminar walks through these upfront costs so you can plan the timing and the cash flow before you find the right home. There are fewer surprises once you understand which costs come up at which stage.
Delaware Home Buyer Seminar Help From Newark, DE
John Thomas teaches the Delaware First Time Home Buyer Seminar virtually from the John Thomas Team office at Primary Residential Mortgage in Newark, Delaware. Because the seminar is delivered as a live virtual webinar, Delaware buyers attend from across the entire state – Wilmington, Newark, Middletown, Bear, New Castle, Dover, Smyrna, plus smaller towns and unincorporated areas throughout New Castle County, Kent County, and Sussex County. Maryland buyers in Cecil, Harford, and Baltimore counties attend regularly too, since the underlying loan programs (FHA, VA, USDA, Conventional) work the same way across the state line. The goal is to help every attendee understand mortgage options, DSHA programs, credit, down payment assistance, and the right next step before applying.
Who Should Attend the Delaware Home Buyer Seminar
The seminar is built for buyers who fit any of the following:
- First-time buyers in Delaware who have never been through a mortgage before and want to understand the full picture before they start talking to lenders.
- Repeat buyers who bought their last home a while ago and want to see what has changed in Delaware mortgage programs (especially the April 2026 DSHA rebrand and Open Door + Keys4You pairing for repeat buyers).
- Buyers comparing Delaware to other states – especially Maryland border buyers comparing DSHA against Maryland Mortgage Program or Pennsylvania PHFA.
- Self-employed, 1099, and small business owner buyers who are not sure whether their income will qualify and want to understand bank statement loans and Non-QM options.
- Veterans and active-duty military considering VA loans for a Delaware purchase.
- Realtors, real estate investors, and parents helping adult children buy who want a deeper understanding of how Delaware buyer-side financing actually works in 2026.
Who Helps You Buy a Home in Delaware? Your Home Buying Team
Buying a home is not just you and the lender. There is a team of professionals who each have a specific role in the process, and the seminar walks through who does what:
- Mortgage lender / loan officer: Reviews your income, assets, and credit; structures the loan; issues pre-approval; coordinates with underwriting; and gets you to the closing table. This is the role John Thomas plays. NMLS #38783.
- Buyer’s real estate agent: Represents you (not the seller) in finding homes, writing offers, negotiating terms, and navigating the contract-to-close process. Under the September 2024 NAR rule change, buyers typically sign a buyer agency agreement before touring homes.
- Real estate attorney or settlement/title team: In Delaware, settlement is typically handled by a title company or real estate attorney. They run title search, prepare closing documents, hold escrow funds, and conduct the closing itself.
- Appraiser: An independent licensed professional ordered by the lender (not selected by you or the seller) who determines the home’s market value. The appraisal protects the lender by confirming the loan amount is supported by the property value.
- Home inspector: A licensed professional you hire (separate from the appraiser) to evaluate the physical condition of the home before you finalize the purchase. The inspection report is your tool for negotiating repairs or walking away during the inspection period.
- Homeowners insurance agent: Helps you select and bind a homeowners insurance policy before closing. The lender requires evidence of insurance at settlement.
- HUD-approved housing counselor (when required): If your DSHA program or loan profile requires homebuyer counseling, a HUD-approved counselor at an agency on DSHA’s approved list issues the official counseling certificate. Separate from the lender seminar.
Once you understand who does what, the process feels less overwhelming. The seminar walks through each step so you know who to call, what happens next, and where buyers often get stuck. Note: this list intentionally does not name specific partner Realtors, title companies, or inspectors – per federal RESPA rules, mortgage lenders cannot exchange referrals for compensation, and the lender’s role is to give you the framework so you can choose your team independently.
Buyer Agency Agreements – September 2024 Rule Change
One of the bigger recent changes in Delaware real estate happened on September 16, 2024, when new National Association of Realtors (NAR) settlement rules took effect nationwide. The short version: in most cases, buyers are now asked to sign a buyer agency agreement before a Realtor shows them homes. The seminar covers what this means for you:
- What the agreement does: It establishes that the agent represents you, the buyer (not the seller), defines the scope of services the agent will provide, and clarifies how the agent gets paid for the work.
- How buyer-agent compensation works under the new rules: Before September 2024, buyer-agent commissions were typically advertised in MLS as part of the listing. Under the new rules, buyer-agent compensation is negotiated separately and may be paid by the seller (negotiated into the contract), by the buyer directly, or a combination. The buyer agency agreement spells out the arrangement before you start touring.
- What to read before signing: The scope of services (what the agent will and will not do), the duration of the agreement (how long it stays in effect), the geographic and property-type scope (is it for all homes in Delaware, or just New Castle County, or just one specific home), and the compensation terms (how much, who pays, what happens if the seller does not cover the full amount).
- This is not legal advice: Read the agreement carefully and consult an attorney if you have questions before signing. The seminar gives you the framework to understand what you are signing – your buyer’s agent and (if needed) a real estate attorney can answer specific questions about the agreement language.
This is one of the topics that almost no national mortgage content covers well because the rule change is recent and the buyer-side implications are still being worked out in real Delaware transactions. Bringing it up in the seminar lets you make an informed choice before you sign anything.
When This Seminar Is Not a Good Fit
The seminar is genuinely useful for most buyers – but not all. Here is when you can skip it and take a different path instead:
- You have a fully-ratified purchase contract and need a pre-approval today. Skip the seminar – call John Thomas directly at 302-703-0727 or schedule a one-on-one consultation. The seminar is for buyers 3+ months out; you need direct help now.
- You already attended a HUD-approved Delaware home buyer counseling session in the last 12 months. If DSHA accepts your existing counseling certificate, you may not need this seminar for counseling purposes (the seminar is educational, not HUD-certified counseling). Confirm with your DSHA-approved counselor before assuming a prior certificate satisfies DSHA’s current requirement.
- You only need a refinance, not a purchase. The seminar is purchase-focused. For refinance questions – rate-and-term, FHA Streamline, VA IRRRL, cash-out – call directly for a one-on-one consultation.
- You are buying investment property only. The seminar covers primary-residence financing (which is what 95% of attendees are buying). For investment-only purchases – DSCR loans, fix-and-flip, foreign national investor financing – schedule a one-on-one consultation instead.
- You are buying in a state where I am not licensed. I am licensed in 17 states but operationally serve Delaware and Maryland buyers. If you are buying in a state where I do not lend, the seminar content will not help you with state-specific programs.
- You want a same-day fixed answer to “am I approved.” The seminar is education; pre-approval requires a one-on-one consultation with document review. The free soft credit pull at the seminar gives you your real FICO scores, but a pre-approval letter requires the next step.
If any of these fit your situation, the most efficient next step is a 30-minute one-on-one consultation. Call 302-703-0727, schedule online, or start a mortgage application.
FAQ – Delaware Home Buyer Seminars
Do I need to attend a seminar to get a DSHA loan in Delaware?
DSHA’s homebuyer education requirement is satisfied by a HUD-approved counseling agency, not by attending this seminar. The Delaware First Time Home Buyer Seminar is educational only – it walks you through every program, but it does not by itself fulfill the DSHA counseling certificate requirement. After attending the seminar, you may still need to complete a HUD-approved counseling session through an agency on DSHA’s approved counselor list. The seminar will walk you through how to find a HUD-approved counselor in Delaware and what to expect.
Will attending the seminar hurt my credit score?
No. The complimentary credit pull included with seminar attendance is a soft credit pull, not a hard inquiry. Soft pulls do not affect your FICO score and do not appear as inquiries on your credit report that other lenders can see. This is different from the credit pull you authorize when you actually apply for a mortgage – that is a hard inquiry and typically causes a small temporary FICO dip. The seminar’s soft pull gives you your real mortgage-grade FICO scores from all three bureaus without any credit-score cost.
Can I do the seminar online instead of in person?
Yes – the May 16, 2026 and June 13, 2026 seminars are both 2-hour live virtual webinars delivered over Zoom. You attend from anywhere in Delaware, Maryland, or any state. Future in-person sessions at Delaware venues may return in the future, but the virtual format reaches the most buyers right now and gets you the same content, same Q&A, same complimentary soft credit pull. Register at delawarehomebuyerseminar.com or call 302-703-0727.
What if I attended a home buyer counseling class more than a year ago – does it still count?
DSHA’s homebuyer education requirement specifies the counseling certificate must be current. Most DSHA-approved counseling agencies issue certificates that are valid for 12 months from the date of completion. If your prior counseling is over 12 months old, you may need to re-complete a HUD-approved counseling session. The Delaware First Time Home Buyer Seminar can help you understand what changed in DSHA programs since you last attended counseling (especially the April 2026 program rebrand and the August 2025 MCC sunset), but it does not by itself extend an expired counseling certificate. Confirm current certificate requirements with your DSHA-approved counselor before assuming prior counseling still counts.
Can I bring my spouse, partner, or co-borrower to the seminar?
Yes – and we strongly recommend it. The seminar covers topics that both co-borrowers benefit from hearing the same way: how DSHA income limits count both incomes, how credit scores from both borrowers affect program eligibility, what gift funds can and cannot be used for, and how to negotiate seller-paid closing costs as a couple. There is no extra registration step for additional attendees from the same household – register once and bring whoever is going to be on the loan with you.
Do I need to be a first-time buyer to attend?
No. The seminar is open to anyone considering buying a home in Delaware – first-time buyers, repeat buyers, move-up buyers, downsizers, and parents helping adult children. Repeat buyers especially benefit from the April 2026 DSHA program rebrand coverage – DSHA Open Door is the first-mortgage track that covers both first-time AND repeat buyers, and Keys4You is the only 4%+ down payment assistance program available to Delaware repeat buyers as of May 2026. Most repeat buyers are surprised to learn they qualify for DPA.
I have a bankruptcy from a few years ago – should I attend the seminar or call directly?
Both – in that order. The seminar covers the general bankruptcy waiting period rules across loan types: typically 2 years from Chapter 7 discharge for FHA, 4 years for Conventional, and 2 years for VA, all with re-established credit during the waiting period. Chapter 13 has different rules involving the trustee. Once you have a sense of where you fall on the timeline, schedule a one-on-one consultation to look at your specific credit profile and run scenarios. Many Delaware buyers with prior bankruptcy qualify sooner than they think, especially after the waiting period plus 12-24 months of clean credit re-established. Call 302-703-0727 or schedule online when you are ready for a one-on-one.
Will the seminar give me a pre-approval letter?
No – the seminar is educational, not a pre-approval. The complimentary soft credit pull gives you your real FICO scores so you understand where you stand, and the Q&A at the end lets you ask scenario-specific questions, but a pre-approval letter requires a one-on-one consultation with document review (income, assets, debts, property details). If you finish the seminar and want to move into pre-approval, you can schedule a 30-minute one-on-one consultation directly with John – many seminar attendees do this within a week of attending. The seminar to pre-approval to house shopping path is designed as a single sequence.
How is the seminar different from the videos on YouTube?
The full 2-hour 38-minute seminar recording is available on YouTube on this page – that is great if you just want to absorb the content at your own pace. The live seminar adds three things the recording cannot: (1) the complimentary soft credit pull with your real FICO scores from all three bureaus, (2) live Q&A where you can ask scenario-specific questions and get answers in real time, and (3) the chance to follow up with a one-on-one consultation if your situation needs more than the seminar can cover. Many attendees watch the recording first, then bring specific questions to the live session.
Can Maryland buyers attend the Delaware home buyer seminar?
Yes. The seminar is delivered as a virtual webinar and is open to attendees from any state. Maryland buyers especially benefit because John Thomas is licensed in Maryland (NMLS #38783, MD license active) and serves Maryland buyers operationally. The seminar covers Delaware DSHA programs in depth, but the underlying loan programs – FHA, VA, USDA, Conventional – work the same way in Maryland. The Maryland Mortgage Program (MMP) is not covered in depth at this seminar, but you can ask about it during the Q&A and we can schedule a Maryland-focused one-on-one consultation after the seminar if MMP is the path you want to explore. Cross-border Delaware-Maryland buyers (working in Wilmington/Newark/New Castle County, looking at homes in Cecil/Harford/Baltimore counties) attend regularly.
About John Thomas – Your Seminar Presenter
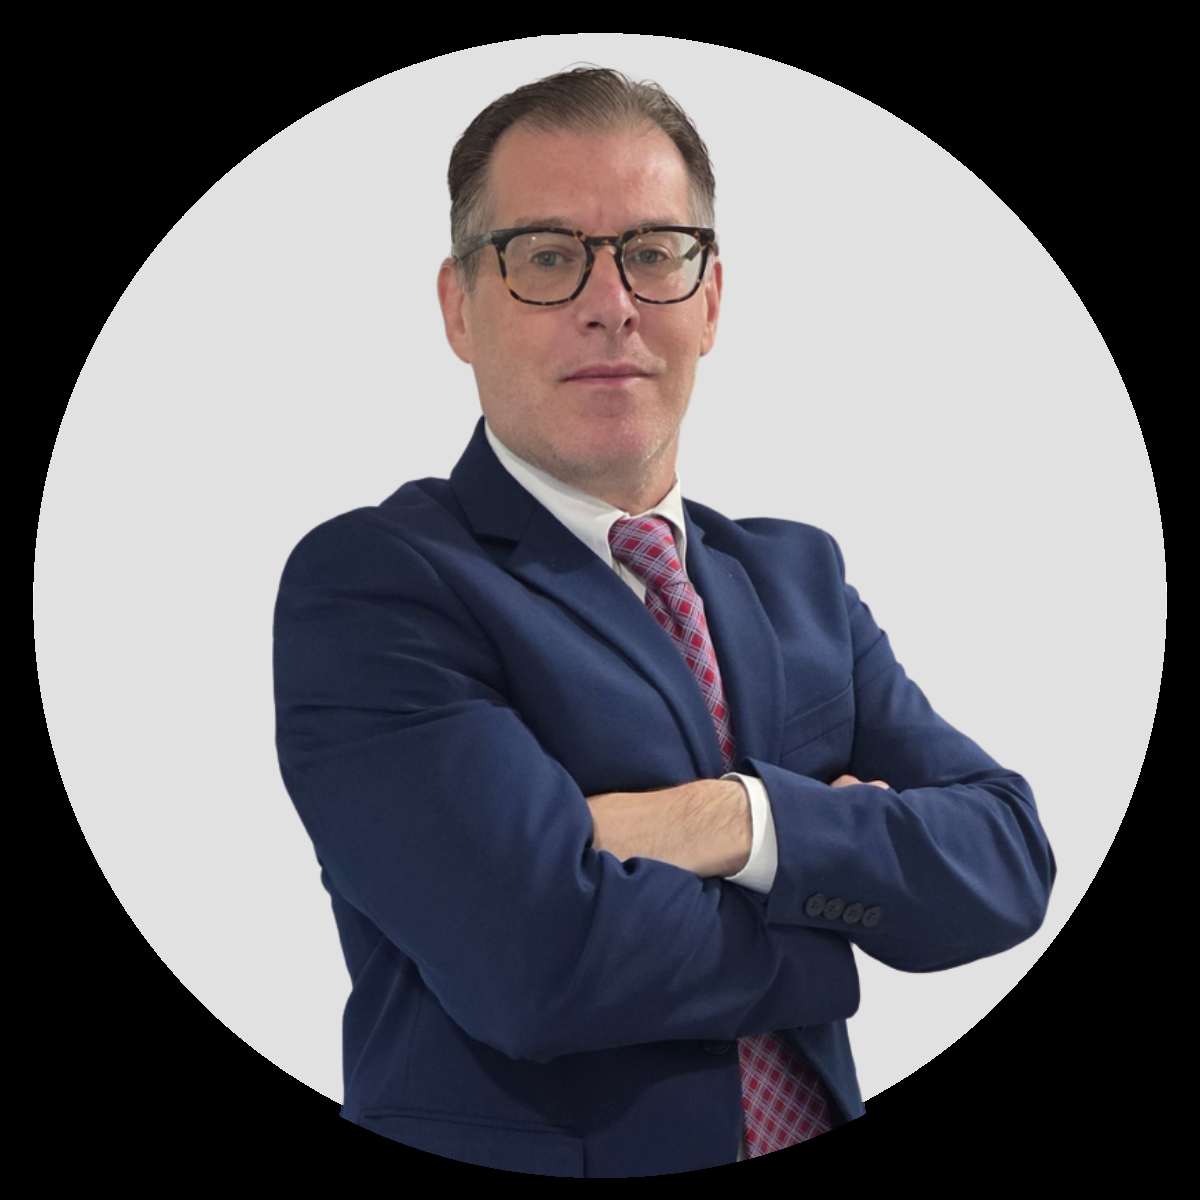
John Thomas is a Delaware mortgage loan officer with over 20 years of experience helping Delaware and Maryland buyers through the home buying process. He is the branch manager at Primary Residential Mortgage, Inc.’s Newark, Delaware office (Branch NMLS #106170), and the author of Your Guide to Buying Your First Home in Delaware. John started teaching the Delaware First Time Home Buyer Seminar in 2005 and has presented 586 sessions to 21,092 Delaware buyers as of May 2026. Before mortgage lending, John taught physics at Delcastle High School for 10+ years – the same teaching habits show up in the seminar.
John holds a Bachelor of Science in Physics Education from the University of Delaware and a Master of Science in Curriculum and Instruction from Delaware State University. He is licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA) under NMLS #38783, with operational service area covering Delaware and Maryland. The Delaware First Time Home Buyer Seminar is the educational anchor of his Delaware practice – the goal is straightforward, and it has been the same for 21 years: send Delaware buyers home with real numbers and real next steps, not sales pressure.
John Thomas Team – Primary Residential Mortgage, Inc.
248 E Chestnut Hill Rd, Newark, DE 19713
Phone: 302-703-0727
Email: JohnThomasTeam@primeres.com
Web: delawaremortgageloans.net
Seminars: delawarehomebuyerseminar.com
NMLS Verification: NMLS Consumer Access – John R. Thomas #38783
Reviews and directions: See John Thomas Team on Google – 4.8 / 5 stars, 285 reviews
Reserve Your Seat at the Next Free Delaware Home Buyer Seminar
Saturday July 18, 2026 – 10:00 AM ET (Virtual Webinar)
Saturday August 15, 2026 – 10:00 AM ET (Virtual Webinar)
Free 2-hour virtual webinar. Complimentary soft credit pull included. No sales pitch, no obligation.
Not Ready to Register? Talk With John Directly
If the seminar is not the right fit for your timeline, call or schedule a one-on-one consultation. Team aims to respond within one business day.
Last Updated: May 2026. Mortgage content reviewed by John R. Thomas, NMLS #38783, DSHA-approved lender at Primary Residential Mortgage, Inc.
John Thomas, NMLS #38783 | Primary Residential Mortgage, Inc. (PRMI NMLS #3094, Newark Branch NMLS #106170) | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
Copyright (c) 2026 John R. Thomas, All Rights Reserved. Equal Housing Lender. Primary Residential Mortgage, Inc. is licensed by the Delaware State Bank Commissioner.
