Dover Delaware First Start Down Payment Assistance Program


Quick Answer: The Dover Delaware First Start Down Payment Assistance Program is a City of Dover grant of up to $20,000 toward settlement costs for first-time buyers buying inside the Dover city limits. It is forgiven in full after ten years, and because the City always takes third lien position, it always stacks with DSHA down payment assistance.
Current as of July 2026. Funding is first-come, first-served and the City’s published balance is nearly exhausted, but the City expects the program to be refunded around September 2026 – call 302-703-0727 and get your file ready now.
Not buying inside the Dover city limits? Start with our Delaware down payment assistance programs guide for the statewide and county options.
| Dover First Start at a Glance | 2026 |
|---|---|
| Maximum assistance | $20,000 of settlement costs |
| Minimum credit score | 620 |
| Buyer’s own funds required | $1,000 (excluding gifts) |
| Asset limit at application | $20,000 in cash or cash equivalents |
| Income limit | 60% to 80% of Kent County AMI by household size |
| Forgiveness period | 10 years of primary residency |
| Lien position | 3rd – always stackable with DSHA assistance |
| Eligible property | Owner-occupied single-family residence inside the Dover city limits – detached, townhouse, condo, or permanently affixed manufactured home. No multi-unit properties. |
| Eligible first mortgage | FHA, VA, or conventional through an approved lender |
| Funding status (July 2026) | Nearly exhausted – City expects refunding around September 2026 |
Dover First Start Eligibility Snapshot
You may be a fit if all of the following are true:
- You have not owned a home in the past 3 years.
- The property is inside the Dover city limits.
- Your credit score is 620 or higher.
- Your household income falls within the City’s 60% to 80% AMI range for your household size.
- You have at least $1,000 of your own cash, excluding gift funds.
- You hold no more than $20,000 in cash or cash-equivalent assets at application.
- You can complete HUD-certified home buyer counseling before closing.
- The home will be your owner-occupied principal residence – a single-family detached home, townhouse, condo, or permanently affixed manufactured home. Multi-unit properties are not eligible.
Eligibility and assistance amounts are determined by the City of Dover. All financing is subject to credit approval and full underwriting review.
I am John Thomas, NMLS #38783, and the John Thomas Team is an approved lender for the City of Dover First Start program. I have spent more than twenty years helping Delaware families buy homes, and Kent County buyers are a large part of that work. First Start is one of the most generous down payment programs in the state for the buyers it fits – up to $20,000, no monthly payments, forgiven in full after ten years – and it is also one of the most misunderstood, because the City rewrote its guidelines and most of what is published online about it is out of date. This page is built from the City of Dover’s current published guidelines and the FY2026 HUD income limits the City itself posts. If you want to know whether you qualify and whether there is money left, call me at 302-703-0727.
See If You Qualify for Dover First Start
We check three things first: your household income, your credit score, and whether the property sits inside the Dover city limits. Then we compare Dover First Start against DSHA, FHA, VA, and conventional options so you can see what is actually available – subject to full underwriting review.
You do not apply to the City first. Start with an approved lender, complete HUD-certified counseling, get a Dover property under contract, and then the lender submits the funding request to the City.
Table of Contents
What Is the Dover Delaware First Start Down Payment Assistance Program?
The Dover First Start Homeownership Downpayment and Settlement Assistance Program is a municipal down payment program run by the City of Dover’s Community Development Office and funded with federal Community Development Block Grant (CDBG) dollars. Its purpose is to help low- and moderate-income families cover down payment and settlement costs on eligible properties inside the Dover city limits.
It is a city program, not a state program. That distinction matters more than most buyers realize. The Delaware State Housing Authority (DSHA) programs are available statewide and are funded through DSHA bond proceeds. First Start money comes out of the City of Dover’s annual CDBG allocation, which means the pool is small, it is spent on a first-come basis, and it can run dry mid-year. If you are buying anywhere else in Delaware, this program does not apply to you – see our Delaware down payment assistance programs guide for the statewide and county options instead.
How Much Money Can You Get from Dover First Start?
The City’s published guidelines set the ceiling at up to $20,000 of settlement costs, with one restriction that trips people up: no more than 50% of the lender’s required down payment can be covered by the grant. In plain terms, First Start is built primarily to attack your closing costs, and it will only carry part of your down payment – you and your first mortgage program still have to cover the rest.
Assistance amounts are also based on demonstrated need and on how much CDBG money the City has left, so $20,000 is a maximum, not an entitlement. Two buyers with identical loan amounts can receive different amounts. The only way to know your number is to have an approved lender run your file and submit it to the City.
| Program feature | City of Dover First Start |
|---|---|
| Maximum assistance | Up to $20,000 of settlement costs |
| Down payment restriction | No more than 50% of the lender’s required down payment |
| Structure | Grant secured by a second mortgage lien on the property |
| Monthly payment | None |
| Forgiveness | Fully forgiven after 10 years of primary residency |
| Early payoff trigger | Sale, transfer, or the home ceasing to be your principal residence within 10 years |
| Minimum credit score | 620 |
| Minimum buyer contribution | $1,000 of your own cash, excluding gift money |
| Asset cap | No more than $20,000 in cash or cash-equivalent assets at application |
| Property location | Inside the City of Dover limits only |
| Funding | First-come, first-served; wait list when funds run out |
Is Dover First Start Funded Right Now?
This is the question nobody else answers, and it is the one that decides whether the program is useful to you this year. The City of Dover posts a running balance of available program money on its Community Development Office page.
Funding status – as of July 7, 2026: the City of Dover reported $4,769.57 remaining in the Down Payment and Settlement Assistance Program. That is a fraction of one full $20,000 award.
The City’s guidelines state that grant funding is awarded first-come, first-served, and that when funds run out qualified buyers are placed on a wait list for the next round of CDBG funding.
The good news: the City’s Community Development Office told us in July 2026 that it expects the program to be refunded sometime in September. Timing is the City’s call and is not guaranteed, but that is a real target to plan around – and the buyers who are already counseled, pre-approved, and under contract when the money lands are the ones who get it. Balances and timing change; the City’s Community Development Office page is the live source.
My honest read for buyers right now: if you are shopping this summer, do not write an offer that depends on First Start dollars that have not been reserved – line up a program that is funded today, most often DSHA Welcome Home with one of its down payment assistance options. But if a September refunding is the plan, then the smart move is to get everything else done now: finish your eight hours of HUD counseling, get fully pre-approved, and know which addresses sit inside the city limits. When the money reloads it goes first-come, first-served, and the buyers who did the paperwork in July are ahead of the buyers who start in September.
What happens if the money runs out after you are under contract? Because the City does not reserve funding until a buyer is mortgage-approved, an unreserved award is not a guarantee – and the guidelines put qualified buyers on a wait list for the next CDBG round when funds are exhausted. That is precisely why I do not let a Dover buyer write an offer that depends on First Start dollars that have not been reserved. We structure the file so it closes with or without the City’s money, and the assistance is upside rather than a load-bearing wall.
How Do You Qualify for the Dover First Start Program?
These are the qualifications exactly as the City of Dover publishes them in its current program guidelines. Several of them changed from the older version of this program that is still being repeated on other websites.
- First-time home buyer. Defined by the City as someone who has not owned a home within the past three years.
- At least $1,000 of your own cash, excluding gift money. Gift funds can still help elsewhere in your file – see our gift funds guidelines – but they do not satisfy this $1,000.
- The home must be your principal residence and must be located inside the City of Dover limits.
- Home ownership counseling with a certified HUD counselor, completed prior to closing. Plan on eight hours. You can locate an approved agency through HUD’s Delaware housing counseling resources. The City also states that funding will not be reserved until the buyer has been approved for a mortgage.
- The first mortgage must be held by a lender approved by the program. Primary Residential Mortgage is an approved lender.
- 620 minimum credit score. If you are not there yet, our five factors of credit scoring breakdown is where I would start.
- Home inspection on all existing properties, with any major defects repaired before closing. The inspection must be completed by an independent home inspector licensed by the City of Dover. New construction must carry a one-year HUD-approved warranty.
- Visual lead-based paint assessment on any home built before 1978.
- Household income within the City’s 60% to 80% area median income range for your household size, as defined by HUD. Note that this counts the household, not only the borrowers on the loan.
- No more than $20,000 in cash or cash-equivalent assets at the time of application. This is a real disqualifier and it is not published anywhere else I have seen.
What if the inspection turns up repairs? The City’s rule is that major defects identified in the inspection must be repaired before closing. In practice that means a repair negotiation with the seller, a re-inspection, and time – which is why I tell Dover buyers to build extra days into the contract rather than fight for a fast close. Buying new construction? There is no existing-home inspection requirement, but the builder must provide a one-year HUD-approved warranty, and the builder’s contract is where the transfer tax trap lives (see below).
One rule that has not changed, and that catches buyers at the settlement table: you cannot receive cash back at settlement. If your Closing Disclosure shows money coming back to you – even your own deposit money – the City reduces its contribution by that amount and the extra funds go back to Dover.
Dover City Limits, Not a Dover Mailing Address
This deserves its own section because it is the single most common way a Dover First Start file dies before it starts. The property must sit inside the incorporated City of Dover limits. A Dover, DE mailing address is not the same thing, and neither is a Dover ZIP code.
City limits – not ZIP code, not mailing address, not school district.
Plenty of homes that say “Dover, DE 19901” or “Dover, DE 19904” on the envelope actually sit in unincorporated Kent County, outside the city boundary. Those homes are not eligible for First Start, no matter how close they are. The same goes for nearby communities – Camden, Wyoming, Magnolia, Smyrna, and much of the area around Dover Air Force Base fall outside the City of Dover limits. We verify the address against the city boundary before an offer is written, and the City confirms it again when the funding application is submitted. You can also check a parcel yourself on the City of Dover’s GIS mapping portal – but do not rely on a neighborhood name or a listing description, because the boundary runs at the parcel level and it is not intuitive.
If the home you love turns out to be outside the line, you are not out of options – it just means the municipal money is off the table and statewide DSHA down payment assistance becomes the path. Ask us to check the address first. It takes a minute and it saves weeks.
What Are the 2026 Dover First Start Income Limits?
The City of Dover uses the HUD income limits for Kent County, by household size. The table below is the City’s own published FY2026 schedule, effective June 1, 2026. The City’s guidelines state that income must fall between 60% and 80% of area median income to be eligible for assistance, so both columns matter – which tier applies to your file is confirmed by the City when your funding application is submitted.
| Household size | 60% of median | 80% of median |
|---|---|---|
| 1 person | $45,240 | $60,350 |
| 2 people | $51,720 | $69,000 |
| 3 people | $58,200 | $77,600 |
| 4 people | $64,680 | $86,200 |
| 5 people | $69,840 | $93,100 |
| 6 people | $75,000 | $100,000 |
| 7 people | $80,220 | $106,900 |
| 8 people | $85,380 | $113,800 |
One wrinkle worth naming: the City’s separate Downtown Homeownership Incentives sheet describes First Start eligibility more simply, as household income of 80% of area median income or less, while the program guidelines use the 60% to 80% range. The City’s Community Development Office is the arbiter of which tier applies to your file, and we confirm it with them before funding is requested.
Two things to be careful about here. First, this is household income based on the number of people residing in the home, not just the people signing the note (a distinction that catches self-employed Delaware buyers especially, since their qualifying income and their household income are often two different numbers) – that is different from the DSHA rule, where Welcome Home counts only the income of borrowers on the note and mortgage. Buyers who qualify comfortably for DSHA sometimes do not qualify for First Start for exactly this reason. Second, these limits are refreshed by HUD annually, so a figure you found on a blog last year is probably wrong.
What Property Types Qualify for Dover First Start?
The City’s published guidelines say “eligible properties” without listing them, which is why nobody else answers this. We asked the City of Dover’s Community Development Office directly. Here is the list, straight from them. The program is built for owner-occupied single-family residences, and the City has confirmed that as a matter of program policy it does not assist multi-unit properties.
| Property type | Eligible for Dover First Start? |
|---|---|
| Single-family detached home | Yes – owner-occupied |
| Townhouse | Yes – the single unit the buyer will occupy |
| Condominium unit | Yes – the single unit the buyer will occupy |
| Manufactured home | Yes – if permanently affixed and treated as real property |
| Duplex or any multi-unit property | No – the City does not assist multi-unit properties as a matter of program policy |
| Investment property / second home | No – owner-occupied principal residence only |
Two things worth pulling out of that list. First, the multi-unit exclusion, because it catches people. An FHA loan will finance a two-to-four unit property that you live in, and buyers reasonably assume the City’s assistance follows the same rule. It does not. The City’s stated reasoning is that its CDBG funding is limited, and keeping the program focused on owner-occupied single-family homeownership stretches those dollars further while avoiding the extra underwriting and administrative complexity that multi-unit deals carry. If a duplex is your plan, the FHA loan still works – the City’s $20,000 does not come with it.
Second, manufactured homes are eligible when they are permanently affixed and titled as real property, not as personal property (chattel) – the same real-property test that governs Delaware manufactured home financing generally. If the home is still titled as a vehicle, the conversion has to happen before any of this works. Worth knowing in Kent County, where manufactured housing is a real part of the entry-level market.
What Are the Grant Terms and Forgiveness Rules?
The City records a mortgage lien on the property for the assistance amount, and it always takes third lien position – behind your first mortgage and behind any DSHA down payment assistance second. There are no monthly payments and no interest accrual on the assistance under the City’s program documents. The obligation is fully forgiven after ten years, provided the home remains your principal residence for that period.
If the home is sold, transferred, or stops being your principal residence within those first ten years, the City’s current guidelines state that a percentage of the grant becomes due and payable – not, as the older program language was often described, the entire amount. That is a meaningful improvement for buyers, and it is the single most commonly misreported fact about this program online, including on national sites.
Refinancing is a separate question. Because the City holds a recorded second lien, a refinance generally requires the City to agree to keep that lien in second position (a subordination) or to be paid off. Do not assume either outcome – confirm it with the City and your lender before you start a refinance.
How the Dover First Start Application Actually Works
Buyers usually come to me thinking they apply to the City first. That is not how this program runs. In my experience originating Dover First Start files, the sequence looks like this, and the order is what keeps a file alive:

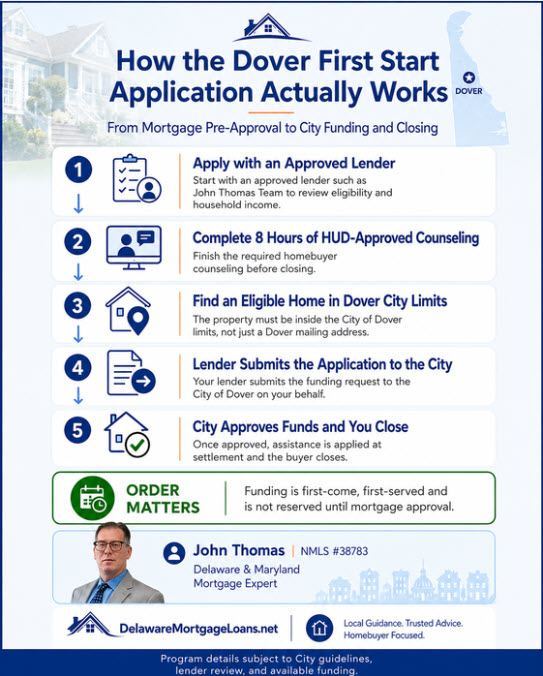
- Apply with an approved lender. You start with a lender approved for the program, like the John Thomas Team. We confirm eligibility first, using household income against the City’s limits for your household size.
- Complete eight hours of home buyer counseling. This has to be done with a certified HUD counselor. Our free Dover Delaware first time home buyer seminar is where a lot of Kent County buyers get started on this step.
- Find a property inside the Dover city limits and get it under contract. City limits, not a Dover mailing address – those are not the same thing, and I check the address before anyone writes an offer.
- The lender submits the funding application to the City of Dover. We send it in for approval of funds on your behalf. You are not filing this yourself.
- The City approves the funds and we go to closing. The assistance is applied at settlement, and you sign the City’s note and second mortgage.
Here is why the order matters so much on this particular program. The City’s guidelines say funding is not reserved until the buyer has been approved for a mortgage, and that money is awarded first-come, first-served. Put those two rules together and a buyer who waits to get pre-approved is standing behind every buyer who did not. In a year like this one, where the published balance is under $5,000, being early in that line is most of the game.
Which First Mortgage Loans Work with Dover First Start?
First Start is a second lien. It sits behind a normal first mortgage, and that first mortgage needs to come from a lender approved by the program. The first mortgage options Dover buyers typically use are:
- FHA loans – 3.5% down with a 580 score, though First Start itself requires 620. The most common pairing for Dover first-time buyers.
- VA loans – no down payment for eligible service members and veterans. With Dover Air Force Base in the area, this is a real path for a lot of Kent County buyers, and it changes the math on how much assistance you need.
- Conventional loans – as little as 3% down for eligible first-time buyers, with mortgage insurance that can be removed later.
Which one is right depends on your credit, your debt-to-income ratio, and the property. If you are a veteran, a VA first mortgage with no down payment often produces a better result than stacking assistance onto an FHA loan, because the 50%-of-down-payment restriction on First Start means the grant cannot do as much for your down payment as buyers expect.
Can You Combine Dover First Start with DSHA Assistance?
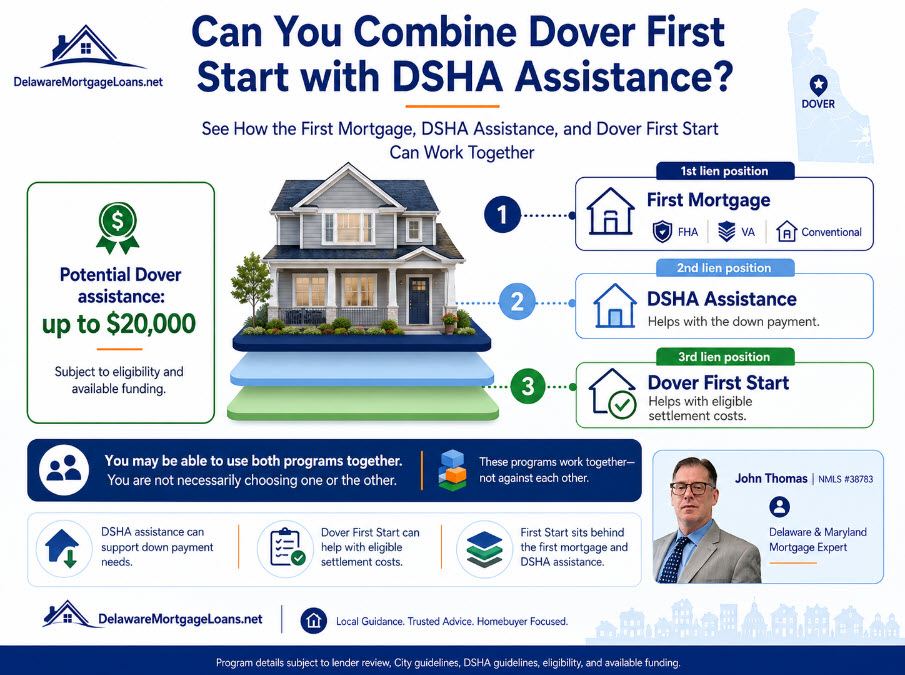
Yes – and this is the part most Dover buyers never hear. The City of Dover always records its assistance in third lien position, behind your first mortgage and behind the DSHA down payment assistance second mortgage. Because it goes into third position by design, First Start can always be stacked with DSHA down payment assistance. You are not choosing between the two programs. You can use both.
That is a meaningful amount of help layered on one purchase: a DSHA down payment assistance second of 3%, 4%, or 5% of your loan amount, plus up to $20,000 from the City of Dover in third position. It also resolves the 50%-of-down-payment restriction neatly – DSHA assistance carries the down payment, and First Start goes to work on your settlement costs, which is exactly what the City designed it to cover. The City of Wilmington’s First Start program works the same way: it also records in third position and stacks with DSHA assistance for Wilmington buyers.

The DSHA tracks a Dover buyer would normally be looking at:
- Welcome Home – the first mortgage for first-time buyers, and the track most First Start buyers also fit.
- Open Door – the first mortgage for repeat buyers and higher-income households. Note that if you qualify for Open Door as a repeat buyer, you do not qualify for First Start, which is first-time-buyer only.
- First State (3% DPA), Keys4You (4% DPA), Take5 (5% DPA, Welcome Home only), and Diamond in the Rough (5% plus FHA 203k renovation financing) – the down payment assistance options that ride on top of those first mortgages.
| Example: $300,000 Dover purchase | Assistance | Lien position |
|---|---|---|
| First mortgage (FHA, VA, or conventional) | – | 1st |
| DSHA Keys4You down payment assistance at 4% of the loan amount | About $12,000 | 2nd |
| City of Dover First Start settlement-cost assistance | Up to $20,000 | 3rd |
| Total assistance reviewed | Up to about $32,000 |
The practical point: DSHA assistance is a percentage of your loan amount and it is funded statewide, while First Start is a flat dollar amount funded out of one city’s grant pool. When First Start money is available, the combination can be powerful. When it is not, DSHA is the program that still closes your loan.
Dover First Start vs. Wilmington First Start vs. DSHA
There are two completely different Delaware programs called “First Start,” and national websites confuse them constantly. Bankrate, for one, has published Wilmington’s terms under a Delaware first-time-buyer heading. If you are buying in Dover, the Wilmington rules do not apply to you, and vice versa.
| Dover First Start | Wilmington First Start | DSHA DPA (statewide) | |
|---|---|---|---|
| Who runs it | City of Dover (CDBG) | City of Wilmington | Delaware State Housing Authority |
| Where you must buy | Inside Dover city limits | Inside Wilmington city limits | Anywhere in Delaware |
| Amount | Up to $20,000 | Lesser of $15,000 or 6% of price | 3%, 4% or 5% of the loan amount |
| Structure | Forgivable, 10 years | Forgivable, 10 years | Deferred 0% second mortgage |
| Income counted | Full household | Household, per City rules | Borrowers on the note (Welcome Home) |
| Min credit score | 620 | Per City rules | 620 |
| Stacks with DSHA DPA | Yes – always records in 3rd lien position | Yes – always records in 3rd lien position | N/A – this is the 2nd lien |
| Funding risk | High – small annual CDBG pool | Moderate | Lower – statewide funding |
If you are buying in New Castle County rather than Kent, the closest equivalent municipal-style program is the New Castle County DPS program, which has its own income rules and its own quirks.
Delaware Transfer Tax and Your Dover Closing Costs
Delaware charges a 4% realty transfer tax. Under a standard Delaware Association of Realtors contract, that splits evenly – 2% paid by the buyer and 2% paid by the seller. On a $300,000 Dover home, the buyer’s half is $6,000, and it is usually the largest single line in a first-time buyer’s closing costs. That is exactly the cost First Start is designed to attack.
There is a second lever on that same line: eligible Delaware first-time buyers may claim a Delaware first-time home buyer state transfer tax exemption, which reduces the buyer’s share of the state portion. Stack that with First Start assistance and a seller credit and the cash you actually bring to settlement can look very different from the number you first calculated.
Builder contract warning. Home builders write their own contracts, and some require the buyer to pay the full 4% transfer tax rather than the standard 2%. On a $300,000 new construction home in Dover, that is a $12,000 transfer tax instead of $6,000 – a $6,000 swing that lands directly on the cash you need at settlement. Always confirm who pays transfer tax before you sign any builder contract.
Seller-paid closing cost credits are the other lever, and they are negotiated into the purchase contract rather than applied for. Between assistance and seller credits, many Dover buyers close with far less cash than the sticker price of the closing costs suggests – see understanding seller-paid closing costs for how that works.
Two More City of Dover Incentives Most Buyers Never Hear About
First Start is not the only thing the City of Dover offers a home buyer. The City publishes a separate Downtown Homeownership Incentives sheet, and two of those incentives can matter as much as the grant money – one of them applies citywide, not just downtown.
1. City of Dover first-time home buyer transfer tax exemption (citywide)
The City exempts first-time home buyers from the transfer tax anywhere inside the Dover city limits, provided the home is used as the buyer’s principal residence. This was adopted February 24, 2025 and is set out in the Dover Code, Chapter 102 (Taxation), Article III (Realty Transfer Tax). The City reserves the right to deny the exemption where a sale appears structured to abuse it.
Careful – the City uses a stricter first-time buyer definition here than First Start does.
For this exemption, the City defines a first-time home buyer as someone who has never held an interest in residential real estate used as their principal residence, anywhere, and who intends to occupy the Dover property within 90 days of the deed being recorded. That is not the same as the First Start rule, which only requires that you have not owned a home in the past three years. It is entirely possible to qualify for First Start assistance and not qualify for this transfer tax exemption. Have both tested before you budget your cash to close.
This City exemption is separate from the state-level break covered on our Delaware first-time home buyer state transfer tax exemption page. They are different programs from different levels of government, and a Dover buyer may be looking at both.
2. Downtown Development District real estate tax abatement (DDD only)
If the home you buy sits inside Dover’s Downtown Development District and you live in it, the City phases in your City real estate taxes over five years rather than charging them in full from day one:
| Year of owner occupancy | Reduction of City real estate taxes |
|---|---|
| 1st year | 100% reduction |
| 2nd year | 75% reduction |
| 3rd year | 50% reduction |
| 4th year | 25% reduction |
| 5th year | 0% – full City taxes resume |
The abatement is not automatic. The homeowner applies by letter to the City Manager, who responds within 30 days, and the request goes to City Council after the certificate of occupancy is issued. After that, a statement of compliance is due to the City Manager by April 15 each year – miss it and the abatement can be lost. Inside the DDD there is also a seller-side sweetener: a seller who sells to a first-time home buyer may be exempt from their portion of the transfer tax, which is a real negotiating chip when you write the offer.
Both incentives are administered by the City’s Department of Planning and Inspections at 15 Loockerman Plaza, Dover, and neither is handled by your lender – but I flag them for every Dover buyer, because stacking a forgivable grant, a transfer tax exemption, and a four-year tax phase-in changes what a house actually costs to own.
When Dover First Start Is Not a Good Fit
I would rather tell you this up front than have you spend two months chasing a program that was never going to work for you.
- You are buying outside the Dover city limits. A Dover mailing address in unincorporated Kent County does not qualify. Statewide DSHA assistance is the path instead.
- You have significant savings. The $20,000 cash and cash-equivalent asset cap at application means buyers with healthy reserves are generally screened out, even when their income fits.
- Your household income runs above the 80% AMI column for your household size – and remember this counts everyone in the household, not just the borrowers.
- You are a repeat buyer. First Start requires that you have not owned a home in the past three years. DSHA Open Door is built for repeat buyers.
- You are buying a duplex or any multi-unit property. The City assists owner-occupied single-family residences only, and does not fund multi-unit purchases as a matter of program policy – even if you will live in one of the units.
- You are on a tight closing timeline. Between HUD counseling, a City-licensed inspection, required repairs, and the City’s funding approval, this program adds steps. If you need to close in three weeks, it is likely the wrong tool.
- Your credit is below 620. There is no exception in the guidelines. If you are close, we can usually work on it – and a FHA loan at 580 may still put you in a home while you build toward assistance eligibility on a future purchase. Rebuilding after a bankruptcy? Our Delaware mortgage after bankruptcy guide covers the waiting periods.
What Changed on the Dover First Start Program in 2026?
The City of Dover revised its published guidelines, and most of the material online – including, until today, parts of this page – still reflects the older rules. Here is what is actually different.
| Rule | Older, widely republished version | Current City of Dover guidelines |
|---|---|---|
| Early sale within 10 years | Full amount of the loan repaid | A percentage of the grant becomes due |
| Home inspection | ASHI inspector | Independent inspector licensed by the City of Dover |
| Counseling timing | Before signing a contract or applying | Prior to closing; funding is not reserved until mortgage approval |
| Assets | No asset test mentioned | No more than $20,000 in cash or cash equivalents at application |
| What the money covers | Down payment and closing costs, broadly | Settlement costs, with no more than 50% of the required down payment |
| Income standard | At or below 80% AMI | Between 60% and 80% AMI by household size |
| Single-parent exception | Listed | Not in the current guidelines |
Official program sources
- City of Dover Community Development Office – current available funding balance and program documents
- Dover First Start program guidelines (PDF) – qualifications and grant terms
- FY2026 HUD income limits, Kent County (PDF) – effective June 1, 2026
- HUD Delaware housing counseling resources – find a HUD-certified counselor
- City of Dover Community Development Office: (302) 736-7175
Last verified against City of Dover published sources: July 13, 2026. Eligible property types (owner-occupied single-family only; no multi-unit) and the expected September 2026 refunding were confirmed directly with the City’s Community Development Office in July 2026.
FAQ – Dover First Start Down Payment Assistance Program
What is the Dover First Start Down Payment Assistance Program?
It is a City of Dover program, funded with federal Community Development Block Grant money, that helps eligible first-time buyers cover down payment and settlement costs on a home inside the Dover city limits. Assistance runs up to $20,000, is secured by a second mortgage lien, carries no monthly payments, and is fully forgiven after ten years of primary residency. It is administered by the City’s Community Development Office and is separate from the statewide DSHA programs.
How much money can you actually get from Dover First Start?
Up to $20,000 of settlement costs. The City’s guidelines add an important restriction: no more than 50% of the lender’s required down payment can be covered by the grant. Awards are also based on demonstrated need and on how much CDBG funding the City has remaining, so $20,000 is a ceiling rather than a standard award. Your actual figure is determined when your approved lender submits the funding application to the City.
Does the Dover First Start program have money available right now?
Not much, but more is coming. Funding is awarded first-come, first-served, and the City publishes its running balance: as of July 7, 2026, the City of Dover reported $4,769.57 remaining in the Down Payment and Settlement Assistance Program, which is a fraction of a single full award. The City’s Community Development Office told us in July 2026 that it expects the program to be refunded sometime in September, though the timing is the City’s call and is not guaranteed. The practical takeaway is to get your HUD counseling done and your pre-approval finished now, so that when the money reloads you are at the front of a first-come line rather than the back of it. Call 302-703-0727 and we will check current availability with the City.
What are the 2026 income limits for the Dover First Start program?
The City uses HUD’s Kent County limits by household size, effective June 1, 2026. The 80% of median figures run from $60,350 for a 1-person household to $86,200 for a 4-person household and $113,800 for an 8-person household. The City’s guidelines state that income must fall between 60% and 80% of area median income to be eligible, so the 60% column matters too. Critically, this counts total household income for everyone residing in the home – not only the borrowers on the loan, which is how DSHA Welcome Home counts income.
Do you have to pay the Dover First Start assistance back?
Not if you stay. The assistance is fully forgiven after ten years of using the home as your principal residence. If the home is sold, transferred, or stops being your principal residence within those first ten years, the City’s current guidelines state that a percentage of the grant becomes due and payable. Older descriptions of this program – still repeated on national websites – say the full amount comes due, which does not match the City’s current published guidelines.
I have $30,000 in savings. Can I still qualify for Dover First Start?
Most likely not, based on the current guidelines. The City states that a buyer cannot have more than $20,000 in cash or cash-equivalent assets at the time of application. This is a newer rule and it is not published on most other sites. Buyers with larger reserves are typically better served by a conventional or FHA loan without municipal assistance, or by DSHA assistance, which does not apply the same asset cap. Ask us to run both scenarios before you assume you are out.
Can I use Dover First Start with a VA loan if I am stationed at Dover Air Force Base?
Yes. Dover First Start sits behind whatever first mortgage you use, and VA is one of the eligible first-mortgage types along with FHA and conventional. For an eligible service member or veteran, a VA loan with no down payment often pairs better with First Start than an FHA loan does, because the City’s rule that no more than 50% of the lender’s required down payment can be covered stops mattering when the down payment is zero – the grant goes entirely to settlement costs. One caution specific to Dover Air Force Base: the base and much of the surrounding area sit outside the incorporated City of Dover limits, and the property has to be inside the city limits to qualify. We check the address before you write an offer.
Can I use seller-paid closing cost credits along with Dover First Start?
Yes, and it is often smart to – but watch the cash-back rule. The City does not allow you to receive cash back at settlement, and if the Closing Disclosure shows money coming back to you, the City reduces its contribution by that amount and the excess returns to Dover. That can happen when a generous seller credit and City assistance are both applied to the same closing costs. The fix is sequencing: we structure the seller credit and the City’s funds so that neither is wasted and nothing bounces back to you as cash. It is worth having your lender model this before the offer is finalized.
Can Dover First Start be combined with DSHA down payment assistance?
Yes. The City of Dover always records its First Start assistance in third lien position, behind your first mortgage and behind the DSHA down payment assistance second mortgage, so First Start can always be stacked with DSHA DPA. A Dover buyer can use a DSHA down payment assistance second of 3%, 4%, or 5% of the loan amount and layer up to $20,000 of City of Dover assistance behind it, subject to eligibility for each program and to available City funding. The City of Wilmington First Start program works the same way for Wilmington buyers.
Is a Dover mailing address the same as being inside the Dover city limits?
No, and this is one of the most common ways a First Start file dies. Many homes with a Dover, DE mailing address sit in unincorporated Kent County and are outside the City of Dover limits, which makes them ineligible for this program. We check the address against the city boundary before an offer is written. If the home falls outside the limits, statewide DSHA assistance is usually the right path instead.
About the Author – John R. Thomas, NMLS #38783
John Thomas is a branch manager and mortgage loan officer with Primary Residential Mortgage, Inc. in Newark, Delaware, and has helped Delaware families buy homes for more than twenty years. He holds a BS in Physics Education from the University of Delaware and an MS in Curriculum and Instruction from Delaware State University, and he is the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826). He hosts free monthly first-time home buyer seminars in Newark, Wilmington, and Dover.
On Dover First Start files specifically, John’s team is an approved lender and submits the funding application to the City on the buyer’s behalf – which is why he pushes Kent County buyers to complete their HUD counseling and get fully pre-approved early: the City does not reserve funding until a buyer is mortgage-approved, and awards are made first-come, first-served out of a small annual grant pool.
Licensed in 17 states as a credential (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA). Delaware and Maryland are the primary service areas.
John Thomas Team | Primary Residential Mortgage, Inc.
248 E Chestnut Hill Rd, Newark, DE 19713
Phone: 302-703-0727 | Email: team@johnthomasteam.com
See John Thomas Team on Google
Serving Dover and Kent County Buyers
The John Thomas Team is based in Newark, Delaware, and works with buyers across Dover, Kent County, Dover Air Force Base, Camden, Wyoming, Magnolia, and Smyrna who need help comparing City of Dover First Start, DSHA, FHA, VA, and conventional financing. One boundary to keep straight: for First Start specifically, the property must sit inside the incorporated City of Dover limits – the surrounding towns are served by DSHA and the other statewide programs instead.
Buying a Home in Dover? Let’s Find the Program That Is Actually Funded.
We will check your household income against the City’s limits, confirm whether First Start money is available, and compare it against DSHA assistance and FHA, VA, and conventional financing – subject to full underwriting review. No pressure, no obligation.
Buying elsewhere in Kent County? Start with our Dover Delaware mortgage loans guide. New to the process entirely? The Delaware first time home buyers guide covers every step from pre-approval to closing.
Last Updated: July 2026 | Mortgage content reviewed by John R. Thomas, NMLS #38783.
John Thomas Team | Primary Residential Mortgage, Inc. | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com
(c) 2026 John R. Thomas. All rights reserved. Program terms, income limits, and funding availability are set by the City of Dover and are subject to change. This page is informational and is not a commitment to lend. All loans subject to credit approval and full underwriting review. Equal Housing Lender.
