
DSHA Loan Programs in Delaware: Down Payment Assistance Explained (2026)

Delaware Mortgage Program (DSHA) Overview: DSHA’s Delaware Mortgage Program offers affordable 30-year fixed-rate mortgage loans – Welcome Home (first-time buyers) and Open Door (all buyers) – paired with down payment assistance of 3%-5% through the First State Home Loan (3%), Keys4You (4%), Take5 (5% – Welcome Home only), and Diamond in the Rough (5% – Welcome Home only) programs. Available statewide across New Castle, Kent, and Sussex Counties. Minimum credit score: 620. DSHA increased its income and sales price limits effective for new reservations received on or after June 8, 2026 (see the updated figures below). Contact John Thomas, NMLS #38783, DSHA Approved Lender, at 302-703-0727. Current as of June 2026.
I’ve been helping Delaware homebuyers navigate DSHA programs for over 20 years, and I’ll tell you this upfront: the biggest problem buyers run into is finding outdated information online. National websites still reference old programs like the SMAL loan or “Preferred Plus” – programs that no longer exist in the same form. On this page, I’m going to walk you through the current, active DSHA loan programs in Delaware as of 2026, including income limits, down payment assistance amounts, and how each program actually works. Whether you’re searching for a DSHA loan in Delaware, a Delaware DSHA mortgage, or just trying to understand what Delaware first-time homebuyer programs are available right now – by the time you’re done reading, you’ll know exactly where you stand.
Find Out Which DSHA Program You Qualify For
We’re a DSHA-approved lender. Call or schedule a free consultation and we’ll review your income, credit, county, and purchase goal – then tell you exactly which program fits, how much assistance you qualify for, and what you’ll need to bring to closing. No pressure, no obligation.
Table of Contents
What Is DSHA and How Do These Loan Programs Work?
DSHA loan Delaware quick answer: A DSHA loan in Delaware is a state-backed 30-year fixed-rate mortgage offered through DSHA’s Delaware Mortgage Program at destatehousing.com (launched in DSHA’s April 2026 rebrand that retired the longtime “Kiss Your Landlord Goodbye” branding). It provides below-market interest rates and pairs with down payment assistance through First State Home Loan (3%), Keys4You (4%), Take5 (5% – Welcome Home only), and Diamond in the Rough (5% – Welcome Home only). The two main programs are Welcome Home (first-time buyers) and Open Door (all buyers). Minimum credit score is 620.
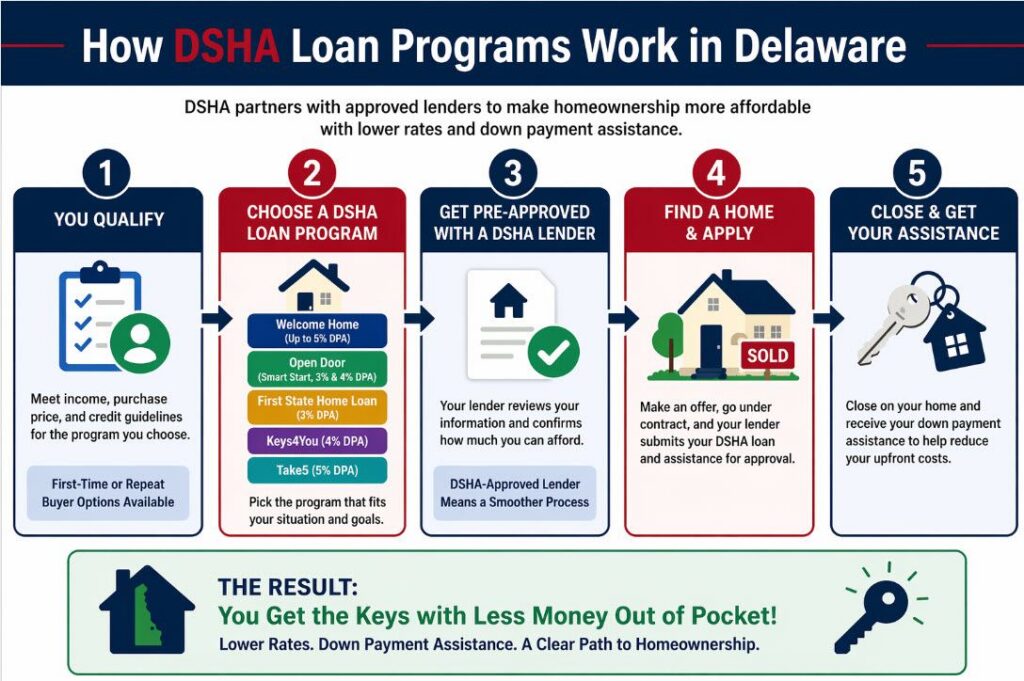
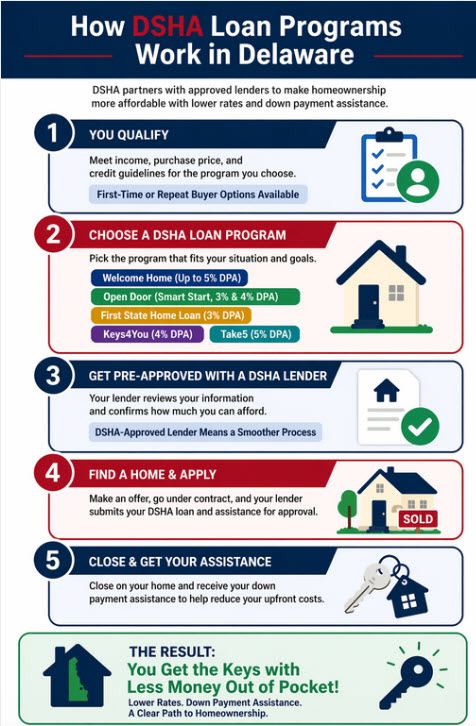
As a DSHA-approved lender here in Delaware, I work with these programs every day. The Delaware State Housing Authority is the state’s official housing finance agency, and their home loan programs are designed to help low- and moderate-income Delaware residents become homeowners by offering below-market interest rates and down payment assistance. DSHA does not lend money directly – they work through a network of approved lenders, including the John Thomas Team in Newark, Delaware.
Every DSHA mortgage is a 30-year, fixed-rate loan. You choose the loan type – FHA, VA, USDA, or Conventional – and DSHA layers in a competitive interest rate and, if you qualify, a second loan to cover your down payment and closing costs. The interest rate is set by DSHA and is the same no matter which approved lender you use. That’s actually a good thing: it removes rate shopping as a factor and means you can focus on finding an experienced DSHA lender who will guide you through the process correctly. You can learn more about DSHA’s programs directly on the Delaware Mortgage Program website (DSHA).
There are two primary mortgage programs under the Delaware Mortgage Program: Welcome Home (for first-time buyers) and Open Door (for both first-time and repeat buyers). Each can be paired with down payment assistance options. Both Welcome Home and Open Door offer First State Home Loan (3%) and Keys4You (4%). Take5 (5%) and Diamond in the Rough (5%) are Welcome Home only. We will cover each one in detail below.
What Are the Current Active DSHA Programs in Delaware?
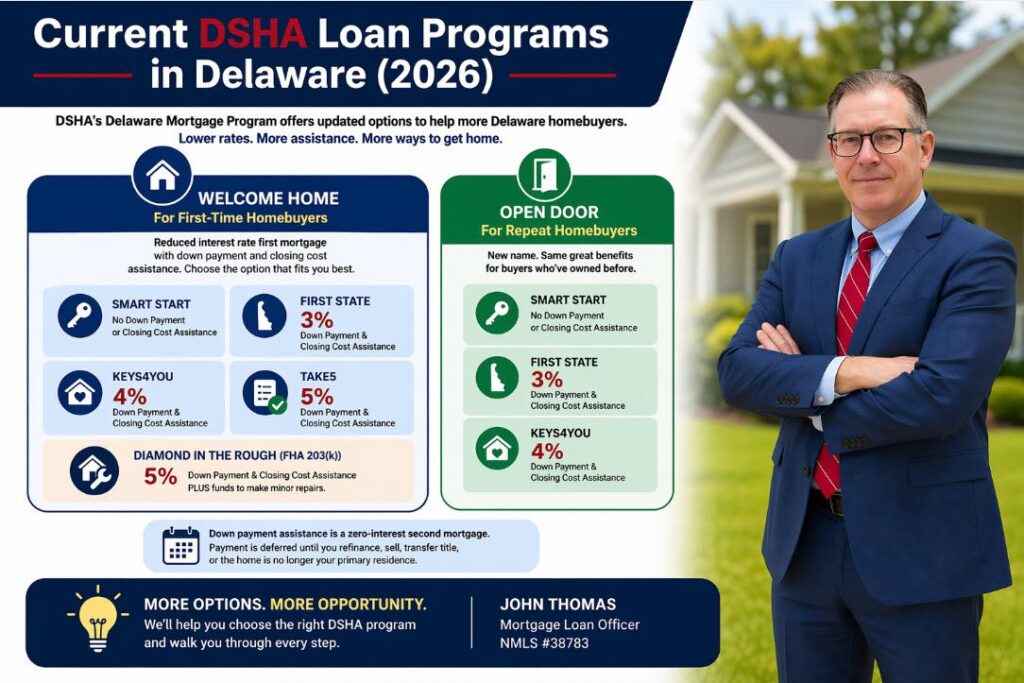

Here’s the most important thing to understand before we go further: several programs you’ll find on national websites no longer exist or have been replaced. The old Single Family Mortgage Revenue Bond program, the SMAL $8,000 deferred loan with 3% annual interest, and the “Preferred Plus” branding referenced on many national sites are outdated. The current DSHA program structure was relaunched in 2024 and funded with a $75 million tax-exempt bond – DSHA’s first since 2013. Then in April 2026, DSHA launched the Delaware Mortgage Program – a single rebrand event that retired the longtime “Kiss Your Landlord Goodbye” campaign, renamed Home Again to Open Door, branded the existing 4% DPA as Keys4You and opened it to both Welcome Home and Open Door, and launched Take5 as a new 5% DPA option exclusive to Welcome Home. That April 2026 lineup is the framework still in place today.
The active DSHA first mortgage programs and their associated DPA options as of 2026 are:
| DSHA First Mortgage | Who It’s For | DPA Options Available | Max DPA |
|---|---|---|---|
| Welcome Home | First-time homebuyers only | Smart Start / First State 3% / Keys4You 4% / Take5 5% / Diamond in the Rough 5% | 5% of loan amount |
| Open Door | First-time AND repeat buyers | Smart Start / First State 3% / Keys4You 4% | 4% of loan amount |
Each first mortgage program can also stand alone without DPA (called Smart Start) – but most buyers use the DPA option to reduce their out-of-pocket costs. Let’s break each program down.
DSHA Welcome Home Program (First-Time Buyers)
The Welcome Home program is DSHA’s flagship option for first-time homebuyers – defined as anyone who has not owned a home as their primary residence in the past three years. It offers below-market interest rates on 30-year fixed loans and can be combined with DPA to cover a significant portion of your upfront costs.
Welcome Home Eligibility Requirements:
- Must be a first-time homebuyer (no primary residence ownership in past 3 years)
- Minimum credit score of 620
- Credit scores between 620-659 require completion of a HUD-approved housing counseling course
- Income must be at or below county limits (see income limit table below). Effective April 15, 2025: Welcome Home counts only income of borrowers on the Note and/or Mortgage – not all household members.
- Property must be primary residence in Delaware
Welcome Home and Open Door Sales Price Limits (Single Family), effective for new reservations on or after June 8, 2026:
- New Castle County (non-targeted): $659,385
- New Castle County (targeted areas): $805,916
- Kent & Sussex Counties (non-targeted): $566,354
- Kent & Sussex Counties (targeted areas): $692,211
Homes in designated “targeted areas” have significantly higher purchase price limits and also waive the first-time homebuyer requirement. Read the complete DSHA Welcome Home program guide for details on income limits, purchase price caps, and which loan types pair with Welcome Home.
DSHA Open Door Program (First-Time and Repeat Buyers)
The Open Door program serves both first-time and repeat homebuyers. It also comes into play if your household income exceeds the Welcome Home limits – Open Door has higher income thresholds, which means more buyers qualify. This is a critical distinction that most buyers don’t know about: if someone tells you that you’re “over the income limit” for DSHA, there may still be a path through Open Door.
Open Door Eligibility Requirements:
- Open to both first-time and repeat buyers
- Minimum credit score of 620
- Credit scores between 620-659 require HUD-approved housing counseling
- Income must be at or below Open Door county limits (higher than Welcome Home). Effective April 15, 2025: Open Door counts only qualifying income on the loan application (1003) – not all household members’ income.
- Property must be primary residence in Delaware
Get the full breakdown on the DSHA Open Door loan – including income limits, DPA options, and how Open Door differs from Welcome Home. Note: Open Door replaced the legacy “Home Again” program in DSHA’s April 2026 Delaware Mortgage Program rebrand. If you previously researched DSHA Home Again, Open Door is the current equivalent.
What Are the DSHA Income Limits for 2026?
DSHA income limits Delaware (effective for new reservations on or after June 8, 2026): Welcome Home non-targeted income limits are $122,700 (1-2 persons) and $141,105 (3+ persons) in New Castle County; $111,400 / $128,110 in Kent and Sussex Counties. Open Door limits are higher – up to $147,240 (1-2 persons) and $184,050 (3+ persons) in New Castle County; $133,680 / $167,100 in Kent and Sussex Counties. Welcome Home targeted-area income limits are higher still: $147,240 / $171,780 in New Castle County and $133,680 / $155,960 in Kent and Sussex Counties.
Welcome Home Income Limits (Non-Targeted Areas):
| County | 1-2 Person Household | 3+ Person Household |
|---|---|---|
| New Castle County | $122,700 | $141,105 |
| Kent & Sussex Counties | $111,400 | $128,110 |
Open Door Income Limits:
| County | 1-2 Person Household | 3+ Person Household |
|---|---|---|
| New Castle County | $147,240 | $184,050 |
| Kent & Sussex Counties | $133,680 | $167,100 |
Welcome Home Income Limits (Targeted Areas):
| County | 1-2 Person Household | 3+ Person Household |
|---|---|---|
| New Castle County | $147,240 | $171,780 |
| Kent & Sussex Counties | $133,680 | $155,960 |
Targeted areas carry higher income limits than the non-targeted figures (the Welcome Home targeted limits are shown in the table above) and also waive the first-time homebuyer requirement. If you’re looking at a home in a targeted census tract, your income eligibility expands significantly. Call us at 302-703-0727 and we can check whether a specific property is in a targeted area. These limits took effect for new reservations on or after June 8, 2026.
How Does DSHA Down Payment Assistance Actually Work?
How DSHA down payment assistance works: DSHA down payment assistance is a zero-interest deferred second mortgage – not a grant – equal to 3%-5% of your loan amount. No monthly payments are required. The balance is repaid when you sell, refinance, or no longer use the home as your primary residence. It can cover your down payment, closing costs, or both depending on the program.
Down payment assistance through DSHA is structured as a second mortgage – not a grant. The distinction matters. The assistance amount is calculated as a percentage of your first mortgage loan amount (not the purchase price), and the balance is deferred with no monthly payments required. The loan becomes due when you refinance, sell, transfer title, or no longer occupy the home as your primary residence.
There are four primary DPA options currently available through DSHA’s first mortgage programs, plus two forgivable flat-dollar options for specific buyer situations:
DSHA First State Home Loan DPA Program (3%)
The First State Home Loan provides 3% of your final loan amount as a deferred second mortgage with zero interest. There are no monthly payments, and the balance is deferred until the property is sold, refinanced, or is no longer your primary residence. The 3% option is available under both Welcome Home and Open Door.
Example: A $350,000 purchase with a $343,000 loan ? First State Home Loan 3% = $10,290 in DPA. That’s a significant reduction in what you need to bring to closing.
See how the First State Home Loan 3% DPA works – including which loan types it pairs with and who benefits most from this option.
Keys4You Home Loan (4% DPA – Welcome Home and Open Door)
The Keys4You Home Loan is a newer DPA option available under both Welcome Home and Open Door. It provides a zero-interest deferred second mortgage equal to 4% of your first mortgage loan amount for down payment and closing costs assistance. No monthly payments are required. The balance is deferred until refinance, sale, transfer of title, or the property is no longer used as a primary residence.
For repeat buyers using Open Door, Keys4You is the maximum DPA available – 4% of loan amount. Read the full Keys4You Home Loan program details for eligibility rules, rates, and payment examples.
Take5 Home Loan (5% DPA – Welcome Home Only)
The Take5 Home Loan provides a zero-interest deferred second mortgage equal to 5% of your first mortgage loan amount – the highest DPA percentage available in the Delaware Mortgage Program without a renovation requirement. No monthly payments are required, and the balance is deferred until refinance, sale, transfer of title, or the property is no longer your primary residence. Take5 is available under the Welcome Home program only – it is not available under Open Door. This makes Welcome Home the stronger program for first-time buyers who qualify on income, as it offers both higher DPA and lower rates.
Get the complete breakdown of the DSHA Take5 5% DPA program – including how it compares to Keys4You and when first-time buyers should choose Take5 over the 4% option.
DSHA Diamond in the Rough DPA Program (5% + FHA 203k)
The Diamond in the Rough program pairs an FHA 203(k) Limited renovation loan with 5% of the loan amount in DPA – the highest DPA percentage available through DSHA. It’s designed specifically for buyers purchasing a home that needs minor repairs or updates (up to $75,000 in renovation costs, per HUD Mortgagee Letter 2024-13 effective November 4, 2024). This is an excellent option in Delaware’s current market, where a lot of move-in-ready homes are priced aggressively but fixer-uppers still offer real value. The purchase price and rehab costs are combined into a single loan, and the work is completed after closing.
The Diamond in the Rough option is available under the Welcome Home program (first-time buyers) only. Learn how the Diamond in the Rough renovation loan works and see whether your target property qualifies.
Home Sweet Home Program ($12,000 Forgivable – Currently Out of Funds)
The Home Sweet Home program provides a zero-interest, forgivable second loan of $12,000 for buyers purchasing a home with a maximum sales price of $285,000. Unlike the First State Home Loan (which is deferred until sale), Home Sweet Home is forgiven at a rate of 10% per year – meaning after 10 years of living in the home as your primary residence, the entire balance is forgiven and you owe nothing. This is an exceptional benefit for buyers purchasing in more affordable price ranges, particularly in Kent and Sussex Counties.
Funding status (April 2026): Home Sweet Home is currently out of funds and DSHA has not announced plans to refund the program. National mortgage sites and older Delaware articles still reference this program as active, but it is not currently accepting applications. If you specifically searched for Home Sweet Home, the active alternatives that serve a similar buyer profile are the DSHA First State Home Loan (3% DPA) and the Keys4You 4% DPA program – both paired with Welcome Home or Open Door. We maintain a dedicated Home Sweet Home program page with the full historical details and will update it the moment funding returns.
Delaware Diamonds Program ($10,000 Essential Workers – Currently Out of Funds)
The Delaware Diamonds program provides a $10,000 zero-interest forgivable second loan specifically for essential workers including teachers, healthcare workers, first responders, and veterans. Like Home Sweet Home, the balance is forgiven over 10 years (10% per year). This is a targeted benefit that many eligible buyers don’t know about.
Funding status (April 2026): Delaware Diamonds is currently out of funds with no announced plans to refund the program. Several national mortgage websites still list this program as active – it is not. If you are an essential worker who searched specifically for Delaware Diamonds, the active DSHA options available to you right now are the same programs available to any eligible buyer: Welcome Home or Open Door paired with First State (3%), Keys4You (4%), or Take5 (5% Welcome Home only). Delaware veterans also have access to the Delaware VA loan combined with DSHA DPA, which is often the strongest combination for eligible service members. Our Delaware Diamonds program page retains the full program details and will be updated if funding returns.
Want to estimate your Delaware down payment assistance? Call us at 302-703-0727 or Schedule Appointment and we’ll walk through your actual numbers – income, county, loan amount – and tell you exactly how much DSHA assistance you qualify for and what you’ll need to bring to closing.
What Are the Current DSHA Interest Rates?
DSHA sets rates based on the underlying bond and updates them periodically. The rate is the same regardless of which approved lender you use. Note that using a DPA second mortgage typically comes with a slightly higher first mortgage rate – this is standard across all DPA programs because the lender is earning less on the front end. The rate difference reflects the cost of the assistance. Here are the current DSHA rates:
| Loan Product | Welcome Home Rate | Open Door Rate |
|---|---|---|
| FHA / VA / RD – Smart Start (no DPA) | 5.625% | 7.000% |
| FHA / VA / RD – First State Home Loan 3% | 5.875% | 7.625% |
| FHA / VA / RD – Keys4You Home Loan 4% | 6.125% | 7.750% |
| FHA / VA / RD – Take5 Home Loan 5% | 6.625% | Not available |
| FHA – Diamond in the Rough 5% | 6.625% | Not available |
| Conventional – Smart Start (no DPA) | 6.125% | 7.375% |
| Conventional – First State Home Loan 3% | 6.375% | 8.000% |
| Conventional – Keys4You Home Loan 4% | 6.500% | 8.125% |
| Conventional – Take5 Home Loan 5% | 7.000% | Not available |
Rates are set by DSHA and subject to change when new bond funding is issued. Rates shown are the DSHA rate sheet dated September 14, 2026. They are not a quote, not an APR, and not a rate lock. Current rates are always published on the Delaware Mortgage Program loan products page. Call 302-703-0727 for today’s rate before committing.
APR (Annual Percentage Rate) will be higher than the interest rate shown and varies based on loan amount, loan type, and applicable fees. Contact us for your specific APR disclosure. Equal Housing Lender.
How Do DSHA Programs Compare? A Side-by-Side Breakdown
| Program | Who Qualifies | DPA Amount | DPA Type | Best For |
|---|---|---|---|---|
| Welcome Home + Smart Start | First-time buyers | None | N/A | Buyers who don’t need DPA |
| Welcome Home + First State 3% | First-time buyers | 3% of loan | Deferred 2nd mortgage, 0% interest | First-time buyers with limited savings |
| Welcome Home + Keys4You 4% | First-time buyers | 4% of loan | Deferred 2nd mortgage, 0% interest | First-time buyers needing more than 3% DPA |
| Welcome Home + Take5 5% | First-time buyers | 5% of loan | Deferred 2nd mortgage, 0% interest | First-time buyers needing maximum DPA |
| Welcome Home + Diamond in the Rough 5% | First-time buyers | 5% of loan | Deferred 2nd mortgage, 0% interest | First-time buyers purchasing a fixer-upper |
| Open Door + Smart Start | First-time and repeat buyers | None | N/A | Repeat buyers who don’t need DPA |
| Open Door + First State 3% | First-time and repeat buyers | 3% of loan | Deferred 2nd mortgage, 0% interest | Repeat buyers or higher-income buyers |
| Open Door + Keys4You 4% | First-time and repeat buyers | 4% of loan | Deferred 2nd mortgage, 0% interest | Repeat buyers needing maximum DPA (Open Door max is 4%) |
| Home Sweet Home ($12,000) | First-time and repeat buyers | $12,000 flat | Forgivable over 10 years | Currently out of funds – see active alternatives |
| Delaware Diamonds ($10,000) | Essential workers only | $10,000 flat | Forgivable over 10 years | Currently out of funds – see active alternatives |
Who Are DSHA Loans Best For in Delaware?
Delaware DSHA loan programs are not one-size-fits-all. Here’s a clear breakdown of who benefits most – and who may be better served by a different mortgage approach.
| DSHA Loans Are a Strong Fit For | DSHA Loans May Not Be the Best Fit For |
|---|---|
| First-time homebuyers in Delaware with limited savings | High-income households above program income limits |
| Buyers who qualify for 3%-5% down payment assistance through First State, Keys4You, Take5, or Diamond in the Rough | Real estate investors (primary residence required) |
| Delaware residents purchasing a primary home | Buyers purchasing a second home or vacation property |
| Veterans combining a Delaware VA loan with DSHA DPA for closing cost coverage | Buyers who need to close in under 30 days (DSHA has additional steps) |
| First-time buyers who need 5% DPA through Take5 (Welcome Home only) | Buyers with credit scores below 620 (credit improvement needed first) |
| Repeat buyers with income above Welcome Home limits (Open Door + Keys4You 4% path) | Buyers purchasing fixer-uppers requiring more than $75,000 in repairs |
DSHA Loan Requirements Checklist for Delaware Buyers
DSHA loan requirements Delaware: To qualify for a DSHA loan in Delaware you need a minimum 620 credit score, household income at or below county limits, a primary residence in Delaware, and you must apply through a DSHA-approved lender. Scores between 620-659 require HUD-approved housing counseling before closing.
- Credit score: 620 minimum. Scores 620-659 require HUD-approved housing counseling (~8 hours, ~$125 fee) before closing.
- Income limits: Income must be at or below DSHA county limits (increased effective for new reservations on or after June 8, 2026). Effective April 15, 2025: Welcome Home counts only income of borrowers on the Note/Mortgage; Open Door counts only qualifying income on the 1003. Welcome Home non-targeted limits: up to $122,700 (1-2 persons) in New Castle County; $111,400 in Kent/Sussex. Open Door limits are higher – see income tables above.
- Primary residence: The property must be your primary home in Delaware – not an investment property or second home.
- First-time buyer status: Required for Welcome Home only (no primary residence ownership in past 3 years). Open Door is open to all buyers (first-time and repeat). Targeted area purchases waive the first-time buyer requirement.
- Approved lender: You must work with a DSHA-approved lender – DSHA does not accept applications directly. The John Thomas Team is a DSHA-approved lender in Newark, Delaware.
- Sales price limits (Welcome Home and Open Door, effective June 8, 2026): Non-targeted areas: $659,385 (New Castle County) / $566,354 (Kent & Sussex). Targeted areas: $805,916 (New Castle County) / $692,211 (Kent & Sussex).
- Loan type: DSHA programs are available with FHA, VA, USDA, and Freddie Mac Conventional loans. The loan type you choose affects your down payment requirement and rate.
- Delaware housing assistance programs: DSHA is the primary source of state-backed mortgage assistance in Delaware – other county and city programs (New Castle County DPS, HIP, VHAP) may also layer on top for additional help.
What Does a Real DSHA Loan Payment Look Like?
DSHA monthly payment example: On a $300,000 home using a DSHA Welcome Home FHA loan at 6.00% interest rate (6.6% APR) with First State Home Loan 3% DPA ($8,730 in assistance), the estimated monthly payment is approximately $2,100-$2,300 including principal, interest, taxes, insurance, and FHA mortgage insurance. Exact figures depend on your tax rate, insurance costs, and final loan amount.
A lot of buyers are surprised by how manageable the monthly payment looks when you factor in the DPA reducing your loan amount. Let’s walk through a real scenario:
| Scenario | Details |
|---|---|
| Purchase price | $300,000 |
| Loan type | FHA via DSHA Welcome Home |
| Down payment required (FHA 3.5%) | $10,500 |
| First State Home Loan 3% DPA | ~$8,730 (3% of loan) |
| Estimated buyer cash to close | ~$3,000-$6,000 (after DPA + seller concessions) |
| DSHA Welcome Home rate (FHA + 3% DPA) | 6.00% interest rate / 6.6% APR |
| Estimated monthly P&I | ~$1,740 |
| Estimated taxes + insurance + MIP | ~$400-$550/month (varies by county) |
| Estimated total monthly payment | ~$2,140-$2,290 |
This is an illustrative estimate. Your actual payment will depend on your specific loan amount, property tax rate, homeowner’s insurance, and HOA fees if applicable. Call 302-703-0727 for a personalized payment estimate based on your actual numbers.
DSHA vs. FHA vs. Conventional: What’s the Difference?
Quick answer: DSHA is not a loan type – it’s a Delaware state program layer. FHA and Conventional are loan types. A DSHA mortgage is an FHA or Conventional loan that has a DSHA-negotiated interest rate and optional down payment assistance attached to it. You can have a DSHA + FHA loan, or a DSHA + Conventional loan. They are not competing options – they work together.
This is one of the most common points of confusion for Delaware homebuyers searching for their options. Here’s how to think about it:
| Feature | FHA Loan (standalone) | Conventional Loan (standalone) | DSHA Mortgage (Delaware) |
|---|---|---|---|
| What it is | Federal loan type with lenient credit rules | Fannie Mae / Freddie Mac loan type | State program layer on top of FHA or Conventional |
| Min. down payment | 3.5% (620+ score) | 3% (Freddie Mac) | Same as underlying loan – DPA covers most or all |
| Down payment assistance | Not built in | Not built in | 3%-5% DPA available through First State Home Loan, Keys4You, Take5, or Diamond in the Rough |
| Interest rate | Market rate (varies by lender) | Market rate (varies by lender) | Set by DSHA – same rate regardless of lender |
| Income limits | None | None | Yes – by county and household size |
| First-time buyer required? | No | No | Welcome Home only (first-time buyers). Open Door is open to all buyers. |
| Best for | Buyers with credit challenges who don’t qualify for DSHA income limits | Buyers with stronger credit and no need for DPA | Delaware buyers who qualify for income limits and want down payment help |
The bottom line: if you qualify for a DSHA mortgage in Delaware, it is almost always the better choice over a standalone Delaware FHA loan or Conventional loan because of the built-in rate advantage and down payment assistance. The only reason not to use DSHA is if your household income is over the program limits – in which case a standard FHA or Conventional loan is the path forward. Call us at 302-703-0727 and we’ll run both scenarios side by side for you.
What Programs Do National Websites Get Wrong About Delaware DSHA?
This is a section you won’t find on most websites, but I think it’s critically important. When Delaware buyers search for DSHA programs online, they frequently land on national aggregate sites that are publishing outdated information. Here’s what to watch out for:
The April 2026 rebrand to “Delaware Mortgage Program”: In April 2026, DSHA launched the Delaware Mortgage Program – a single rebrand event that retired the longtime “Kiss Your Landlord Goodbye” campaign and consolidated all program information at destatehousing.com. As part of that same rebrand, “Home Again” was renamed to Open Door, the existing 4% DPA option (which DSHA had reintroduced in 2025 with no official product name and made available only with Home Again) was branded as Keys4You and opened to both Welcome Home and Open Door, and a new 5% DPA option called Take5 was launched under Welcome Home only. There was no separate 2025 program rebrand – the April 2026 launch was the single name-change event. Any site still referencing kissyourlandlordgoodbye.com or describing “Home Again” as currently active is working from outdated information.
The “SMAL Loan” ($8,000 at 3% interest): Many sites still describe the old Second Mortgage Assistance Loan (SMAL) – an $8,000 second mortgage with 3% annual interest that was deferred for 30 years but accrued interest the entire time. This program has been replaced. The current First State Home Loan DPA carries zero interest and is based on a percentage of your loan amount, which for most buyers today represents significantly more assistance than the old $8,000 cap.
“Preferred Plus” branding: Some national sites still reference “DSHA Preferred Plus” as an active program name. This was the old DPA branding and has been replaced by the current First State Home Loan structure under Welcome Home and Open Door. If you see “Preferred Plus,” the site is out of date.
The “Delaware Revenue Bond Program” or “Single Family Mortgage Revenue Bond”: These were the original names for what is now Welcome Home and Open Door. They’re the same underlying program concept – state bond-funded below-market mortgages – but the program names, income limits, and DPA structures have all been updated.
When you work with us, you get current program information because we are actively originating DSHA loans. We’re not pulling from a cached database – we’re on the ground doing these loans every week.
What Delaware Buyers Should Know About Down Payment Requirements
One of the most common misconceptions I hear at our homebuyer seminars is that buyers think they need 20% down to buy a home. That number is a myth for most buyers. Here’s what DSHA programs actually require:
- FHA-backed DSHA loans: Require 3.5% down (before DPA is applied). With First State Home Loan 3%, most or all of this is covered by the DPA.
- Conventional DSHA loans (Freddie Mac): Require 3% down. First State Home Loan 3% can cover this entirely.
- VA-backed DSHA loans: Zero down required – and DSHA DPA covers closing costs on top of that. This is the most powerful combination available to Delaware veterans. Major national lenders like Veterans United and Navy Federal don’t offer state DPA programs, which means Delaware VA loan borrowers who use DSHA get a genuine advantage those lenders can’t match.
- USDA-backed DSHA loans: Zero down required for eligible rural areas of Delaware. USDA loans in Delaware combined with DSHA DPA means closing costs can be significantly reduced for buyers in Kent and Sussex County rural areas.
Keep in mind that closing costs in Delaware typically run between 2%-5% of the purchase price. Transfer tax in Delaware is 4% total – under a standard Delaware Association of Realtors contract, this is split 2% buyer / 2% seller. However, if you’re buying a new construction home from a builder, the builder’s contract may require the buyer to pay the full 4% transfer tax. This is a significant cost difference that catches many first-time buyers off guard, so please make sure you ask us about this before going under contract on new construction.
Between DPA from DSHA, seller-paid closing costs negotiated into your offer, and the various down payment options above, many Delaware buyers are purchasing homes with far less out of pocket than they expected. For a complete look at all current down payment assistance options in Delaware – including non-DSHA programs like New Castle County DPS, Wilmington First Start, and the Sussex County Housing Trust Fund – visit our full guide to Delaware Down Payment Assistance Programs.
Do You Have to Be a First-Time Buyer to Use DSHA Programs?
No – and this surprises a lot of people. The Open Door program is available to both first-time and repeat buyers. Even the Welcome Home program allows repeat buyers to purchase in designated “targeted areas” without the first-time buyer restriction. If you bought a home eight years ago, sold it, and have been renting since then, you may also qualify as a “first-time buyer” under DSHA’s three-year lookback rule. And if none of those apply, Open Door is still a viable path with competitive rates and DPA options. The short answer: don’t disqualify yourself before talking to us.
How Does the Housing Counseling Requirement Work?
If your credit score is between 620 and 659, DSHA requires you to complete a HUD-approved housing counseling course before closing. In Delaware, this is typically an 8-hour course available through approved housing counseling agencies, and there is usually a fee of around $125. This is not a punishment – it’s genuinely useful education that covers budgeting, understanding your mortgage, and long-term homeownership. We can point you to approved agencies in your area. Once you complete counseling, you’re cleared for the DSHA program regardless of your score being in that range.
If your score is 660 or above, housing counseling is optional (not required). We always recommend it for buyers who want a deeper understanding of the process, but it won’t hold up your timeline if you’re ready to move forward.
DSHA Loans in Wilmington, Dover, and Newark, Delaware
DSHA loan programs are available statewide, but buyer needs and market conditions vary by city. Here’s how these Delaware DSHA mortgage programs play out in the three major markets we serve most frequently:
Wilmington, Delaware: Wilmington buyers often benefit from both DSHA programs and targeted area designations that expand income limits and remove the first-time buyer requirement. Several Wilmington zip codes fall within DSHA targeted census tracts, meaning repeat buyers can still access Welcome Home program benefits – and income limits are roughly 20% higher than standard. Many Wilmington first-time buyers use the DSHA Welcome Home FHA loan combined with the First State Home Loan 3% DPA to purchase in the city’s growing residential neighborhoods.
Dover, Delaware: Dover is in Kent County, where Welcome Home non-targeted income limits are $111,400 for 1-2 person households and $128,110 for households of three or more (effective for new reservations on or after June 8, 2026). Median home prices in the Dover market are lower than New Castle County, which makes DSHA’s First State (3%) and Keys4You (4%) DPA programs especially impactful – a smaller loan means a smaller out-of-pocket cost after DPA is applied. Dover Air Force Base proximity also means a significant portion of our buyers here are veterans who combine a Delaware VA loan through DSHA with DPA for closing cost coverage – a combination that gives Delaware veterans a genuine edge that national VA lenders simply can’t replicate.
Newark, Delaware: Newark is where our office is located, and it’s one of the most active DSHA markets in New Castle County. The University of Delaware drives a younger first-time buyer demographic who typically use the DSHA Welcome Home program with First State Home Loan 3% DPA. Newark’s home prices have been rising, making the DPA especially valuable for buyers stretching to qualify. As a DSHA-approved lender based right here in Newark, we are deeply familiar with the local market, typical seller concession norms, and which neighborhoods offer the best value for DSHA-eligible buyers.
What Is the Step-by-Step Process to Get a DSHA Loan?
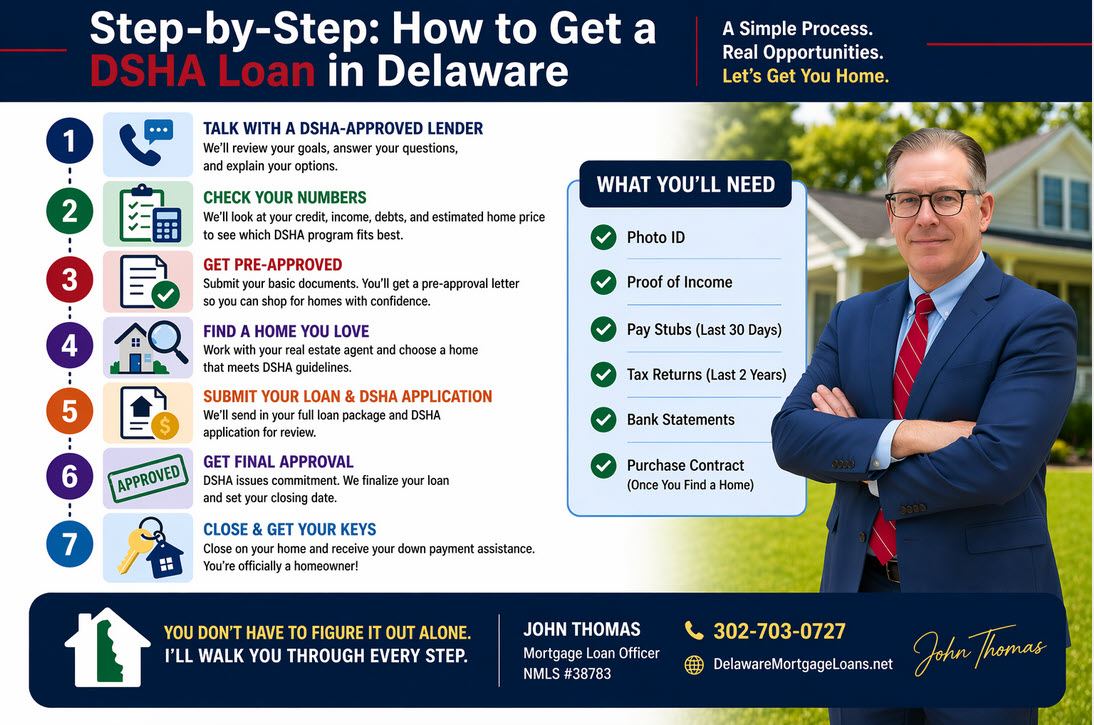
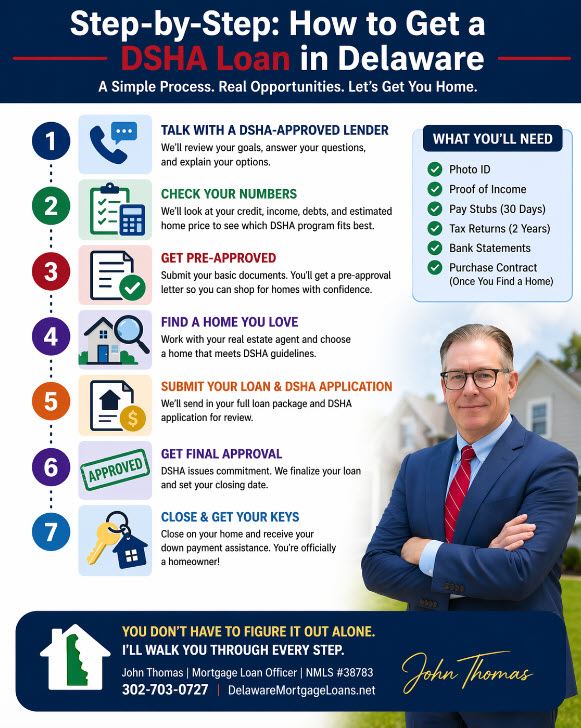
Here’s how the process works when you work with our team:
- Complete the online application at Apply Online or call 302-703-0727. We’ll do a credit check and review your income and household size.
- Determine which DSHA program fits – Welcome Home vs. Open Door, and which DPA option makes the most sense given your purchase price and loan amount goals.
- If needed, complete housing counseling – required for scores 620-659. We’ll connect you with an approved provider.
- Get pre-approved with your specific DSHA program identified. Your pre-approval letter will reflect the DSHA rate and DPA.
- Find a home and go under contract. Your real estate agent should be aware you’re using a DSHA loan so they can structure the offer appropriately.
- Underwriting and closing – DSHA loans close like any other mortgage. Settlement in Delaware is handled by a licensed attorney or title company.
One important note: DSHA loan interest rates are set at the time of rate lock, not at pre-approval. Rate locks typically last 60-90 days on DSHA loans. We’ll manage the timing carefully to protect your rate.
John Thomas’s Book: The Delaware DSHA Guide in Print
I wrote Your Guide to Buying Your First Home in Delaware specifically to help buyers understand programs like DSHA from A to Z – the application process, income limits, what happens after closing, and much more. It’s available on Amazon (ISBN: 0557349826) and I also walk through DSHA programs in detail during our monthly Delaware First Time Home Buyer Seminars. If you want the complete picture on buying your first home in Delaware – including DSHA programs, credit, down payment, and the full purchase process – visit our Delaware First Time Home Buyer Guide.
You can also find video walkthroughs of DSHA programs, income limit updates, and buyer Q&As on our Delaware Mortgage Loans YouTube channel.
John Thomas, NMLS #38783 | NMLS #38783 DSHA Approved Lender Author
Branch Manager & Division Vice President of Sales, John Thomas Team with AnnieMac Home Mortgage
John Thomas is a DSHA-approved mortgage loan officer with the John Thomas Team in Newark, Delaware. With over 20 years of experience and 3,000+ Delaware buyers helped, John specializes in DSHA programs, FHA, VA, USDA, and first-time homebuyer loans across all three Delaware counties. He is the author of Your Guide to Buying Your First Home in Delaware and hosts monthly homebuyer education seminars in Newark, Dover, and Wilmington.
John’s hands-on expertise with DSHA’s Welcome Home, Open Door, First State Home Loan, Keys4You, Take5, and Diamond in the Rough programs means his clients get current, accurate guidance – not recycled information from national aggregate websites. He has been helping Delaware families navigate DSHA programs since their original bond program structure and through every program update since.
Stats: 20+ Years in Delaware Mortgages | 3,000+ Buyers Helped | 1,000+ DSHA/DPA Loans | DE & MD Service Area | CMP Certified Mortgage Planner
John holds a Bachelor of Science in Physics Education from the University of Delaware and a Master of Science in Curriculum and Instruction from Delaware State University. Licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA). NMLS #38783. The license list is a credential, not a service-area claim; day-to-day origination is Delaware and Maryland.
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com | Schedule Appointment | About John Thomas | See John Thomas Team on Google | YouTube Channel | Facebook
Related Delaware Mortgage Guides
DSHA is one piece of the Delaware homebuying puzzle. These related guides cover the specific DSHA programs, down payment assistance options, and first-time buyer resources that support this page:
DSHA First Mortgage Programs
- DSHA Welcome Home Mortgage Loan – the first-time buyer program with the lowest rates and widest DPA access, including Take5 and Diamond in the Rough.
- DSHA Open Door Loan Delaware – the first-time AND repeat buyer program with higher income limits and Keys4You 4% DPA as its maximum assistance.
- DSHA Home Again Program (legacy reference) – Home Again was renamed to Open Door in DSHA’s April 2026 Delaware Mortgage Program rebrand. This legacy page is kept for buyers who researched the program under the old name.
DSHA Down Payment Assistance Options
- First State Home Loan DPA program – 3% DPA, available under both Welcome Home and Open Door.
- Keys4You 4% down payment assistance – Open Door’s maximum DPA and a strong option for first-time buyers who need more than 3%.
- Take5 Home Loan program – 5% DPA, the highest non-renovation DPA available, for Welcome Home first-time buyers only.
- Diamond in the Rough FHA 203k program – 5% DPA paired with an FHA 203(k) Limited renovation loan for fixer-upper purchases.
DSHA Programs Currently Out of Funds
These two programs are referenced on outdated national mortgage sites but are not currently accepting applications. We keep the pages live so Delaware buyers who searched for them can find accurate information and redirect to active alternatives.
- DSHA Home Sweet Home $12,000 forgivable DPA – flat-dollar forgivable second loan for homes priced at $285,000 or below, forgiven 10% per year over 10 years. Out of funds as of April 2026.
- Delaware Diamonds $10,000 essential worker DPA – forgivable DPA for teachers, healthcare workers, first responders, and veterans. Out of funds as of April 2026.
Delaware First-Time Buyer Resources
- Complete Delaware Down Payment Assistance Programs guide – covers every DPA option available in Delaware including county and city programs (New Castle County DPS, Wilmington First Start, Dover First Start, Sussex County Housing Trust Fund).
- Delaware First Time Home Buyers Guide – the full pillar page covering programs, credit, down payment, seminars, and the complete purchase process.
- Delaware Mortgage Credit Certificate (MCC) – program ended August 15, 2025. The MCC was a dollar-for-dollar federal tax credit that previously paired with DSHA loans, but DSHA discontinued the program effective August 15, 2025. The page is preserved for buyers researching the historical program.
FAQ on DSHA Loan Programs
What is the DSHA loan program in Delaware?
The Delaware State Housing Authority (DSHA) offers affordable 30-year fixed-rate mortgage programs – Welcome Home (for first-time buyers) and Open Door (for all buyers) – with interest rates at or below current market rates. These programs are funded through state bonds and available statewide across New Castle, Kent, and Sussex Counties. Buyers can also add down payment assistance (DPA) through programs like the First State Home Loan (3%), Keys4You (4%), Take5 (5% Welcome Home only), or Diamond in the Rough (5% Welcome Home only). DSHA does not lend directly – you apply through an approved lender like the John Thomas Team in Newark, Delaware.
Do I have to be a first-time homebuyer to use DSHA programs?
No. While the Welcome Home program is limited to first-time homebuyers – defined as those who have not owned a primary residence in the past three years – the Open Door program is available to both first-time and repeat buyers. Buyers purchasing homes in DSHA-designated “targeted areas” may also access Welcome Home benefits even if they’ve owned a home before. If you’re not sure whether you qualify as a first-time buyer under DSHA’s rules, call us at 302-703-0727 and we’ll clarify your status right away.
What is the difference between the DSHA Welcome Home and Open Door programs?
Welcome Home is for first-time homebuyers and has lower income limits. Open Door (renamed from Home Again in DSHA’s April 2026 Delaware Mortgage Program rebrand) is available to both first-time and repeat buyers and carries higher income limits, making it an important option for buyers who exceed Welcome Home thresholds. Both programs offer the Smart Start loan (no DPA), the First State Home Loan DPA at 3%, and the Keys4You Home Loan at 4%. Welcome Home also adds Take5 (5%) and Diamond in the Rough (5% for renovation buyers). Open Door’s maximum DPA is 4% via Keys4You. If you’re told you’re over the income limit for one program, Open Door may still be a viable path.
How much down payment assistance can I get through DSHA?
DSHA down payment assistance ranges from 3% to 5% of your loan amount depending on the program. The First State Home Loan provides 3% and the Keys4You Home Loan provides 4% – both available under Welcome Home and Open Door. The Take5 Home Loan provides 5% under the Welcome Home program only. The Diamond in the Rough provides 5% for buyers using an FHA 203(k) renovation loan. All active DPA second mortgages carry zero interest and no monthly payments. Two additional forgivable programs – Home Sweet Home ($12,000 for homes under $285,000) and Delaware Diamonds ($10,000 for essential workers) – are currently out of funds with no announced refunding plans, despite still being referenced on outdated national websites.
What credit score do I need for a DSHA loan in Delaware?
The minimum credit score for any DSHA program is 620. Applicants with scores between 620 and 659 must complete a HUD-approved housing counseling course – typically an 8-hour course with an approximately $125 fee – before closing. Applicants with scores of 660 or higher have no counseling requirement, though it remains available as a free resource. If your score is below 620, ask us about our Get Mortgage Ready credit improvement program – we can often map out a realistic path to qualification within a specific timeframe based on your credit report.
Are DSHA income limits really that restrictive?
No – and this surprises many buyers. As of the limits effective for new reservations on or after June 8, 2026, Welcome Home allows non-targeted household incomes up to $122,700 for 1-2 person households and $141,105 for households of 3 or more in New Castle County. In Kent and Sussex Counties, those limits are $111,400 and $128,110 respectively. Open Door limits are even higher: up to $147,240 (1-2 person) and $184,050 (3+) in New Castle County, and $133,680 / $167,100 in Kent and Sussex. Targeted-area Welcome Home limits are higher still. Many dual-income households – including teachers, nurses, tradespeople, and state employees – qualify comfortably.
What Delaware transfer tax rules apply when using a DSHA loan?
Delaware transfer tax totals 4% of the purchase price. Under a standard Delaware Association of Realtors contract, this is split equally – 2% paid by the buyer and 2% paid by the seller. However, if you are purchasing a new construction home directly from a builder, the builder’s contract may require the buyer to pay the full 4% transfer tax. This is a significant cost difference that catches many first-time buyers off guard. DSHA down payment assistance can help offset this cost, but you need to know about it before going under contract. Always ask us to review the contract structure before you sign.
Can DSHA loans be combined with FHA, VA, or USDA loans?
Yes. DSHA’s Welcome Home and Open Door first mortgage programs are available with FHA, VA, USDA Rural Development, and Freddie Mac Conventional loan types. Each has a different base down payment requirement: FHA requires 3.5% down with a 620+ credit score, VA and USDA require zero down, and Freddie Mac Conventional requires 3% down. DSHA’s DPA programs layer on top of these and can offset a significant portion of your required down payment and closing costs – especially when combined with seller-paid concessions negotiated into your purchase offer.
What old DSHA programs no longer exist and why do websites still reference them?
Several programs still described on national mortgage websites are no longer active in their original form. The SMAL loan – an $8,000 deferred second mortgage at 3% annual interest – has been replaced by the current First State Home Loan DPA, which carries zero interest and is based on a percentage of your loan amount. The “Preferred Plus” branding no longer exists. The original “Single Family Mortgage Revenue Bond Program” name has been retired and replaced by Welcome Home and Open Door. In April 2026, DSHA launched the Delaware Mortgage Program at destatehousing.com – a single rebrand event that retired the longtime ‘Kiss Your Landlord Goodbye’ campaign, renamed Home Again to Open Door, branded the existing 4% DPA as Keys4You and opened it to both Welcome Home and Open Door, and launched Take5 as a new 5% DPA option. The Delaware Mortgage Credit Certificate (MCC) program also ended on August 15, 2025. National aggregate sites often pull from cached databases and don’t update when state programs change. Working with a DSHA-approved lender who is actively originating these loans is the only reliable way to get current program information.
How do I apply for a DSHA loan through John Thomas?
The easiest first step is to apply online at applywithjohnthomasteam.com or call our team directly at 302-703-0727. We’ll review your credit, income, household size, and target county – and identify exactly which DSHA program fits your situation. We’ll also estimate your actual out-of-pocket cost at closing so you have a clear number to work toward before you start home shopping. You can also schedule a free 30-minute consultation at schedule.johnthomasteam.com/30min. Our team is available seven days a week, including evenings, to accommodate buyers with work schedules.
Ready to Find Out Which DSHA Program Is Right for You?
We’ll review your income, credit, county, and purchase goal – and tell you exactly which DSHA program fits your situation, how much assistance you qualify for, and what you’ll need to bring to closing. No pressure, no obligation. Just straightforward answers from a DSHA-approved lender with 20+ years of Delaware experience.
Last Updated: September 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
John R. Thomas, NMLS #38783 | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net | Equal Housing Lender
Copyright (c) 2026 John R. Thomas, All Rights Reserved.
