DSHA Open Door Loan Program in Delaware: The Complete 2026 Guide


DSHA Open Door Quick Answer: The DSHA Open Door loan Delaware program is a 30-year fixed-rate mortgage for both first-time and repeat homebuyers through DSHA’s Delaware Mortgage Program. It replaced Home Again in DSHA’s April 2026 Delaware Mortgage Program rebrand and offers income limits higher than Welcome Home, with up to 4% down payment assistance through Keys4You or 3% through First State Home Loan.
- Program: DSHA Open Door (under the Delaware Mortgage Program)
- Best for: First-time and repeat buyers in Delaware (no first-time buyer requirement)
- DPA options: Smart Start (none), First State (3%), Keys4You (4%)
- Maximum assistance: 4% DPA via Keys4You
- Income limits – New Castle County: $147,240 (1-2 persons) / $184,050 (3+ persons)
- Income limits – Kent & Sussex Counties: $133,680 (1-2 persons) / $167,100 (3+ persons)
- Purchase price limits: $659,385 New Castle / $566,354 Kent & Sussex
- Minimum credit score: 620 (660 for manufactured homes; counseling required for 620-659)
- Replaces: DSHA Home Again (renamed April 2026; legacy page kept live for buyers searching old name)
- Contact: John Thomas, NMLS #38783 – call 302-703-0727 or schedule a free consultation
Reviewed by John Thomas, NMLS #38783, DSHA-approved lender | Last reviewed: April 2026
Source note: DSHA officially rebranded its single-family mortgage lending program as the Delaware Mortgage Program in April 2026 – renaming Home Again to Open Door, branding the 4% DPA as Keys4You, and launching Take5. See the official DSHA announcement at destatehousing.com.
| Feature | DSHA Open Door |
|---|---|
| Buyer type | First-time and repeat buyers |
| Minimum credit score | 620 (660 for manufactured homes) |
| DPA options | Smart Start (none) / First State 3% / Keys4You 4% |
| Maximum DPA | 4% of loan amount |
| Income limit (New Castle, 1-2 persons) | $147,240 |
| Income limit (New Castle, 3+ persons) | $184,050 |
| Income limit (Kent/Sussex, 1-2 persons) | $133,680 |
| Income limit (Kent/Sussex, 3+ persons) | $167,100 |
| Purchase price limit (New Castle) | $659,385 |
| Purchase price limit (Kent/Sussex) | $566,354 |
| Available statewide | Yes – New Castle, Kent, and Sussex Counties |
| Replaces | DSHA Home Again (renamed April 2026) |
The DSHA Open Door loan Delaware program is the official name for what was previously called DSHA Home Again Loan Program. I’m a DSHA-approved lender here in Delaware and I’ve been originating Open Door loans – and before that, Home Again loans – for years. If you’ve landed on this page because you heard “Home Again” no longer exists, you’re in the right place. DSHA renamed Home Again to Open Door in April 2026 as part of the new Delaware Mortgage Program launch – the same single rebrand that introduced Keys4You (4% DPA) and Take5 (5% DPA), and retired the longtime “Kiss Your Landlord Goodbye” campaign. The core purpose of the program is the same as Home Again was: helping buyers who are repeat homeowners or who exceed Welcome Home income limits access below-market mortgage rates and down payment assistance. See the full Home Again program history for context on the predecessor program. This page walks through everything: who qualifies, income limits, how much assistance you can get, current rates, and how to apply.
See If You Qualify for DSHA Open Door
We’ll review your income, credit, county, and purchase goal – then tell you exactly whether Open Door fits, how much DPA you qualify for, and what you’ll need to bring to closing. No pressure, no obligation.
Table of Contents
What Is the DSHA Open Door Loan Program?
What is DSHA Open Door: DSHA Open Door is a 30-year fixed-rate mortgage program under DSHA’s Delaware Mortgage Program that is available to both first-time and repeat homebuyers. It replaced the former Home Again program in DSHA’s April 2026 rebrand. Open Door offers below-market interest rates and can be combined with down payment assistance of 3%-4% of the loan amount through First State Home Loan or Keys4You. Smart Start is also available with no DPA at the lowest rate.
The Delaware State Housing Authority (DSHA) offers two primary mortgage programs under the Delaware Mortgage Program: Welcome Home for first-time buyers, and Open Door for a broader range of buyers. Open Door is specifically designed for buyers who don’t qualify for Welcome Home – either because they’ve owned a home in the past three years, or because their qualifying income exceeds the Welcome Home limits. Open Door carries the same 30-year fixed-rate structure with DSHA-set rates and can be layered with the same types of down payment assistance.
DSHA does not lend money directly. You apply through an approved lender – the John Thomas Team in Newark, Delaware. You can learn more about the full Delaware Mortgage Program at destatehousing.com.
What Replaced DSHA Home Again? The April 2026 Rebrand Explained.
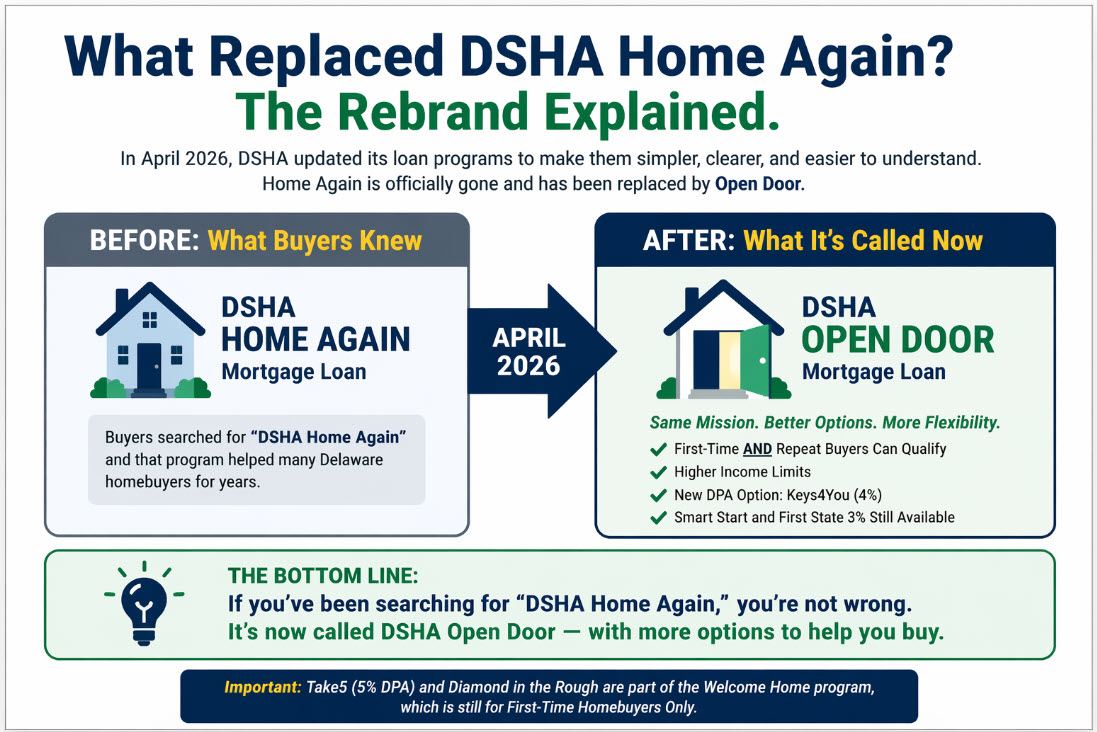
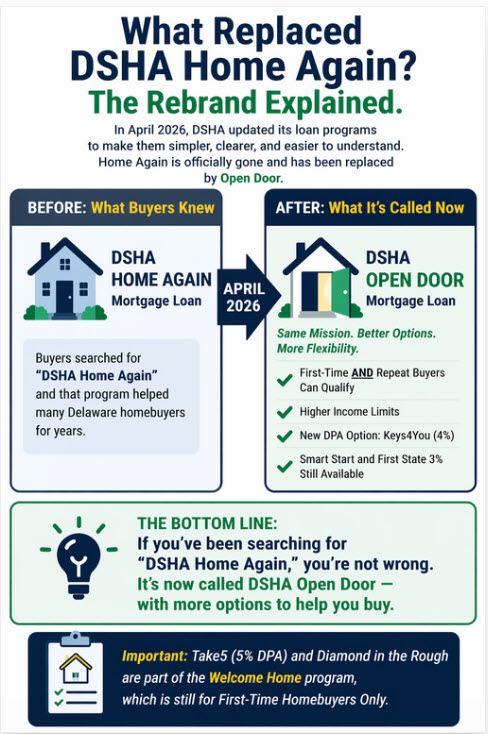
If you’ve been searching for the DSHA Home Again loan and found this page – here’s what happened. DSHA’s April 2026 Delaware Mortgage Program rebrand was a single product update that included multiple changes at once, and outdated sites often confuse the timeline. Here’s what actually happened:
- Home Again was renamed Open Door. The eligibility, income limits, and program structure are essentially the same – only the program name changed.
- The 4% DPA was branded as Keys4You and opened to both Welcome Home AND Open Door. DSHA had reintroduced this 4% DPA option in 2025 with no official product name – and at that point it was only available with Home Again. The April 2026 rebrand gave it the Keys4You name and made it the largest DPA available under Open Door (and the second-largest under Welcome Home, after Take5).
- A new 5% DPA option called Take5 was launched. Take5 is exclusive to Welcome Home and is now the largest non-renovation DPA available in Delaware.
- The “Kiss Your Landlord Goodbye” campaign and kissyourlandlordgoodbye.com were retired. All single-family mortgage program information moved to destatehousing.com under the new Delaware Mortgage Program brand.
Per DSHA Director Matthew Heckles’ announcement: “The launch of the Delaware Mortgage Program replaces the longtime homeownership campaign and website, ‘Kiss Your Landlord Goodbye.’ All single-family mortgage lending information will now live under the DSHA brand and website, destatehousing.com.” The rebrand was a single April 2026 event – there is no separate prior rebrand.
Any website still referring to “DSHA Home Again” as if it were a current program – or linking to the old kissyourlandlordgoodbye.com URL – is working from outdated information. We keep our Home Again legacy page live for buyers who researched the program under the old name, but the current program is Open Door.
What Are the DSHA Open Door Eligibility Requirements?
Open Door eligibility requirements: Minimum 620 credit score. Open to first-time and repeat buyers. Qualifying income (on the loan application/1003) at or below Open Door county limits. Must purchase a primary residence in Delaware. Must use a DSHA-approved lender. Must qualify for an FHA, VA, USDA, or Conventional loan. Scores between 620-659 require HUD-approved housing counseling before closing.
- Credit score: Minimum 620 for all borrowers. Scores 620-659 require completion of a HUD-approved housing counseling course (~8 hours, ~$125 fee) before closing. Minimum 660 for manufactured homes.
- First-time buyer status: Not required. Open Door is available to both first-time and repeat homebuyers.
- Primary residence: Property must be your primary residence in Delaware. Investment properties and second homes do not qualify.
- Income limits: Qualifying income on the loan application (1003) must be at or below Open Door county limits (see income table below). As of April 15, 2025, only the income of borrowers on the Note and/or Mortgage counts – income from non-borrowing household members is no longer counted toward qualifying.
- Location: Property must be located in Delaware. Available in all three counties: New Castle, Kent, and Sussex.
- Approved lender: Must apply through a DSHA-approved lender. The John Thomas Team is DSHA-approved, in Newark, Delaware.
- Loan type: Must qualify for a FHA loan paired with DSHA Open Door, VA loan paired with DSHA Open Door, USDA loan in Delaware, or Conventional loan in Delaware.
- Debt-to-income ratio: Standard DTI guidelines apply based on your chosen loan type – typically up to 45%-50% back-end DTI with compensating factors. See our guide to understanding your debt-to-income ratio.
What this means for you: You don’t need to be a first-time buyer and you don’t need perfect credit. If your qualifying income is within the Open Door limits and you’re buying a primary residence in Delaware, you likely have a path to a DSHA loan. Call us at 302-703-0727 and we’ll confirm your eligibility in minutes – before you start house shopping.
What Are the DSHA Open Door Income Limits for 2026?
Open Door income limits, effective for reservations on or after June 8, 2026: New Castle County – $147,240 (1-2 persons) / $184,050 (3+ persons). Kent & Sussex Counties – $133,680 (1-2 persons) / $167,100 (3+ persons). These are higher than Welcome Home limits. Effective April 15, 2025: only qualifying income on the loan application (1003) counts – not all household members’ income. Household size still sets the limit tier.
Income limits are one of the most important factors in determining which DSHA program you qualify for. Open Door has significantly higher income limits than Welcome Home, making it accessible to many middle- and upper-middle-income Delaware households that would otherwise not qualify for any state-backed mortgage assistance.
| County | 1-2 Person Household | 3 or More Persons |
|---|---|---|
| New Castle County | $147,240 | $184,050 |
| Kent & Sussex Counties | $133,680 | $167,100 |
How DSHA counts income (effective April 15, 2025): DSHA changed how income is counted for Open Door. Before the change, all adult household members had to provide income documentation – including a non-borrowing spouse. Under the current rule, only the qualifying income on the loan application (Form 1003) counts. Income from non-borrowing household members is no longer counted. If you have overtime pay, rental income, or a second job that you’re not using on the application, it doesn’t count either. Household size still determines which income limit tier applies.
Homes in DSHA-designated targeted census tracts have income limits that are roughly 20% higher than the figures above. Call us at 302-703-0727 to check whether a specific property falls in a targeted area.
What this means for you: As of April 2025, only the income you use on your loan application counts toward the Open Door limit. A non-borrowing spouse’s income, unused overtime, or other income sources not on the 1003 are excluded. This is a significant change – many buyers who assumed they were over the limit may now qualify. Call 302-703-0727 and we’ll calculate it correctly.
Open Door vs. Welcome Home: What’s the Difference?
| Feature | Welcome Home | Open Door |
|---|---|---|
| Who qualifies | First-time buyers only (no ownership in past 3 years) | First-time AND repeat buyers |
| Income limits (New Castle, 1-2 persons) | $122,700 | $147,240 |
| Income limits (New Castle, 3+ persons) | $141,105 | $184,050 |
| Income limits (Kent/Sussex, 1-2 persons) | $111,400 | $133,680 |
| Income limits (Kent/Sussex, 3+ persons) | $128,110 | $167,100 |
| DPA options | Smart Start / First State 3% / Keys4You 4% / Take5 5% / Diamond in the Rough 5% | Smart Start / First State 3% / Keys4You 4% |
| Max DPA | 5% of loan amount | 4% of loan amount |
| Government rate, Smart Start (Sep 12, 2026) | 5.375% | 6.875% |
| Government rate, First State 3% (Sep 12, 2026) | 5.625% | 7.625% |
| Government rate, Keys4You 4% (Sep 12, 2026) | 5.875% | 7.750% |
| Conventional rate, Smart Start (Sep 12, 2026) | 5.875% | 7.250% |
| Renovation loan option | Diamond in the Rough (FHA 203k + 5% DPA) | Not available |
| Take5 5% DPA | Yes – see Take5 program details | No – Welcome Home only |
| Best for | First-time buyers within income limits | Repeat buyers or higher-income households |
The most common scenario where Open Door comes into play: a dual-income couple in New Castle County where the qualifying income on the application is $130,000. That exceeds the Welcome Home limit of $122,700 (1-2 persons) but is well within Open Door’s $147,240 limit. Open Door gets them into the program. If neither program fits due to income, a standard FHA loan or Conventional loan without DSHA is the path forward.
Who Is DSHA Open Door Best For?
| Open Door Is a Strong Fit For | Open Door Is NOT the Right Program For |
|---|---|
| Repeat buyers in Delaware who have owned a home in the past 3 years | Real estate investors (primary residence only) |
| Buyers whose qualifying income exceeds Welcome Home limits | Buyers purchasing a second home or vacation property |
| Dual-income households earning up to $147,240 (NCC) / $133,680 (K&S) for 1-2 persons | Buyers with qualifying income above Open Door limits |
| Buyers who need 3%-4% down payment assistance (First State or Keys4You) | Buyers with credit scores below 620 |
| First-time buyers whose income is over the Welcome Home threshold | Buyers needing a renovation loan (Welcome Home + Diamond in the Rough only) |
| Veterans and active duty using a VA loan who need closing cost assistance | Buyers who qualify for Welcome Home – Welcome Home has better rates |
DSHA Open Door: Pros and Cons
| Pros | Cons |
|---|---|
| Higher income limits than Welcome Home – more buyers qualify | Interest rates are higher than Welcome Home rates |
| Available to repeat buyers – no first-time buyer requirement | Maximum DPA is 4% (Keys4You) – less than Welcome Home’s 5% |
| Up to 4% DPA through Keys4You – meaningful assistance for repeat buyers | DPA is a deferred second mortgage, not a grant – must be repaid upon sale or refi |
| 30-year fixed rate – payment stability for the life of the loan | No renovation loan option (Diamond in the Rough is Welcome Home only) |
| Works with FHA, VA, USDA, and Conventional loan types | Must use a DSHA-approved lender – not available at every bank |
| April 2025 rule change: only qualifying income on 1003 counts | Take5 (5%) is not available under Open Door – Welcome Home only |
What Down Payment Assistance Can I Get with DSHA Open Door?
Open Door can be paired with three DPA options, all structured as zero-interest deferred second mortgages with no monthly payments. The balance is due when you sell, refinance, transfer title, or no longer use the home as your primary residence.
First State Home Loan (3% DPA)
The First State Home Loan provides 3% of your final loan amount as a zero-interest deferred second mortgage. No monthly payments required. Available under both Welcome Home and Open Door. This is the most widely-used DSHA DPA product in Delaware – straightforward, reliable, and pairs with FHA, VA, USDA, or Conventional first mortgages.
Example: $300,000 purchase ? ~$291,000 loan ? First State Home Loan = ~$8,730 in DPA.
Read the complete First State Home Loan DPA program details ?
Keys4You Home Loan (4% DPA) – Open Door Maximum
Keys4You provides a zero-interest deferred second mortgage equal to 4% of your first mortgage loan amount – available under both Open Door and Welcome Home. No monthly payments, deferred until sale, refinance, or no longer primary residence. DSHA reintroduced the 4% DPA option in 2025 (then exclusive to Home Again with no official product name); the April 2026 Delaware Mortgage Program rebrand gave it the Keys4You brand and opened it to Welcome Home as well. For repeat buyers using Open Door, Keys4You provides the maximum DPA available under that program.
Example: $300,000 purchase ? ~$291,000 loan ? Keys4You 4% = ~$11,640 in DPA.
Get the full Keys4You Home Loan program breakdown ?
What About 5% DPA? Take5 and Diamond in the Rough
If you need 5% DPA, both Take5 and Diamond in the Rough are available – but only under the Welcome Home program, not Open Door. Take5 is a zero-interest deferred second mortgage equal to 5% of the loan amount (no renovation required) that DSHA launched as part of the April 2026 Delaware Mortgage Program rebrand. Diamond in the Rough is 5% DPA paired with an FHA 203k renovation loan. If you qualify for Welcome Home and need maximum DPA, those are the stronger options. If your income exceeds Welcome Home limits and you need Open Door, the maximum DPA available is 4% through Keys4You.
See Welcome Home eligibility, income limits, and all five DPA options ?
| DPA Program | Amount | Available Under | Interest | Monthly Payment |
|---|---|---|---|---|
| Smart Start | None | Open Door + Welcome Home | N/A | None |
| First State Home Loan | 3% of loan | Open Door + Welcome Home | 0% | None |
| Keys4You Home Loan | 4% of loan | Open Door + Welcome Home | 0% | None |
| Take5 Home Loan | 5% of loan | Welcome Home ONLY | 0% | None |
| Diamond in the Rough | 5% of loan | Welcome Home ONLY | 0% | None |
Real Buyer Example: Open Door in Action
Scenario: A married couple in New Castle County. The husband earns $135,000 and is the sole borrower on the loan. They owned a home 4 years ago and sold it – making them repeat buyers. Under the updated DSHA income rule (effective April 15, 2025), only the husband’s qualifying income on the application counts – $135,000.
Solution: Open Door. The husband’s qualifying income of $135,000 is within Open Door’s $147,240 limit for a 1-2 person household (household size still sets the limit tier). They purchase a $325,000 home using a DSHA Open Door FHA loan and pair it with Keys4You 4% DPA – the maximum available under Open Door.
The numbers: Loan amount ~$314,000 ? Keys4You at 4% = ~$12,560 in down payment assistance. FHA requires 3.5% down ($11,375). The Keys4You DPA covers the entire FHA down payment and a portion of closing costs. Their estimated cash to close dropped to approximately $3,000-$6,000 instead of $20,000+.
Result: They purchased sooner than expected – instead of spending two more years saving. The Keys4You DPA is a deferred zero-interest second mortgage they’ll repay when they eventually sell or refinance. If they had qualified for Welcome Home, Take5 at 5% would have given them even more assistance – but at $135,000 income, Open Door with Keys4You was their path.
What this means for you: Under the updated income calculation rule, many buyers who previously thought they were over the Open Door limit may now qualify – especially if a non-borrowing spouse’s income or unused income sources were being incorrectly counted. You won’t get Take5’s 5%, but Keys4You at 4% can still make a meaningful difference in your cash to close. Call us and we’ll run the numbers before you assume you don’t qualify.
What Are the Current DSHA Open Door Interest Rates?
DSHA sets rates for the Delaware Mortgage Program and updates them periodically. Open Door rates are higher than Welcome Home rates – this is standard because Open Door serves a broader buyer pool. The rate is the same regardless of which DSHA-approved lender you use. Read the table down a column and the second pattern appears too: within Open Door, every step up in down payment assistance costs you rate. That spread is the price of the assistance, financed over the life of the loan rather than paid at closing.
| Open Door DPA tier | FHA / VA / RD | Conventional |
|---|---|---|
| Smart Start (no DPA) | 6.875% | 7.250% |
| First State Home Loan (3% DPA) | 7.625% | 8.000% |
| Keys4You Home Loan (4% DPA) | 7.750% | 8.125% |
Rates shown are the DSHA rate sheet dated September 12, 2026. They are not a quote, not an APR, and not a rate lock, and DSHA can change them on any business day. Current rates are published at destatehousing.com – call 302-703-0727 for today’s rate before you decide based on these figures. APR will be higher than the interest rate and varies by loan type, amount, and fees; ask for your specific APR disclosure. Equal Housing Lender.
What Property Types Are Eligible for DSHA Open Door?
- Single-family residences – most common property type
- Townhomes and rowhomes
- 2-4 unit properties – FHA, VA, or USDA only (buyer must occupy one unit)
- Warrantable condos
- Manufactured homes – minimum 660 credit score, FHA loan only, double-wide or larger (single-wides do not qualify per DSHA program guidelines)
Purchase price limits (non-targeted areas, effective June 8, 2026): New Castle County $659,385 | Kent & Sussex Counties $566,354. Targeted area properties have higher purchase price limits.
What Are the Closing Costs with DSHA Open Door?
Down payment assistance covers part of your upfront costs – but you also need to plan for closing costs. In Delaware, closing costs typically run 2%-5% of the purchase price, which on a $300,000 home means $6,000-$15,000 in fees covering title, attorney, lender fees, prepaid taxes, and insurance.
Delaware transfer tax is 4% total – typically split 2% buyer / 2% seller under a standard Delaware Association of Realtors contract. If you’re buying from a builder, the builder’s contract may require you to pay the full 4% – a significant difference worth clarifying before you sign. You can learn more about how seller-paid closing costs work in Delaware and how to negotiate them into your offer.
What this means for you: Your DPA – especially Keys4You at 4% through Open Door – can cover most or all of your down payment and a meaningful portion of closing costs. Combined with seller concessions negotiated into your offer, many Open Door buyers close with significantly less cash out of pocket than they expected. We’ll give you an exact estimate before you make an offer.
The Open Door Income Calculation Rule (Updated April 2025)
This is one of the most important updates to understand about the Open Door program. Effective April 15, 2025, DSHA changed how income is calculated for both Open Door and Welcome Home. The old rule – which required all household members’ income to be counted regardless of whether they were on the loan – no longer applies. Note that this April 2025 rule change took effect a year before the broader April 2026 Delaware Mortgage Program rebrand – they were two separate program updates.
For Open Door, DSHA now counts only the qualifying income on the loan application (Form 1003). This means only the income you actually use to qualify for the mortgage is counted against the income limit. If you have overtime pay, rental income, or a second job that you’re not using on the application, it doesn’t count. If a spouse is not on the loan and their income is not on the 1003, it is not counted.
Example: A couple where only the husband is on the loan. He earns a $120,000 base salary but also receives $15,000 in overtime he chooses not to include on the application. Only the $120,000 base salary is counted toward the Open Door income limit – the overtime and the wife’s income are excluded.
What this means for you: The income counting rule changed significantly in April 2025. Many buyers who previously thought they were over the Open Door income limit may now qualify under the new calculation. Call us at 302-703-0727 – we’ll run the correct income calculation for you before you assume you don’t qualify.
Common Mistakes Delaware Buyers Make with Open Door
After 20+ years originating DSHA loans in Delaware, these are the mistakes I see most often – and all of them are avoidable with the right guidance upfront.
- Misunderstanding the income calculation rule. As of April 15, 2025, only the qualifying income on the loan application (1003) counts toward the Open Door income limit – not all household members’ income. A non-borrowing spouse’s income is excluded. Some buyers still assume the old “all household income” rule applies and incorrectly disqualify themselves. Call us and we’ll run the correct calculation.
- Assuming first-time buyer status is required. Many repeat buyers don’t even look at DSHA programs because they think they’re only for first-time buyers. Open Door has no first-time buyer requirement at all.
- Not comparing Welcome Home first. If you could qualify for Welcome Home, the rates are lower and you have access to Take5 at 5% DPA. We always check both programs and show you the real numbers side by side before you choose.
- Choosing the wrong DPA option. First State (3%) and Keys4You (4%) are the two DPA options under Open Door – each comes with a slightly different rate. The right choice depends on your loan amount, how much cash you have, and your long-term plans. This is exactly what the pre-approval consultation is for.
- Not knowing about the transfer tax. Delaware’s 4% transfer tax – and the builder contract exception – catches buyers off guard. Know this before you go under contract, especially on new construction.
- Waiting too long to lock the rate. Open Door rates are set by DSHA and can change when new bond funding is issued. Rate locks typically run 60-90 days. Waiting until late in your search to get pre-approved leaves your rate exposed.
- Trusting outdated information online. National websites still reference Home Again, Kiss Your Landlord Goodbye, and the old kissyourlandlordgoodbye.com URL – all retired in DSHA’s April 2026 Delaware Mortgage Program rebrand. Always verify with a DSHA-approved lender who is actively originating these loans.
How Do I Apply for the DSHA Open Door Loan?
- Apply online or call us – Submit your application at applywithjohnthomasteam.com or call 302-703-0727. We’ll pull your credit and collect the qualifying income documents for your loan application.
- Confirm Open Door eligibility – We verify your qualifying income against Open Door county limits and confirm which DPA option (Smart Start, First State 3%, or Keys4You 4%) makes the most sense for your loan amount and purchase goal.
- Housing counseling if needed – Required for credit scores 620-659. We’ll connect you with a HUD-approved agency in Delaware.
- Pre-approval issued – Your pre-approval letter will reflect your Open Door program, rate, and DPA amount so your real estate agent can submit competitive offers.
- Go under contract – Your agent should know you’re using a DSHA Open Door loan so the offer and timeline are structured appropriately.
- Underwriting and closing – Open Door loans close like any standard mortgage. Settlement in Delaware is handled by a licensed attorney or title company.
Rate locks on Open Door loans typically run 60-90 days. We manage the timing carefully to protect your rate from the day you go under contract through closing.
Using DSHA Open Door in New Castle, Kent, and Sussex Counties
Open Door is available statewide, but the buyer experience – and what your money gets you – varies significantly by county. Here’s what buyers should know across all three.
New Castle County
New Castle is Delaware’s most competitive market. Newark, Wilmington, Bear, and Pike Creek see consistent buyer demand, and homes in desirable school districts move quickly. Open Door’s income limits in New Castle – $147,240 (1-2 persons) / $184,050 (3+ persons) – cover a wide range of buyers here, including dual-income couples, teachers, nurses, state employees, and tradespeople. The purchase price limit of $659,385 covers most of the active market. With Keys4You at 4% on a $350,000 home, an Open Door buyer can access roughly $13,400 in DPA – enough to cover most or all of the FHA down payment and reduce cash to close significantly. Our office is in Newark, so we work with New Castle buyers every day.
Kent County
Dover is Kent County’s primary market, with a buyer pool that includes Dover Air Force Base military personnel and families, state government employees, and buyers priced out of New Castle. Open Door’s Kent County income limits – $133,680 (1-2 persons) / $167,100 (3+ persons) – are well-suited to this buyer profile. VA loans work with Open Door, making the program particularly relevant for military buyers who need help with closing costs rather than a down payment. The purchase price limit of $566,354 covers the vast majority of Dover-area home prices.
Sussex County
Sussex County includes both the beach communities near Rehoboth and Lewes and more affordable inland areas like Georgetown, Milford, and Seaford. Sussex shares Kent’s income limits – $133,680 (1-2 persons) / $167,100 (3+ persons). Buyers in inland Sussex often find that Open Door – especially with Keys4You 4% DPA – dramatically reduces their cash-to-close on more affordable homes, sometimes to $2,000-$5,000 out of pocket. Beach-area buyers should verify that their target property falls within the $566,354 purchase price limit.
What this means for you: Whether you’re buying in Newark, Dover, or Georgetown, we can run your Open Door eligibility in minutes. Call 302-703-0727 or schedule a free consultation – we work with buyers across all three counties and know the local market dynamics well.
John Thomas, NMLS #38783 | NMLS #38783 DSHA Approved Lender Author
Branch Manager & Division Vice President, John Thomas Team with AnnieMac Home Mortgage
John Thomas is a DSHA-approved mortgage loan officer with the John Thomas Team in Newark, Delaware. With over 20 years of experience and 3,000+ Delaware buyers helped, John has been originating Open Door and Home Again loans since the programs launched. He specializes in DSHA programs, FHA, VA, USDA, and first-time homebuyer loans across all three Delaware counties, and is the author of Your Guide to Buying Your First Home in Delaware.
As an active DSHA-approved lender who updated his programs the day the April 2026 Delaware Mortgage Program rebrand was announced, John provides current, accurate Open Door guidance that national aggregate sites – still publishing outdated Home Again information – simply cannot match.
Stats: 20+ Years in Delaware Mortgages | 3,000+ Buyers Helped | 1,000+ DSHA/DPA Loans | Licensed in DE & MD | CMP Certified Mortgage Planner
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com | Schedule Appointment | About John Thomas | YouTube Channel | See John Thomas Team on Google
Related Delaware Mortgage Guides
Open Door is one piece of the broader Delaware down payment assistance landscape. For deeper reading on the programs and concepts referenced throughout this page:
- DSHA Loan Programs in Delaware – Complete 2026 Guide – Full breakdown of every DSHA program (Welcome Home, Open Door, First State, Keys4You, Take5, Diamond in the Rough) and how they compare.
- DSHA Welcome Home Loan Program – DSHA’s flagship first-time buyer program with five DPA options including Take5 (5%) and Diamond in the Rough (5%). Better rates than Open Door for buyers who qualify.
- DSHA Home Again (Legacy Reference) – Home Again was renamed to Open Door in DSHA’s April 2026 Delaware Mortgage Program rebrand. We keep this page live for buyers who researched the program under the old name.
- DSHA First State Home Loan DPA – The 3% DPA option available under both Welcome Home and Open Door. Most widely used DPA in Delaware.
- DSHA Keys4You Home Loan (4% DPA) – Open Door’s maximum DPA option. Available under both Welcome Home and Open Door.
- DSHA Take5 Home Loan (5% DPA) – The 5% DPA available under Welcome Home only. Not available with Open Door.
- DSHA Diamond in the Rough – FHA 203(k) Limited renovation loan paired with 5% DPA for Welcome Home buyers purchasing fixer-uppers.
- Delaware Down Payment Assistance Programs – Every active DPA option in Delaware including DSHA programs and county/city programs in all three counties.
- Delaware First Time Home Buyers Guide 2026 – The pillar first-time buyer resource, including the book, seminar schedule, credit strategy, and step-by-step purchase process.
- Delaware FHA Loans – The most popular loan type paired with Open Door. 3.5% down, 580+ credit.
- Delaware Mortgage Credit Certificate (MCC) program – the MCC was a federal tax credit for Delaware first-time buyers that ended August 15, 2025 (separately from the April 2026 Delaware Mortgage Program rebrand). Many national sites, mortgage blogs, and even accountants still reference it as active. Our MCC page explains how the program worked, when it ended, and what DSHA replaced it with.
FAQ: DSHA Open Door Loan Program Delaware
What is the DSHA Open Door loan program in Delaware?
The DSHA Open Door loan program is part of DSHA’s Delaware Mortgage Program. It is a 30-year fixed-rate mortgage available to both first-time and repeat homebuyers in Delaware who meet income limits. Open Door replaced the former Home Again program when DSHA rebranded its single-family mortgage products as the Delaware Mortgage Program in April 2026. It can be combined with down payment assistance including Smart Start (no DPA), First State Home Loan (3%), or Keys4You (4%). Take5 (5%) and Diamond in the Rough (5%) are available under Welcome Home only.
What replaced DSHA Home Again?
DSHA Home Again was renamed to Open Door in DSHA’s April 2026 Delaware Mortgage Program rebrand. That single rebrand event also branded the existing 4% DPA as Keys4You and opened it to both Welcome Home and Open Door, launched Take5 (5% DPA, Welcome Home only), and retired the longtime ‘Kiss Your Landlord Goodbye’ campaign. Open Door serves the same purpose as Home Again did – helping first-time and repeat buyers who exceed Welcome Home income limits or are not first-time buyers.
Who qualifies for the DSHA Open Door program?
Open Door is available to any buyer purchasing a primary residence in Delaware who has a minimum 620 credit score and qualifying income at or below the Open Door county limits. Unlike Welcome Home, Open Door does not require first-time buyer status. It is commonly used by repeat buyers, buyers who exceed Welcome Home income limits, and higher-income dual-income households. You must apply through a DSHA-approved lender.
What are the DSHA Open Door income limits?
Open Door income limits for 2026 are: New Castle County – $147,240 for 1-2 person households, $184,050 for 3 or more persons. Kent and Sussex Counties – $133,680 for 1-2 person households, $167,100 for 3 or more persons. Effective April 15, 2025: only qualifying income on the loan application (1003) counts – not all household members’ income. Household size still sets the limit tier. Targeted area properties have higher limits.
What down payment assistance is available with DSHA Open Door?
Open Door can be paired with three DPA options: Smart Start (no assistance, lowest rate), First State Home Loan (3% of loan amount, zero interest, deferred), and Keys4You Home Loan (4% of loan amount, zero interest, deferred). All DPA options are second mortgages with no monthly payments, due upon sale, refinance, or when the home is no longer your primary residence. Take5 (5%) and Diamond in the Rough (5%) are available under Welcome Home only – Open Door’s maximum DPA is 4% via Keys4You.
What are the current DSHA Open Door interest rates?
Open Door rates on the DSHA rate sheet dated September 12, 2026: FHA/VA/RD Smart Start 6.875%, First State Home Loan 7.625%, Keys4You 7.750%; Conventional Smart Start 7.250%, First State Home Loan 8.000%, Keys4You 8.125%. These are not a quote, not an APR, and not a rate lock – DSHA can change them on any business day. Call 302-703-0727 for today’s rate. Rates are set by DSHA and published at destatehousing.com.
What is the difference between DSHA Open Door and Welcome Home?
Welcome Home is for first-time buyers only (no primary residence ownership in past 3 years) and has lower income limits ($122,700/$141,105 NCC, $111,400/$128,110 K&S). Open Door is for both first-time and repeat buyers and has higher income limits ($147,240/$184,050 NCC, $133,680/$167,100 K&S). Open Door offers Smart Start, First State 3%, and Keys4You 4% – max DPA is 4%. Welcome Home offers those same three plus Take5 (5%) and Diamond in the Rough (5%). If you exceed Welcome Home income limits or are a repeat buyer, Open Door is your path.
What property types are eligible for DSHA Open Door?
Eligible property types include single-family residences, townhomes and rowhomes, 2-4 unit properties (FHA, VA, or USDA only), warrantable condos, and manufactured homes (660+ credit score, FHA only, double-wide or larger). The property must be in Delaware and used as a primary residence. Purchase price limits: $659,385 in New Castle County and $566,354 in Kent and Sussex Counties.
Can I combine Open Door with the Mortgage Credit Certificate?
No – the Delaware Mortgage Credit Certificate (MCC) program ended August 15, 2025 and is no longer accepting applications. The MCC ended separately from the April 2026 Delaware Mortgage Program rebrand. Many national sites, accountants, and mortgage blogs still reference the MCC as active, which is why so many buyers still ask about it. The MCC tax credit is no longer available, but our Delaware Mortgage Credit Certificate page explains how the program worked, when it ended, and what DSHA replaced it with.
Ready to Apply for DSHA Open Door?
We’ll review your income, credit, county, and purchase goal – and tell you exactly whether Open Door fits your situation, which DPA option gives you the most assistance, and what you’ll need at closing. No pressure, no obligation. Just straightforward answers from a DSHA-approved lender with 20+ years of Delaware experience.
Last Updated: September 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
John R. Thomas, NMLS #38783 | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net | Equal Housing Lender
Copyright John R. Thomas, All Rights Reserved
