Dover Delaware Mortgage Loans: Local Lending for Kent County Homebuyers
Dover Delaware mortgage loans include FHA, VA, USDA, conventional and DSHA financing for Kent County buyers. Homes inside the Dover city limits can add the City’s First Start help of up to $20,000, and Dover sits in no DSHA targeted area, so Kent’s standard income limits apply. Current as of October 2026.
Finding a house you like in Dover is the easy part. Working out which loan fits, whether the address sits inside the city line, and how much help you can stack is where most buyers get stuck. I’m John Thomas, NMLS #38783, and my goal on this page is to give you the full picture of Dover Delaware mortgage loans in one place: the four main loan types, the DSHA programs, the help only City of Dover buyers get, and what Dover Air Force Base families should look at first. If you mainly want down payment help, our Delaware down payment assistance programs guide covers every program by county.
Buying in Dover or Anywhere in Kent County?
Send us the address or the area you’re shopping. We’ll check whether it sits inside the Dover city limits, which DSHA limits apply and whether USDA is on the table, then compare the loans side by side.
Table of Contents
What Mortgage Loan Programs Can Dover Buyers Use?
Dover buyers can use FHA (3.5% down with a 580 score), conventional (as little as 3% down), VA (0% down for eligible service members and veterans) and USDA (0% down, but only outside the City of Dover in eligible rural areas). Any of these can pair with DSHA assistance when the buyer meets DSHA’s limits, as of October 2026.
FHA is where a lot of Dover first-time buyers start. HUD allows 3.5% down with a 580 credit score, or 10% down with a score from 500 to 579 (HUD FHA loan rules). Lenders set their own minimum score on top of that, so a 580 is HUD’s floor, not a promise. The 2026 FHA limit for a one-unit home in Kent County is $541,287 (HUD FHA limit lookup), well above what most Dover homes sell for; our Delaware FHA loan limits 2026 page has every county and unit count. FHA also finances a two- to four-unit home you live in, though City of Dover First Start does not assist multi-unit properties. More on the program: FHA loans for Dover homebuyers.
Conventional loans work well when your credit is strong. Eligible first-time buyers can put down as little as 3% through Freddie Mac Home Possible or Fannie Mae HomeReady, and the mortgage insurance can come off once you build enough equity. With 20% down, there’s no mortgage insurance at all. See conventional loans for Dover buyers.
VA loans matter more in Dover than almost anywhere else in Delaware because of Dover Air Force Base. There’s a full section on that below, and the program page is VA loans for Dover veterans.
USDA is the one that depends most on the address. The City of Dover itself is generally too large for USDA’s rural map, but plenty of Kent County outside the city can qualify. Check a specific address on the USDA property eligibility map before you count on it, and read USDA loans near Dover, Delaware for income rules.
| Loan | Minimum down payment | Credit rule | Where it fits for Dover buyers |
|---|---|---|---|
| FHA | 3.5% (10% with a 500-579 score) | HUD floor 580 for 3.5% down; lenders set their own minimums | First-time buyers with modest savings or thinner credit |
| Conventional | 3% for eligible first-time buyers | Set by the lender and the underwriting system | Stronger credit; mortgage insurance can be removed later |
| VA | 0% for eligible borrowers | Set by the lender; Certificate of Eligibility required | Dover Air Force Base service members, veterans, eligible surviving spouses |
| USDA | 0% | Set by the lender; household income limits apply | Eligible rural Kent County addresses outside the City of Dover |
| DSHA Welcome Home / Open Door | Pairs with 3% to 5% DSHA assistance | DSHA minimum 620 | Buyers within Kent County DSHA income and price limits |
What Homebuyer Help Is Only Available Inside the Dover City Limits?
Three City of Dover programs apply only to homes inside the city limits, as of October 2026: First Start, up to $20,000 toward settlement costs for eligible first-time buyers; a City transfer tax exemption for qualifying first-time buyers; and a five-year City property tax phase-in inside the Downtown Development District. A Dover mailing address alone does not qualify.
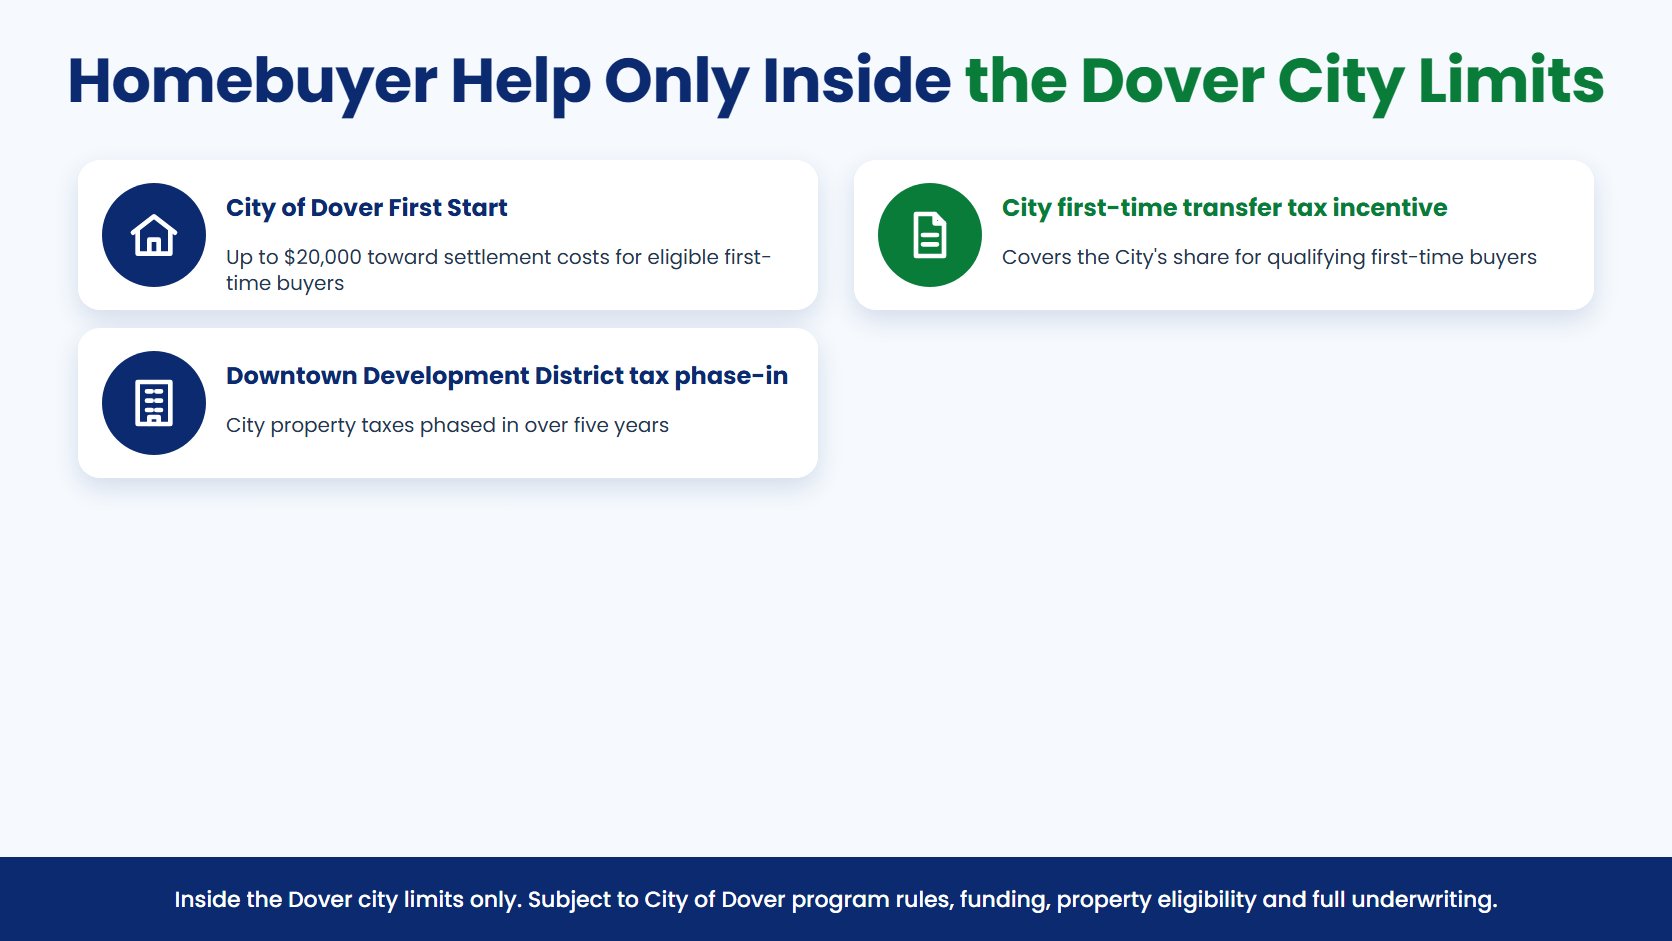
City of Dover First Start. The City’s program pays up to $20,000 of settlement costs for first-time buyers whose household income falls within the City’s 60% to 80% of area median income range, with a 620 credit score and at least $1,000 of their own money. It’s forgiven after ten years in the home, and it can stack with DSHA assistance: the City records in second lien position on its own, or third behind DSHA’s second mortgage. The City refunded the program in September 2026 after it ran out of money over the summer, and money goes first-come, first-served. When you use both, the order on title is: first mortgage, then the DSHA second mortgage, then the City’s First Start lien in third. Every rule, the income table and the property types are on our City of Dover First Start program page, built from the City’s program guidelines.
City first-time home owner transfer tax incentive. The City of Dover lists a First Time Home Owner Tax Incentive on its transfer tax page. It covers the City’s share of the realty transfer tax for a qualifying first-time buyer anywhere inside the city limits who lives in the home. The City’s test is stricter than First Start’s: you must never have owned a principal residence anywhere, and you must move in within 90 days of the deed being recorded. It’s separate from the state’s own Delaware first-time home buyer transfer tax exemption, and a buyer can qualify for one, both or neither.
Downtown Development District tax phase-in. If the home sits inside Dover’s Downtown Development District and you live in it, the City phases in its own real estate taxes: 100% off in year one, 75% in year two, 50% in year three and 25% in year four. You apply to the City; your lender doesn’t file it for you.
All three stop at the city line. Homes with a Dover, DE 19901 or 19904 mailing address can sit in unincorporated Kent County, and so do Camden, Wyoming and much of the area around the base. I check the parcel against the City of Dover GIS map before anyone writes an offer that depends on City money.
How Do DSHA Programs Work With Dover Delaware Mortgage Loans?
As of October 2026, Dover buyers use DSHA’s Kent County non-targeted limits: $111,400 for a 1-2 person household and $128,110 for 3 or more on Welcome Home, and $133,680 and $167,100 on Open Door. No Dover address sits in a DSHA targeted area, so the higher targeted limits do not apply here.
DSHA’s two first mortgages are Welcome Home, for buyers who haven’t owned a home in the past three years (plus qualified veterans), and Open Door, for first-time and repeat buyers. Either one can come with a 0% deferred second mortgage: First State at 3% or Keys4You at 4%, and on Welcome Home only, Take5 at 5% or Diamond in the Rough at 5% with an FHA 203(k) Limited repair loan. The rules are in DSHA’s Delaware Mortgage Program Notice, effective June 8, 2026.
| Kent County (DSHA non-targeted) | 1-2 person household | 3+ person household |
|---|---|---|
| Welcome Home income limit | $111,400 | $128,110 |
| Open Door income limit | $133,680 | $167,100 |
| Purchase price limit (both programs) | $566,354 | |
Why don’t the targeted limits help a Dover buyer? DSHA lists one targeted census tract in Kent County, tract 0425.00, and the Census Bureau places that tract in Milford, not Dover. So when a Dover buyer reads about DSHA’s higher targeted-area limits or the targeted-area exception to the first-time rule, none of it applies to a Dover address. Use the non-targeted numbers above.
How DSHA counts income trips people up too. Welcome Home counts all income of everyone on the note and mortgage, overtime and bonus included. Open Door counts the qualifying income on the loan application. Household size, including people who aren’t on the loan, sets which column you use. That’s the opposite of First Start, which counts the whole household’s income. In my experience, a Dover couple who fits DSHA easily can still miss First Start because a working adult child living with them counts for the City and not for DSHA, so I run both tests before we pick a plan. DSHA requires a 620 credit score, and buyers at 659 or below complete homebuyer education first; our Dover Delaware first time home buyer seminar is a good place to start. The full program list is on our DSHA loan programs guide, with details on DSHA Welcome Home for Dover first-time buyers and DSHA Open Door for Dover repeat buyers.
How Do VA Loans Work for Dover Air Force Base Buyers?
Eligible Dover Air Force Base service members, veterans and surviving spouses can buy a primary residence with no down payment and no monthly mortgage insurance through a VA loan, as of October 2026. They need a Certificate of Eligibility and must meet lender credit and income standards; the funding fee is waived for veterans receiving VA disability compensation.
The VA funding fee and closing cost page lists who is exempt; everyone else pays a one-time fee that can be financed into the loan. A few things come up again and again with base buyers:
- Housing allowance (BAH) can generally count as income when it’s documented on your Leave and Earnings Statement.
- VA loans are for a home you’ll live in. If PCS orders are coming, tell us early, because timing changes how occupancy is handled.
- A past VA loan doesn’t rule out a new one. Remaining entitlement, or restored entitlement after a sale, can still be used.
- A lot of homes near the base sit outside the Dover city limits, so City programs may not apply, but VA works anywhere in Delaware.
You can request a Certificate of Eligibility through the VA eligibility page, or we can pull it for you. Our VA loan eligibility requirements page covers service rules, and if you have a military connection, I’d look at VA before any other program.
What Will Closing Cost a Dover Homebuyer?
Closing costs on a Dover purchase often run about 3% to 5% of the price, as of October 2026. The biggest line is usually the realty transfer tax under Title 30, chapter 54: 4% combined, split 2% buyer and 2% seller on a standard Delaware Association of Realtors contract, unless the contract shifts more to the buyer.
Read the builder contract before you sign. New construction contracts around Dover are written by the builder, and some of them put more than the usual 2% transfer tax on the buyer. On a $325,000 home, the difference between paying 2% and the full 4% is $6,500 at the closing table.
Beyond transfer tax, a Dover closing usually includes lender and title charges, the appraisal, a year of homeowners insurance and prepaid taxes for escrow. Delaware closings are conducted by a Delaware-licensed attorney, so a settlement attorney fee is part of the budget. Three things can shrink the cash you bring: DSHA assistance and First Start money applied at settlement, a seller credit written into the contract (see seller-paid closing costs), and the state and City first-time transfer tax breaks when you qualify.
| Hypothetical $325,000 Dover purchase, FHA | Estimate |
|---|---|
| FHA down payment (3.5%) | About $11,375 |
| Buyer’s 2% share of transfer tax (standard contract) | About $6,500 |
| Other closing costs and prepaids | Varies with the loan, title, insurance and closing date |
| DSHA Keys4You at 4% of the loan amount, if eligible | About $12,500 toward these costs |
| City of Dover First Start, if eligible and funded | Up to $20,000 of settlement costs |
What Are the Steps to Buying a Home in Dover With Down Payment Help?
A Dover purchase with assistance usually runs in six steps: get pre-approved with an approved lender, check the address against the Dover city limits and USDA map, finish homebuyer counseling if a program needs it, choose the loan and assistance, sign a contract so the lender can request City funds, then complete underwriting and close.
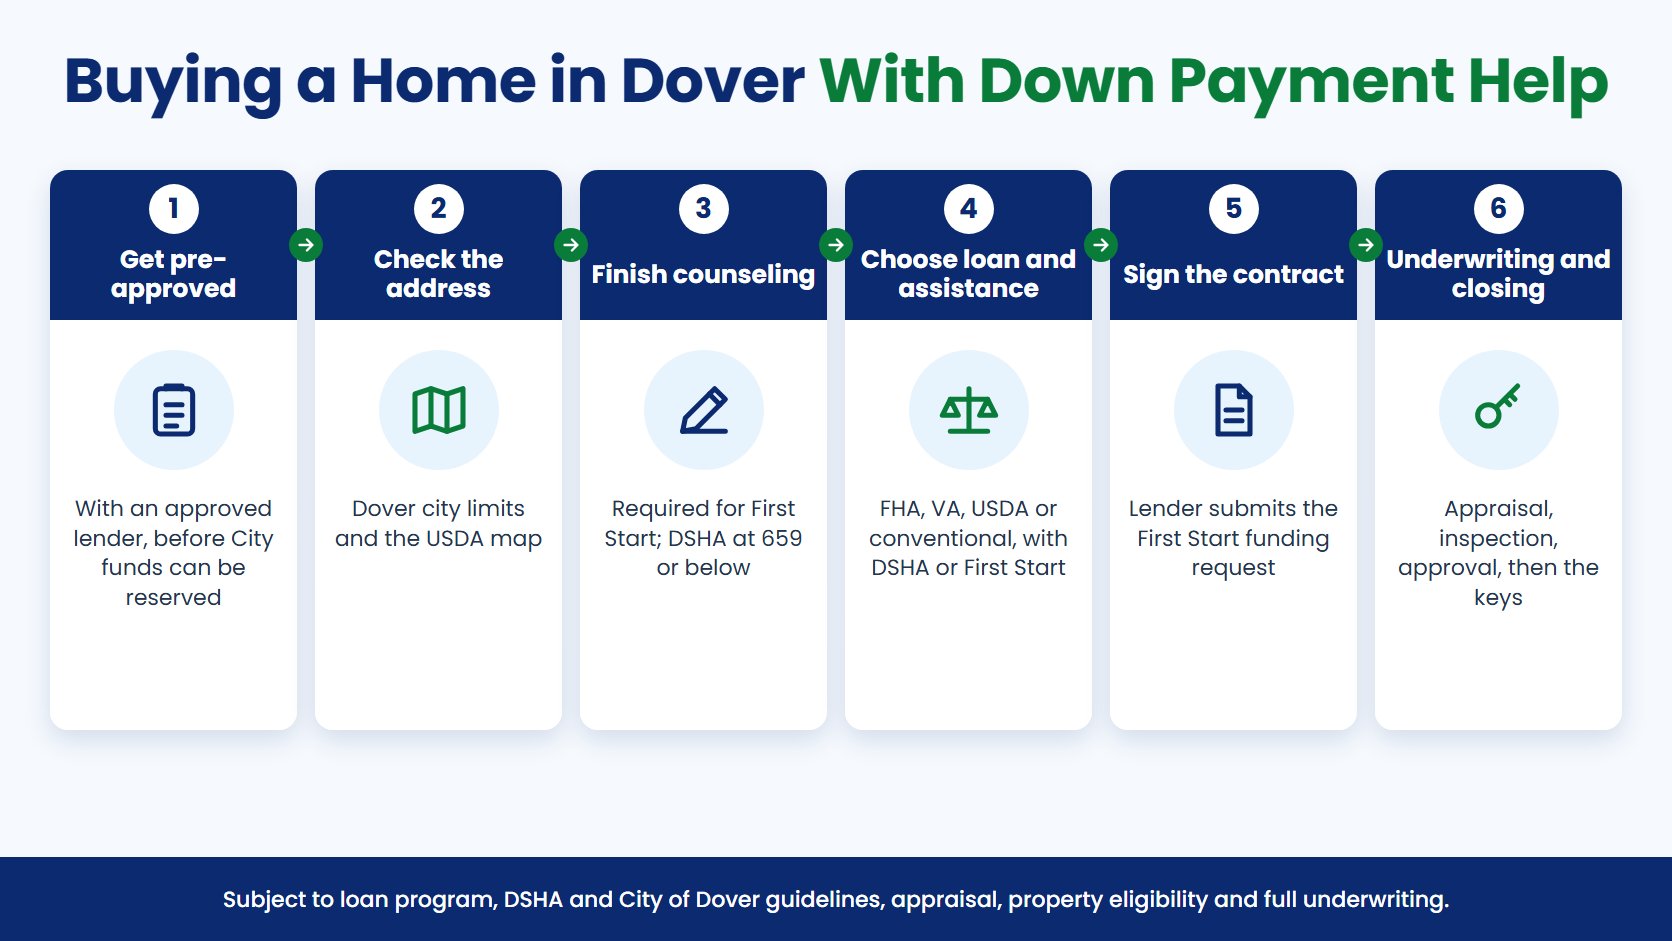
- Get pre-approved first. The City of Dover doesn’t reserve First Start money until you’re approved for a mortgage, and DSHA reservations come through the lender.
- Check the address. Inside the city limits opens First Start and the City tax breaks; outside it, check the USDA map.
- Finish counseling if you need it. First Start requires HUD-certified counseling before closing, and DSHA requires education at a 659 score or below.
- Choose the first mortgage and the assistance: FHA, VA, USDA or conventional, with DSHA, First Start or both.
- Sign the contract. For First Start, the lender then submits the funding request to the City for you.
- Appraisal, inspection and underwriting, then closing. First Start needs an inspection by an inspector licensed by the City of Dover on an existing home.
We start with a soft credit pull, so checking where you stand doesn’t touch your score.
When These Dover Loan Options Are Not a Good Fit
- First Start is usually not a fit if the home sits outside the Dover city limits, your household income is above the City’s 80% column, you hold more than $20,000 in cash or cash-equivalent assets, or you’ve owned a home in the past three years. DSHA assistance is the path in those cases.
- DSHA Welcome Home is not a fit if you owned a home in the last three years and aren’t a qualified veteran. Open Door still pairs with First State or Keys4You.
- USDA is generally not a fit inside the City of Dover. If the address isn’t on the USDA map, FHA or VA is the usual low-down route.
- FHA may cost more than conventional if your credit is strong. With less than 10% down, FHA mortgage insurance stays for the life of the loan, while conventional mortgage insurance can come off as you build equity.
- Down payment assistance is a second mortgage you repay when you sell or refinance. If you expect to move in a year or two, compare the payoff against simply waiting and saving.
Each of these depends on the full file. The quickest way to know is a side-by-side comparison of your own numbers, and that’s what a 30-minute call is for.
Our Dover and Kent County Service Area
The John Thomas Team lends throughout Delaware and Maryland from our office at 248 E Chestnut Hill Rd in Newark, DE 19713. Dover and the rest of Kent County are part of that regular service area, and the map below shows the full Delaware and Maryland coverage.
The John Thomas Team serves homebuyers throughout Delaware and Maryland. Office: 248 E Chestnut Hill Rd, Newark, DE 19713. Dover and all of Kent County are within our service area.
Around Dover we work with buyers in Camden, Wyoming, Magnolia, Felton and Hartly, and at the county’s north end in Smyrna; see Smyrna Delaware mortgage loans. To the south, Kent County’s one DSHA targeted tract is in Milford, covered on Milford Delaware mortgage loans. The loan programs on this page work in all of these towns; the City of Dover programs don’t. Manufactured homes are a real part of the Kent County market outside the city, and they carry their own financing rules; see Delaware manufactured home loans.
Our Ties to Dover and Kent County
Our connection to Dover runs through education and program access, and each of these can be checked:
- A free Dover first-time home buyer seminar, so Kent County buyers can learn the process, and the DSHA education step, close to home.
- An approved lender for the City of Dover First Start program, which means we originate the first mortgage and submit the City funding request for eligible buyers.
- VA lending for Dover Air Force Base service members and veterans, including Certificate of Eligibility and PCS timing questions.
- John earned his Master of Science in Curriculum and Instruction at Delaware State University in Dover.
- A DSHA-approved lender, so Dover buyers can use Welcome Home, Open Door and every DSHA assistance option through us.
Dover, Delaware Home Buying Questions
Local questions about buying in Dover and Kent County. Current as of October 2026.
Is a Dover, DE mailing address the same as being inside the Dover city limits?
No. Many homes with a Dover, DE 19901 or 19904 mailing address sit in unincorporated Kent County, outside the City of Dover. That matters because First Start, the City first-time transfer tax incentive and the Downtown Development District tax phase-in apply only inside the city limits. To check, look up the parcel on the City’s GIS map and see whether it falls inside the City boundary, or send us the address and we’ll check it. The City confirms it again on any First Start file.
Are any Dover homes in a DSHA targeted area?
No, as of October 2026. DSHA lists one targeted census tract in Kent County, 0425.00, and it is in Milford. Dover buyers use DSHA’s Kent County non-targeted limits: $111,400 for a 1-2 person household and $128,110 for 3 or more on Welcome Home. The targeted-area exception to the first-time rule doesn’t apply to a Dover address either.
Which county limits apply to a Dover purchase?
Kent County’s. For DSHA that means the Kent and Sussex limits, including a $566,354 purchase price limit as of October 2026. For FHA, the 2026 one-unit limit in Kent County is $541,287 on HUD’s FHA limit lookup. First Start uses the City’s own HUD-based Kent County income table, which counts everyone in the household, not only the borrowers.
Can I use a USDA loan for a home near Dover?
Often, if the home is outside the City of Dover. The city itself is generally too large for USDA’s rural map, but many Kent County areas around it, such as parts of Camden, Wyoming, Felton and Hartly, may be eligible. Eligibility goes address by address and also depends on household income, so check the specific home on the USDA map before writing an offer.
Do first-time buyers pay transfer tax in Dover?
Usually less. Delaware gives qualifying first-time buyers a reduction on the state share, and the City of Dover has its own first-time home owner incentive on the City share for homes inside the city limits. Each uses a never-owned test that is stricter than DSHA’s three-year rule, so check both before you budget your closing costs. The state rule is in 30 Del. C. 5401 and 5402.
Does living near Dover Air Force Base change which loan I should use?
For eligible service members and veterans, it usually puts VA first: no down payment and no monthly mortgage insurance, with the funding fee waived for veterans receiving disability compensation. Many homes near the base are outside the Dover city limits, so City programs may not apply there, while VA and DSHA still do.
FAQ: Dover Delaware Mortgage Loans
What credit score do I need for a mortgage in Dover, Delaware?
It depends on the program. HUD allows FHA with a 580 score and 3.5% down, or 500 to 579 with 10% down, and lenders can set higher minimums of their own. DSHA’s Welcome Home and Open Door need 620, Diamond in the Rough needs 640, and City of Dover First Start needs 620. VA, USDA and conventional minimums are set by the lender and the underwriting system. These are program rules, not an approval; your full credit, income and debt picture decides the terms.
Can I buy a home in Dover after a Chapter 7 bankruptcy?
Often, yes, once the program’s waiting period has passed. Each loan type sets its own wait after a Chapter 7 discharge, and some allow a shorter one when the bankruptcy came from circumstances outside your control. What counts after that is how your credit has been rebuilt since. Our buying a home after bankruptcy in Delaware page lays out the waiting periods, and a call with your discharge date lets us tell you where you stand.
Can I use the City of Dover First Start program and DSHA assistance on the same home?
Yes, when you qualify for both. On its own, First Start records in second lien position behind your first mortgage. Used with DSHA assistance, the City records in third position behind the DSHA second mortgage, so the two stack. First Start has its own tests, including a home inside the Dover city limits, the City’s 60% to 80% household income range and a $20,000 asset cap. The full rules are on our City of Dover First Start program page.
Can I use a VA loan to buy a home near Dover Air Force Base?
Yes. Eligible active-duty service members, veterans, qualifying Guard and Reserve members and eligible surviving spouses can buy a primary residence in the Dover area with no down payment and no monthly mortgage insurance. You need a Certificate of Eligibility and must meet the lender’s credit and income standards. Documented housing allowance can generally count as income. If PCS orders are coming before closing, tell us early, because the timing affects how VA’s occupancy rule is handled.
Do I have to be a first-time buyer to get help buying a home in Dover?
No. DSHA Open Door is open to repeat buyers and still pairs with First State (3%) or Keys4You (4%) assistance. DSHA Welcome Home, Take5 and City of Dover First Start are for buyers who haven’t owned a home in the past three years, and Welcome Home also accepts qualified veterans. So a Dover buyer who owned before still has a path to DSHA help through Open Door.
Can I use gift funds toward a Dover home purchase?
In most cases, yes. FHA, VA, USDA, conventional and DSHA loans allow documented gifts from eligible donors toward the down payment and closing costs, with a signed gift letter and a paper trail for the money. City of Dover First Start is the exception to watch: you must put in at least $1,000 of your own money, and a gift doesn’t count toward that $1,000. Our gift funds guidelines cover the documents.
Can I use a Dover assistance program for a home that needs repairs?
Possibly. DSHA’s Diamond in the Rough pairs 5% assistance with an FHA 203(k) Limited loan for Welcome Home buyers with a 640 score, so the purchase and certain repairs go into one loan, and the purchase plus repairs must stay under DSHA’s price limit. First Start has its own rule: an inspection by an inspector licensed by the City of Dover, with major defects repaired before closing. Plan extra days in the contract for either.
Do bonuses, overtime or commission count toward DSHA income limits in Dover?
On Welcome Home, yes: DSHA counts all income of everyone on the note and mortgage, including bonus and overtime, even income you don’t need to qualify. On Open Door, DSHA counts the qualifying income on the loan application. Household size, including people not on the loan, sets which Kent County limit applies. City of Dover First Start is different again, because it counts the income of the whole household.
Is the City of Dover First Start program funded right now?
Yes, as of October 2026. The program ran out of funds in the summer of 2026, and the City refunded it in September 2026. Money is awarded first-come, first-served, and the City doesn’t reserve it until you’re approved for a mortgage, so buyers who are already counseled and pre-approved are ahead in line. We set the file up so it can close with DSHA assistance if City money isn’t available when you need it.
How do I get started with a Dover mortgage?
Start with a conversation. Call 302-703-0727, schedule a 30-minute appointment, or apply online. We begin with a soft credit pull, check the address against the Dover city limits and the USDA map, and compare the loans and assistance you may qualify for, depending on your credit, income and the property. If you’re planning to use DSHA with a score at or below 659, our free Dover first-time home buyer seminar is a good first step on the education requirement.
About Your Dover Mortgage Lender, John Thomas
John R. Thomas is Branch Manager and Division Vice President with the John Thomas Team in Newark, Delaware, and has helped Delaware families buy homes for more than 20 years. On a Dover file, the first thing John checks is the parcel, because whether the home sits inside the city line decides whether First Start and the City tax breaks are even on the table before anyone compares loans.
John holds a BS in Physics Education from the University of Delaware and an MS in Curriculum and Instruction from Delaware State University in Dover. He is the author of Your Guide to Buying Your First Home in Delaware and teaches first-time buyer seminars, including one for Dover buyers. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access. Read more on his loan officer bio page.
Years 3,000+
Buyers Helped 1,000+
First-Time Buyers DE & MD
Service Area CMP
Certified Mortgage Planner
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com
Schedule Appointment (30 min)
See John Thomas Team on Google for reviews, directions, and local office information.
YouTube | Facebook | Instagram | TikTok | X / Twitter | LinkedIn
We start with a soft credit pull, so there’s no hit to your score. Then we check the address against the city line, show which loans and assistance you may qualify for, depending on your credit, income and the property, and walk you through your cash to close before you make an offer.
Last Updated: October 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
John R. Thomas, NMLS #38783 | John Thomas Team with AnnieMac Home Mortgage | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
AnnieMac Home Mortgage is an Equal Housing Lender. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access.
(c) Copyright John R. Thomas, All Rights Reserved.
