Smyrna Delaware Mortgage Loans for Kent and New Castle County Buyers


Current as of September 2026. Smyrna Delaware Mortgage Loans depend on which side of the county line the home sits. Most of Smyrna is in Kent County, where the 2026 FHA limit is $541,287 and DSHA’s price cap is $566,354; New Castle County-side addresses get $630,200 and $659,385. The town itself lost USDA eligibility in October 2023.
John R. Thomas | NMLS #38783 | 20+ Years | 3,000+ Delaware Buyers Helped | DSHA Approved Lender
Lending in Smyrna, Clayton, and the rest of Kent County from our Newark office. See John Thomas Team on Google for reviews, directions, and local office information.
If you’re pricing Smyrna Delaware Mortgage Loans, start with a question most buyers never think to ask: which county is the house in? Smyrna is one of the few Delaware towns that sits on a county line, and the answer moves your FHA limit, your DSHA income cap, and your USDA options. I’m John Thomas, NMLS #38783. Before I suggest a program for a Smyrna buyer, I pull the parcel record, because a 19977 ZIP code doesn’t tell me the county.
If you’re a first-time buyer, the state’s down payment help is usually the first thing to line up – our Delaware down payment assistance guide compares every program. For Kent County sales north of Dover, the Dover mortgage page covers the capital’s own city programs.
Send Me the Smyrna Address – I’ll Tell You Which Limits Apply
County, DSHA tier, FHA limit, and USDA map status, checked before you write an offer.
Table of Contents
Is Your Smyrna Home in Kent County or New Castle County?
Most Smyrna homes are in Kent County, but part of the town and some addresses with a Smyrna mailing address sit in New Castle County. As of September 2026 that difference is worth $88,913 of FHA loan room and $93,031 of DSHA purchase-price room. The county on the deed decides, not the 19977 ZIP code.
The reason is the map, not a quirk of any one program. Smyrna’s Kent County side belongs to the Dover metropolitan area, and its New Castle County side belongs to the Philadelphia metro. Federal and state agencies set limits by metro and county, so two homes a short drive apart can be governed by different numbers. Here is what that looks like for the programs Smyrna buyers use most.
| Limit (2026) | Kent County side | New Castle County side |
|---|---|---|
| FHA loan limit, 1-unit | $541,287 | $630,200 |
| DSHA purchase price limit, single-family (non-targeted) | $566,354 | $659,385 |
| DSHA Welcome Home income, 1-2 person | $111,400 | $122,700 |
| DSHA Welcome Home income, 3+ person | $128,110 | $141,105 |
| DSHA Open Door income, 1-2 person | $133,680 | $147,240 |
| DSHA Open Door income, 3+ person | $167,100 | $184,050 |
What this means for you: a two-person household earning $118,000 is over the Kent County Welcome Home income limit but under the New Castle County one, so the same buyer can be in or out of the first-time-buyer program depending on the lot. A buyer over both Welcome Home limits still has DSHA Open Door, which carries higher caps and allows repeat buyers.
DSHA also names targeted census tracts where income and price limits run higher – in Kent County that is a single tract, 0425.00. If you’re unsure whether an address is in it, DSHA points buyers to the FFIEC geocoding map, and I run that check along with the county lookup.
Can You Get a USDA Loan in Smyrna, Delaware?
Not inside the Town of Smyrna. USDA’s 2020-Census map update, effective for closings on or after October 1, 2023, removed the town from the eligible rural area. Some parcels outside the town boundary, in the farmland toward Clayton, Kenton and Cheswold, may still qualify, so the exact address has to be checked on the USDA map.
This is the most common piece of stale advice I see about Smyrna. Older listings and guides still describe the town as USDA-eligible, and buyers plan around zero down before they find out. If a Smyrna listing mentions USDA, treat it as a claim to verify. Outside the town line, a USDA Rural Development loan can still be the lowest-cash option, and the income limit follows the same county split as the table above – higher on the New Castle County side.
If the parcel is ineligible, the realistic zero- or low-cash paths for a Smyrna buyer are an FHA first mortgage paired with DSHA assistance, or a VA loan for eligible service members and veterans.
Which Loan Programs Fit Smyrna Delaware Mortgage Loans?
In Smyrna, FHA paired with DSHA down payment assistance fits most first-time buyers, VA fits Dover Air Force Base households, and conventional fits buyers with 5 to 20 percent down. The county line changes which limits apply to each option, and USDA only enters the picture for eligible parcels outside the town boundary.
| Program | Where it fits in Smyrna | Smyrna-specific check |
|---|---|---|
| FHA | First-time and credit-rebuilding buyers; 3.5% down | Kent-side ceiling $541,287 – above that, conventional or more down |
| DSHA Keys4You / Take5 | Down payment and closing-cost help as a 0% deferred second | Kent-side income and price caps apply; Take5 is Welcome Home only |
| VA | Active duty, veterans, eligible surviving spouses | No county loan limit with full entitlement |
| Conventional | 5-20% down, stronger credit | Same $832,750 conforming limit on both sides of the line |
| USDA | Rural parcels outside the town boundary | Not available inside the Town of Smyrna |
| Jumbo | Loan amounts above $832,750 | Rare in Smyrna; mostly larger lakefront homes |
Self-employed Smyrna buyers often qualify on tax returns, but when write-offs shrink income on paper, the self-employed mortgage options page explains the alternatives.
What Are Homes Selling for in Smyrna (ZIP 19977)?
As of May 2026, the median sale price in ZIP 19977 was $417,799, with a median 94 days on market and 89 active listings, according to the MBS Highway Real Estate Report Card for that ZIP. That median sits below both the Kent County FHA limit and DSHA’s Kent County price cap.
Ninety-plus days on market is slower than the northern New Castle County suburbs, and that changes negotiation. In a market where homes sit, sellers are more open to paying part of a buyer’s closing costs, which pairs well with DSHA assistance. It also means the median hides a wide spread: townhomes near the town center trade well below it, while the larger lakefront homes trade well above. I’ll refresh these figures at the next update; ask me for the current report before you make an offer.
How Much Cash Do You Need to Close on a $400,000 Smyrna Home?
On a $400,000 Smyrna purchase, the three largest buyer-side items total about $23,655 with FHA and $29,655 with 5% down conventional: the down payment, a 2% share of Delaware transfer tax, and the title premium. A DSHA Keys4You second of about $15,440 can cut the FHA figure to roughly $8,215.
| Item | FHA 3.5% down | Conventional 5% down | FHA + DSHA Keys4You |
|---|---|---|---|
| Down payment | $14,000 | $20,000 | $14,000 |
| Buyer share of transfer tax (2% of price) | $8,000 | $8,000 | $8,000 |
| Owner’s + lender’s title premium (filed rate) | $1,655 | $1,655 | $1,655 |
| Subtotal | $23,655 | $29,655 | $23,655 |
| DSHA Keys4You second mortgage (4% of first mortgage) | – | – | about -$15,440 |
| Net of these items | $23,655 | $29,655 | about $8,215 |
Two Smyrna-specific notes. First, new-construction contracts in the growing subdivisions around town often assign more of the transfer tax to the buyer than a standard resale contract does, so read that clause before you sign. Second, first-time buyers can cut their share through the Delaware first-time buyer transfer tax exemption. The title line comes from our breakdown of owner’s title insurance cost in Delaware.
Buying in Smyrna While Stationed at Dover Air Force Base
Smyrna sits north of Dover along US 13 and Route 1, which makes it a practical home base for Dover Air Force Base households who want a quieter town. A Delaware VA loan fits most of them: no down payment, no county loan limit for buyers with full entitlement, and no funding fee for veterans receiving VA compensation for a service-connected disability. Housing allowance can count as qualifying income when it’s documented on the Leave and Earnings Statement.
One thing to settle early: a buyer with reduced entitlement – often someone who still owns a home financed with a VA loan at a previous duty station – is measured against the county conforming limit, which is $832,750 in both Kent and New Castle Counties for 2026. How much of that you can use with no down payment depends on the entitlement you have left.
Smyrna Neighborhoods and the Loan Question Each One Raises
Smyrna is small, but where you buy inside it changes the paperwork. These are the areas I review most often for Smyrna buyers and the one question each tends to raise.
- Historic town center: older homes near Main Street and Commerce Street. Expect appraisal and repair questions on older houses; an FHA 203(k) or DSHA’s Diamond in the Rough program can finance minor repairs. Inside the town line, so no USDA.
- New subdivisions around the town edge: builder contracts, builder incentives, and the transfer tax clause. Compare a builder’s preferred-lender incentive against your own total cost before you commit.
- Lake Como and the larger lakefront homes: the part of Smyrna likeliest to exceed the Kent County FHA limit and DSHA’s $566,354 cap, where conventional financing usually takes over.
- Smyrna addresses north of the county line: New Castle County limits apply – confirm on the parcel record, not the envelope.
- Clayton, Kenton, and the farmland west and south of town: the places to check the USDA map, because some parcels outside the town boundary may still qualify.
Where the John Thomas Team Lends Around Smyrna
We lend across all three Delaware counties and in Maryland from our office at 248 E Chestnut Hill Rd in Newark. For a Smyrna buyer, that means one lender who can compare the Kent County and New Castle County numbers side by side.
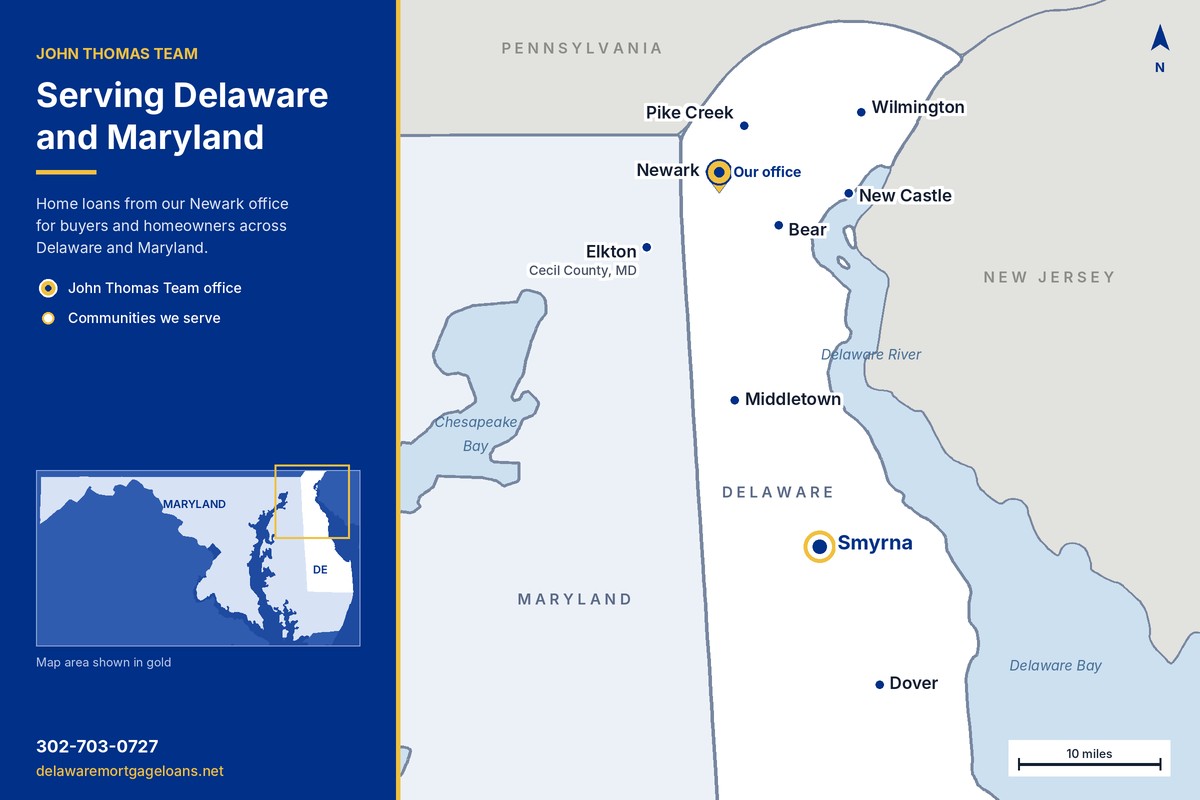
Most Smyrna files move from application to closing without an office visit: documents upload securely, disclosures are e-signed, and settlement happens with a Delaware attorney near the property.
Smyrna Buyer Questions, Answered Locally
Current as of September 2026. Local questions about Smyrna; loan-program questions are in the FAQ below.
Does a Smyrna mailing address mean the home is in Kent County?
Not always. The 19977 ZIP covers homes on both sides of the Kent-New Castle line. The county recorded on the deed and the county tax parcel decide which FHA, DSHA and USDA limits apply. Send the address and I’ll confirm the county before you pick a program.
Is any part of Smyrna a DSHA targeted area?
DSHA lists one targeted census tract in Kent County, 0425.00, where Welcome Home income limits rise to $133,680 (1-2 person) and $155,960 (3+ person) and the price cap to $692,211. Whether a particular Smyrna address falls in it is a lookup on the FFIEC map, which I run with the county check.
How much transfer tax does a Smyrna buyer pay?
Delaware’s realty transfer tax is 4% of the price in total. A standard resale contract usually splits it evenly, so the buyer pays 2% – $8,000 on a $400,000 home. New-construction contracts often shift more to the buyer, and eligible first-time buyers can reduce their share through the state exemption.
Can I still get a USDA loan for a home near Smyrna?
Possibly, if the home is outside the Town of Smyrna. The town lost USDA eligibility for closings on or after October 1, 2023, but some surrounding rural parcels may still qualify. The USDA eligibility map decides address by address.
Is Smyrna a good fit if I commute to Wilmington?
It can be, but it’s a longer daily drive than the towns closer to the canal, and that changes the math on a larger payment. If a Wilmington commute is daily, compare Smyrna prices against Middletown before you settle on a budget.
For the commute comparison, our Middletown mortgage page covers the town just north of the county line.
When a Smyrna Mortgage Plan Is the Wrong Plan
A few plans look right on paper for Smyrna and fall apart on the specifics:
- Planning around USDA for a home inside town. It isn’t eligible. Plan FHA with DSHA assistance, or VA if you’re eligible, instead.
- Using the New Castle County limits for a Kent County house. If the parcel is in Kent County, a household of two above $111,400 is over the Welcome Home limit – Open Door, with its $133,680 cap, is the next place to look.
- FHA on a Kent County home priced well above $541,287. The extra down payment needed to stay under the limit often makes conventional the better choice.
- DSHA assistance on a home above $566,354 in Kent County. The price cap rules it out unless the home is in a targeted tract.
- Stretching to the top of approval for a daily Wilmington commute. Fuel and time costs are real; budget the payment with the commute in it.
Smyrna Delaware Mortgage Loans FAQ
What credit score do I need for a DSHA loan in Smyrna?
DSHA requires a 620 minimum credit score for Welcome Home and Open Door, and buyers at 659 or below complete housing counseling before closing. The first mortgage underneath DSHA – FHA, VA, USDA, or conventional – has its own requirements, and lenders can set floors above the program minimum. The same score rules apply on both sides of the county line; only the income and price limits change.
My income is over the Kent County Welcome Home limit. Do I have options in Smyrna?
Yes. If the home is on the New Castle County side, the higher New Castle limits ($122,700 for 1-2 people, $141,105 for 3 or more) may apply. If it’s in Kent County, DSHA Open Door allows up to $133,680 or $167,100 and is open to repeat buyers. A home in DSHA’s targeted Kent tract also raises the Welcome Home limit. We compare all three before you choose.
Can I buy a Smyrna home above $566,354 with DSHA help?
Only in limited cases. $566,354 is DSHA’s single-family purchase price limit for Kent County outside targeted areas as of September 2026. A New Castle County-side home can go to $659,385, and the Kent County targeted tract allows up to $692,211. Above those caps, conventional financing with your own down payment is the usual path.
Can I get an FHA loan for a Smyrna home over the Kent County FHA limit?
Yes, if you bring enough down payment to keep the loan at or below $541,287 for a one-unit Kent County home in 2026. On a $600,000 home that means putting down more than $58,700. At that point, a conventional loan with 5 to 10 percent down often costs less each month, so it’s worth pricing both.
I just got PCS orders to Dover Air Force Base. Can I buy in Smyrna before I arrive?
Often, yes. VA lenders can generally qualify you on your orders and your Leave and Earnings Statement, and settlement in Delaware can be completed with a local attorney. If you still own a home with a VA loan at your old station, your remaining entitlement affects how much you can borrow with no down payment.
Can I use gift money for a Smyrna home purchase?
Yes. FHA, VA, USDA, and conventional loans all accept documented gift funds from eligible donors, with a signed gift letter and a paper trail showing the transfer. DSHA’s assistance can be combined with a gift. Our gift funds guide covers donor rules and the gift letter; the one thing to avoid is moving large sums without documentation right before you apply.
I’m self-employed in Kent County. Can I still buy in Smyrna?
Usually. Most programs use two years of personal and business tax returns, and a strong year can be averaged against a weaker one. If deductions leave little taxable income, bank statement and 1099-based loans are alternatives, though they typically cost more and don’t pair with DSHA assistance. We review your returns before you shop so the budget is realistic.
Can I use a DSHA program with a USDA loan outside Smyrna?
DSHA’s Delaware Mortgage Program works with conventional, FHA, VA, and USDA first mortgages, so a USDA-eligible parcel outside the town boundary can pair with DSHA, subject to both programs’ income and price limits. Because USDA already requires no down payment, the DSHA second is typically used for closing costs. Eligibility of the parcel comes first.
Related reading: gift funds and gift of equity rules for Delaware buyers, and the Delaware first-time home buyer guide.
John R. Thomas
Branch Manager & Division Vice President, John Thomas Team with AnnieMac Home Mortgage
John R. Thomas is a Branch Manager and Division Vice President with the John Thomas Team in Newark, Delaware, and the author of Your Guide to Buying Your First Home in Delaware. For Smyrna buyers his first step is the same every time: confirm the county and USDA map status of the exact parcel before any program is chosen, because in a town that straddles two counties the address decides the limits.
He holds a B.S. in Physics Education from the University of Delaware and an M.S. in Curriculum and Instruction from Delaware State University, and taught in Delaware schools before he started lending. Read more about John Thomas.
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com
Schedule Appointment (30 min) | See John Thomas Team on Google
YouTube · Facebook · Instagram · TikTok · X / Twitter · LinkedIn
State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access. Operational service area for purchase and refinance guidance on this site is Delaware and Maryland.
County, DSHA tier, FHA limit, USDA map status, and an estimate of your cash to close – for the exact Smyrna address you’re considering.
