
Chattel Loans Delaware: Mobile Home Financing on Leased Land


Direct Answer: A chattel loan in Delaware is a specialized home-only loan used to finance a mobile or manufactured home on leased land — typically in a mobile home park — where the home is treated as personal property, not real estate. Traditional FHA, VA, USDA, and Conventional loans do not work in these situations. Delaware chattel loans are available with credit scores as low as 550, minimum 5% down at 600+ credit, terms up to 25 years, and current rates ranging from 8.44% to 12.30% depending on credit tier (Triad, April 2026). Apply through John Thomas, NMLS #38783, at 302-703-0727.
If you’re buying a mobile home in a park in Delaware — or on a lot where you don’t own the land — you’re not looking for a traditional mortgage. You’re looking for a chattel loan. I’ve been helping Delaware buyers finance mobile homes on leased land for over 20 years, and I can tell you this up front: most lenders won’t touch these deals. The ones that do often don’t understand Delaware’s specific rules — including the 3.75% DMV fee the state charges because Delaware treats mobile homes as vehicles. My name is John Thomas, NMLS #38783, and my team at Primary Residential Mortgage specializes in exactly this kind of loan. This page walks you through how chattel loans work, what you’ll need to qualify, current rates, and what makes Delaware different.
Buying a Mobile Home in a Delaware Park? Let’s See What You Qualify For.
Most Delaware lenders can’t do chattel loans. We can. Credit scores from 550, terms up to 25 years, and a team that understands the Delaware DMV process. Three ways to get started:
Table of Contents
What Is a Chattel Loan in Delaware?
A chattel loan is a personal property loan used to finance a mobile or manufactured home that is not attached to land you own. Instead of the loan being secured by real estate — which is how a traditional mortgage works — the loan is secured by the home itself, much like a car loan is secured by the vehicle. That’s not just a legal technicality. It has real consequences for your down payment, your interest rate, your loan term, and whether you can use any down payment assistance programs.
In Delaware specifically, the state treats mobile homes on leased land as personal property with a VIN number, similar to a titled vehicle at the DMV. That means if you’re buying in a mobile home park — or on a lot where the land is leased from the park owner or a private landowner — FHA, VA, USDA, and Conventional loans do not apply. A chattel loan is almost always the only financing path available. The trade-off is that you get into a home faster, with less paperwork, but at a higher interest rate and shorter term than a traditional mortgage.
When Do You Actually Need a Chattel Loan?
You need a chattel loan when the home you’re buying is considered personal property rather than real estate. The most common situations in Delaware are:
- The home is in a mobile home park — you own the home but lease the lot from the park owner and pay monthly ground rent.
- The land is leased, not owned — you have a lease agreement with a private landowner rather than a deed to the land itself.
- The home is not permanently attached — the wheels are off and it sits on blocks or a slab, but the title has not been converted to real estate.
- The title has not been retired — even if the home is physically fixed to a foundation, if the manufacturer’s title is still active at the DMV, it’s chattel.
If you do own the land and the home is permanently attached to it with a retired title, you may qualify for a traditional mortgage instead — and you should. Traditional mortgages carry lower rates, longer terms, and are eligible for down payment assistance. See our page on Delaware Manufactured Home Loans for that path. For everything else, chattel is the answer, and we’ll cover the full pillar page at Mobile Home Loans on Leased Land.
What Credit Score Do I Need for a Chattel Loan in Delaware?
Delaware chattel loan credit requirements are more flexible than most buyers assume. Chattel lenders tier pricing into three programs — Gold, Silver, and Bronze — with credit score determining both your rate and how much down payment you’ll need. Here’s how Triad Financial Services — one of the country’s largest chattel lenders — structures their tiers as of April 2026:
- 640 and above (Gold tier) — qualifies for as little as 5% down (95% loan-to-value) with the lowest available rates on a primary residence.
- 600 to 639 (Silver tier) — still qualifies for 5% down, but at higher rates than Gold.
- 575 to 599 (Bronze tier) — minimum 15% down. 5% and 10% down options are not available at this credit tier.
- 550 to 574 (Bronze tier) — minimum 15% down, and you will likely need seller-paid closing costs to meet minimum loan-amount requirements.
- 625 minimum — required for vacation or secondary homes regardless of credit tier.
- Below 550 — typically will not qualify, but we can refer you to credit repair resources and build a plan to get you over the line.
What this means for you: a 640 credit score unlocks the best pricing tier with only 5% down. A 600 credit score still gets you in at 5% down, just at higher rates. If your score is between 550 and 574, plan on 15% down minimum — there is no 5% or 10% down option at that credit range with most chattel lenders. See the current rate table below for specific rates at each tier.

How Much Down Payment Do I Need?
Minimum down payment on a Delaware chattel loan ranges from 5% to 20% of the purchase price, depending on your credit profile and occupancy type. On a $200,000 mobile home in a Delaware park, that looks like:
- 5% down = $10,000 (640+ Gold or 600–639 Silver credit, primary residence)
- 15% down = $30,000 (550–599 Bronze credit, primary residence — 5% and 10% down not available below 575)
- 15% down = $30,000 (vacation or second home at 85% LTV)
- 20%+ down = $40,000+ (investment property or weaker profile)
Here’s the part most buyers don’t hear until they’re in the middle of the process: chattel loans are not eligible for any down payment assistance program. No DSHA programs, no grants, no NCC Teacher/Nurse — none of it. Those programs are built around real estate, and a chattel home isn’t real estate. That means the down payment, closing costs, and Delaware’s DMV fee all have to come from your own funds, gift funds from an eligible donor, or seller concessions. If you were hoping to combine a chattel loan with the Delaware Down Payment Assistance Programs, that’s not an option — we’ll need to plan your cash-to-close a different way.
Does Delaware Charge a Transfer Fee on Mobile Homes?
Yes — and this is the single biggest cost buyers don’t know about until closing. Because Delaware treats mobile homes on leased land as vehicles, the state charges a 3.75% Department of Motor Vehicles document fee at both purchase and sale, calculated on the sale price of the home. This is separate from any deed transfer tax — chattel homes don’t have deeds, so the DAR contract 2%/2% buyer-seller transfer tax split does not apply.
In practice, the 3.75% DMV fee is typically split 50/50 between buyer and seller by custom, though it is negotiable in the purchase contract. On a $150,000 mobile home, the total DMV fee is $5,625 — meaning the buyer pays about $2,813 and the seller pays about $2,813. On a $200,000 home, the total is $7,500 and the buyer pays roughly $3,750. This is cash at closing and is not rolled into the loan. When I pre-approve you, we build this number into your total cash-to-close so there are no surprises at the DMV.
Delaware Chattel Loan Requirements at a Glance
Beyond credit score and down payment, these are the core requirements for a Delaware chattel loan:
- Debt-to-income ratio: up to 50% for Gold and Silver tier credit profiles. Bronze tier DTI is evaluated case-by-case by the lender. Lot rent counts as a housing expense and is included in your housing DTI.
- Loan term: maximum 25 years (300 months) for loans of $40,000 or more; maximum 20 years (240 months) for loans under $40,000.
- Minimum loan amount: $20,000 for Gold and Silver tier; $50,000 for Bronze tier (or $25,000 if closing costs are seller-paid).
- Home age: must have been built after June 15, 1976 — this is the HUD Code cutoff. Pre-1976 “mobile homes” do not qualify for any lender program in Delaware.
- HUD label: the red HUD certification tag must be present and legible on the exterior of every transportable section of the home.
- HUD data plate: the interior data plate (usually inside a kitchen cabinet or utility closet) must be present and readable.
- Park approval: the mobile home park or leased lot must be approved by the lender. The park must meet basic quality standards, have an active written lease, and the lease term must be at least as long as the loan term.
- Occupancy: most chattel programs are primary residence or second home only. Investment/rental chattel loans are limited.
- Income documentation: two years of W-2s or tax returns, two months of pay stubs, and two months of bank statements — same as any mortgage.
Chattel Loan vs. Traditional Mortgage — Side by Side
Here’s a simple side-by-side comparison to help you understand your options:
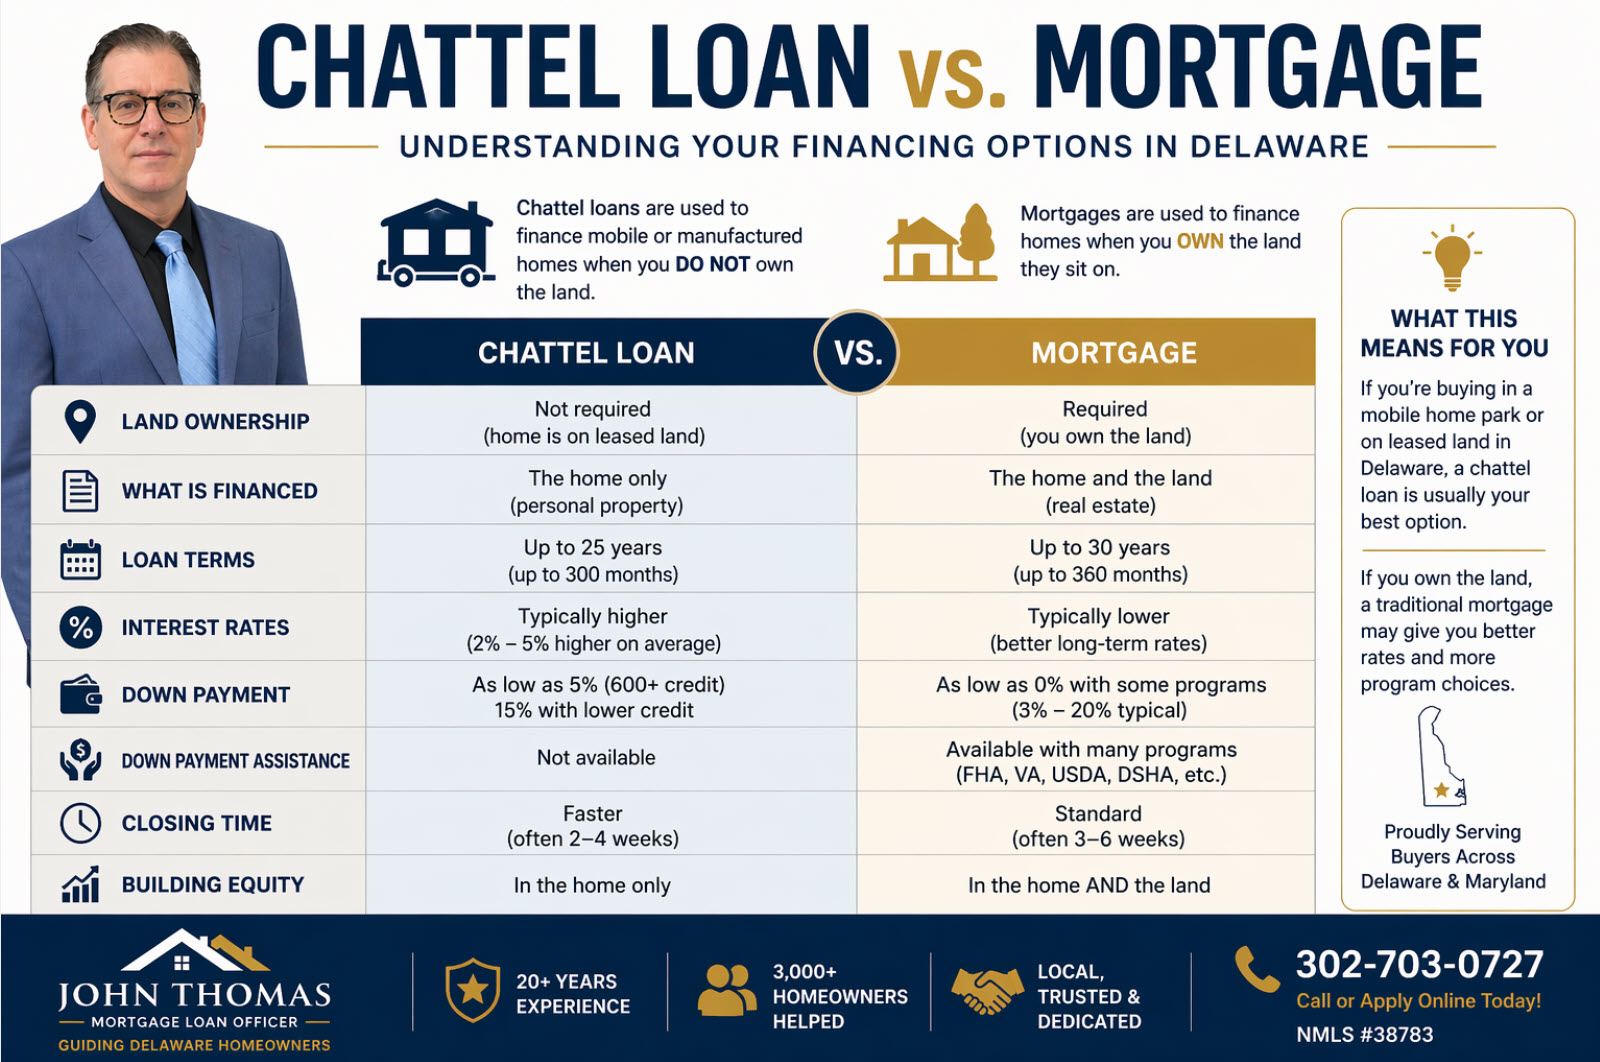

Here is how Delaware chattel loans compare to traditional mortgages (FHA, VA, USDA, Conventional) when both options are theoretically on the table:
| Feature | Chattel Loan | Traditional Mortgage |
|---|---|---|
| Land ownership required | No | Yes |
| What gets financed | Home only | Home + land |
| Loan term | Up to 25 years ($40K+ loans); 20 years under $40K | Up to 30 years |
| Interest rate range (Apr 2026) | 8.44% – 12.30% (Triad, varies by credit + down) | Market mortgage rate (lower) |
| Minimum credit score | 550 | 580 (FHA), 620 (Conventional) |
| Minimum down payment | 5% at 600+ credit; 15% below 575 | 3.5% FHA, 0% VA/USDA, 3% Conventional |
| Down payment assistance eligible | No | Yes — DSHA, NCC, Dover, Diamonds |
| Closing speed | Often 3–4 weeks | 4–6 weeks |
| Delaware transfer tax / fee | 3.75% DMV doc fee (split) | 4% deed transfer tax (2%/2% split on DAR contract) |
| Refinance to mortgage later? | Yes — if land is acquired and title retired | N/A |
| Mortgage insurance (MI) | Not applicable (no real estate) | Required below 20% down (except VA) |
What this tells you: if you already own the land, or you’re planning to buy land and the home together, the traditional mortgage path is almost always better — lower rate, longer term, access to assistance programs. Our Delaware FHA Loan page covers that path for manufactured homes on owned land. If you’re buying in a park, or on leased land where you’ll never own the dirt, a chattel loan is simply what’s available — and the goal is to get you in with the best possible terms. For a deeper comparison across every leased-land financing scenario, see our full guide to mobile home loans on leased land.
Current Chattel Loan Rates in Delaware
Chattel loan rates change frequently and vary by credit tier, down payment, loan term, and lender. The rates below reflect Triad Financial Services’ broker rate sheet effective April 20, 2026 — one of the largest chattel lenders serving Delaware. These are representative starting points for primary residence chattel loans. Your actual rate will depend on your full scenario, and I shop multiple chattel lenders (Triad, 21st Mortgage, Vanderbilt) to find the best pricing for each client.
| Credit Tier | Credit Score | Down Payment | Chattel 25-Year Rate | Chattel 20-Year Rate |
|---|---|---|---|---|
| Gold | 775+ | 5% – 35% | 8.59% | 8.44% |
| Gold | 740–774 | 5% – 35% | 8.64% | 8.49% |
| Gold | 700–739 | 5% – 35% | 8.69% – 8.89% | 8.54% – 8.74% |
| Gold | 650–699 | 5% – 35% | 9.66% – 9.78% | 9.51% – 9.63% |
| Gold | 640–649 | 5% – 35% | 10.09% – 10.21% | 9.94% – 10.06% |
| Silver | 640+ | 5% – 35% | 11.44% – 11.79% | 11.44% – 11.79% |
| Silver | 620–639 | 5% – 35% | 11.64% – 11.99% | 11.64% – 11.99% |
| Silver | 600–619 | 5% – 35% | 11.84% – 12.19% | 11.84% – 12.19% |
| Bronze | 600+ | 5% – 35% | 11.89% – 12.29% | 11.89% – 12.28% |
| Bronze | 575–599 | 15% – 35% (5% & 10% N/A) | 12.29% – 12.30% | 12.28% |
| Bronze | 550–574 | 15% – 35% (5% & 10% N/A) | 12.30% | 12.28% |
The pattern to notice: Gold tier (640+ credit) rates are roughly 3 points lower than Bronze tier (below 600). A 40-point credit score difference can mean the difference between an 8.69% rate and a 12.29% rate on the same home — over a 25-year term, that’s tens of thousands of dollars in interest. If your score is on the border between tiers, it is almost always worth taking 60–90 days to improve your credit before locking a rate.
What Mobile Home Parks Can I Buy In?
Delaware has nearly 90 mobile home parks in Sussex County alone, plus dozens more in Kent and New Castle counties. We’ve financed chattel loans in most of them. The most popular leased-land communities we see offers and pre-approvals for include:
- Pot Nets Communities (multiple locations near Long Neck / Millsboro) — highest amenities, highest ground rent, strong resale.
- Rehoboth Bay Mobile Home Park — Rehoboth Beach area, waterfront access, long-established community.
- Sea Air Village — Rehoboth Beach, newer inventory (2026-model homes in the $159,995 range).
- Sussex West & Sussex East — Lewes area, family-oriented, competitive ground rent.
- Bay City Mobile Home Park — Millsboro, resort-style amenities coming online.
- Village of Cool Branch — Seaford, inland Sussex, lower price point ($212,900 range for 2023-build).
Current Sussex County pricing (April 2026) generally runs from about $159,995 for newer single-wides in Rehoboth Bay-area parks up to $229,900 for newer double-wides in amenity-rich communities. Ground rent across Delaware’s beach-area parks has climbed significantly since 2021 — what used to be $550/month is now $700+ in many communities, and over $1,000/month in the highest-amenity parks. When I build your pre-approval, we underwrite both your housing payment and your ground rent together, because the park can raise your rent without your approval and we want to make sure you stay comfortable even if it goes up.
FHA Title I Chattel Loan vs. Conventional Chattel — What’s the Difference?
There are two flavors of chattel financing. The one most Delaware buyers use is a conventional chattel loan through specialty lenders like Triad Financial Services, 21st Mortgage, or Vanderbilt Mortgage. These are the 550-credit, 5%-down programs described above.
The second type is the FHA Title I Chattel Loan — a government-insured program that treats the home as personal property but follows FHA underwriting guidelines. Title I loans are rarer and have stricter property condition standards, but they can offer slightly better rates and more flexibility for certain borrowers. Most national specialty lenders do not offer Title I, so availability is limited. When I run your scenario, I’ll tell you whether Title I is worth pursuing or whether a conventional chattel program will get you the better deal faster. Either way, if you’re also considering a traditional government-backed program on owned land, check our Loan Programs overview to see every option side by side.
Can I Refinance a Chattel Loan Into a Traditional Mortgage Later?
Yes — and this is one of the most powerful long-term plays a chattel borrower can make. If you eventually buy the land your home sits on, permanently affix the home to a foundation, and surrender the manufacturer’s title at the Delaware DMV (the process is called “retiring the title”), the home legally converts from personal property to real property. Once that’s done, you can refinance the chattel loan into a traditional FHA, VA, USDA, or Conventional mortgage — lower rate, longer term, and equity in both the home and the land going forward.
The catch: the land has to actually be for sale, and you need to qualify to purchase both the land and refinance the home. Some parks eventually convert to resident-owned cooperatives or sell individual lots — if you’re in a park where that’s possible, it’s worth asking the park owner directly. I’ve walked more than one client through exactly this conversion, and the long-term savings on interest rate alone can easily run into the tens of thousands over the life of the loan.
A Real Delaware Example
Here’s what a typical deal looks like in practice. A buyer in Sussex County finds a 2023-build doublewide in Bay City Mobile Home Park listed at $212,900.
- Credit score: 635
- Down payment: 5% = $10,645
- Delaware DMV fee (buyer share): approximately $3,992
- Estimated closing costs: roughly $4,500
- Total estimated cash-to-close: about $19,137
- Ground rent at the park: roughly $850/month
- Loan term: 23 years
That buyer qualifies with a debt-to-income ratio inside program guidelines and moves into a brand-new home without needing to buy land. In Sussex County — where the median single-family home price is well above $450,000 — a chattel purchase is often the only path under $250,000 total cost of entry. That’s why our Delaware First Time Home Buyer clients who don’t qualify for DSHA Welcome Home or Delaware VA Loan programs often end up on the chattel path.
Watch: Chattel Loans Explained in Plain English
I recorded this video to walk buyers through exactly how chattel loans work, who qualifies, and what to expect at closing. If you’re visual, start here:
About the Author — John R. Thomas
Branch Manager & Senior Mortgage Loan Officer • Primary Residential Mortgage, Inc.
John R. Thomas has been helping Delaware home buyers finance mobile homes, manufactured homes, and every other property type for more than 20 years. As a Branch Manager with Primary Residential Mortgage in Newark, Delaware, he specializes in loan programs most lenders don’t touch — including chattel loans for leased-land mobile homes, FHA 203(k) renovation loans, and non-QM financing for self-employed borrowers. When a program exists anywhere in Delaware, John and his team know how to use it.
John is the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826), hosts the monthly Delaware Home Buyer Seminar, and has guided more than 3,000 Delaware families through the mortgage process. Whether you’re looking at a single-wide in Sussex West or a brand-new double-wide in a Pot Nets community, John’s team will tell you honestly whether a chattel loan, a traditional mortgage, or waiting six months to improve your credit is the right next step.
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727
Schedule Appointment | YouTube Channel | delawaremortgageloans.net
FAQ — Chattel Loans Delaware
What is a chattel loan in Delaware?
A chattel loan is a home-only loan used to finance a mobile or manufactured home that sits on land you do not own — typically in a mobile home park or on a leased lot. Delaware treats these homes as personal property rather than real estate, so the loan is secured by the home itself rather than by a deed to the land. Chattel loans are available from specialty lenders with credit scores as low as 550 and minimum 5% down at qualifying credit tiers (640+ for best pricing).
Can I use DSHA or any Delaware down payment assistance on a chattel loan?
No. Every Delaware down payment assistance program — DSHA Welcome Home, DSHA Open Door, First State Home Loan, Delaware Diamonds, City of Dover First Start, and all local programs — requires the property to be real estate. A mobile home on leased land is personal property, not real estate, so chattel loans are not eligible for any of these programs. Your down payment, closing costs, and Delaware’s DMV transfer fee have to come from your own savings, eligible gift funds, or seller concessions.
What credit score do I need to get a chattel loan in Delaware?
Chattel lenders use three credit tiers: Gold (640+ credit) gets the best rates with 5% down, Silver (600–639) still qualifies for 5% down at higher rates, and Bronze (550–599) requires at least 15% down — 5% and 10% down options are not available below a 575 credit score. Vacation or second-home chattel loans usually require at least a 625 credit score. If your score is below 550, we can refer you to a credit-repair partner and build a 60-to-90-day plan to get you into qualifying territory.
Does Delaware charge a transfer tax or fee on mobile homes?
Yes, but it is not the standard deed transfer tax. Because Delaware treats mobile homes on leased land as vehicles, the state charges a 3.75% Department of Motor Vehicles document fee based on the sale price of the home. The fee is typically split 50/50 between buyer and seller, though it is negotiable in the purchase contract. On a $200,000 mobile home, the total fee is $7,500 — meaning the buyer’s share is roughly $3,750. This is cash at closing and cannot be rolled into the chattel loan.
Can I refinance a chattel loan into a traditional mortgage later?
Yes — if you eventually buy the land your home sits on, permanently affix the home to a foundation, and surrender the manufacturer’s title at the Delaware DMV, the home converts from personal property to real estate. Once that conversion is complete, you can refinance the chattel loan into a traditional FHA, VA, USDA, or Conventional mortgage, which usually means a lower interest rate, a longer term, and the ability to build equity in both the home and the land.
How long does it take to close a chattel loan in Delaware?
A typical Delaware chattel loan closes in about three to four weeks once you have a signed purchase agreement and a fully approved park application. That is faster than most traditional mortgages, which usually run four to six weeks, because chattel loans do not require a full real estate title search, deed preparation, or lender’s title insurance. The variables that can slow a chattel closing are park approval, home inspection, and Delaware DMV title transfer processing.
What are current chattel loan rates in Delaware?
As of April 2026, Delaware chattel loan rates from Triad Financial Services — one of the largest chattel lenders — range from 8.44% for top-tier Gold borrowers (775+ credit, 20-year term) up to 12.30% for Bronze tier borrowers (550–574 credit). Silver tier pricing (600–639 credit) generally runs 11.44% to 12.19%. Your actual rate depends on credit score, down payment, loan term, and home type. Rates are subject to change without notice and are not a commitment to lend — call 302-703-0727 for a current quote on your scenario.
Can the park deny my chattel loan application?
Yes, and this is a step most buyers underestimate. Every mobile home park in Delaware runs its own credit, background, and income screening on incoming residents, separate from the lender’s underwriting. If the park denies your application, the chattel loan cannot proceed — even if your loan is fully approved. Good practice is to submit your park application at the same time you go under contract on the home, so that both tracks move in parallel and you don’t lose weeks if either one needs more documentation.
Ready to Get Pre-Approved for a Delaware Chattel Loan?
Mobile home financing on leased land is a specialty — work with the team that closes these every month.
We’ll review your credit, income, the park you’re interested in, and the Delaware DMV costs in one 30-minute call and give you a clear yes-or-no on your qualifying amount. No pressure, no obligation, no cost. Not sure yet whether chattel is the right fit? Start with our broader overview of leased-land financing options in Delaware.
Last Updated: April 2026
John Thomas, NMLS #38783 | Primary Residential Mortgage, Inc. | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
Copyright John R. Thomas, All Rights Reserved.
