DSHA Home Sweet Home DPA Program — 2026 Status & Alternatives


Heads up: DSHA Home Sweet Home is not currently listed as an active DSHA DPA option.
As of April 2026, DSHA’s current Delaware Mortgage Program materials no longer list Home Sweet Home as an available down payment assistance option. The current DSHA DPA lineup includes First State, Keys4You, Take5, and Diamond in the Rough. Home Sweet Home was historically a temporary program that DSHA refunded multiple times — it may return only if DSHA refunds it again. In the meantime, Delaware buyers have strong DSHA DPA options available right now. Call John Thomas, NMLS #38783, at 302-703-0727 to find the best currently-funded program for your situation.
DSHA Home Sweet Home Quick Answer: The DSHA Home Sweet Home Program is a temporary Delaware down payment assistance program that provided $12,000 as a zero-interest forgivable second mortgage on homes priced at $285,000 or less. It forgave 10% per year over 10 years. Available to both first-time and repeat buyers using the DSHA Smart Start first mortgage. Not currently listed as an active DSHA DPA option as of April 2026 — see current alternatives below or call John Thomas at 302-703-0727.
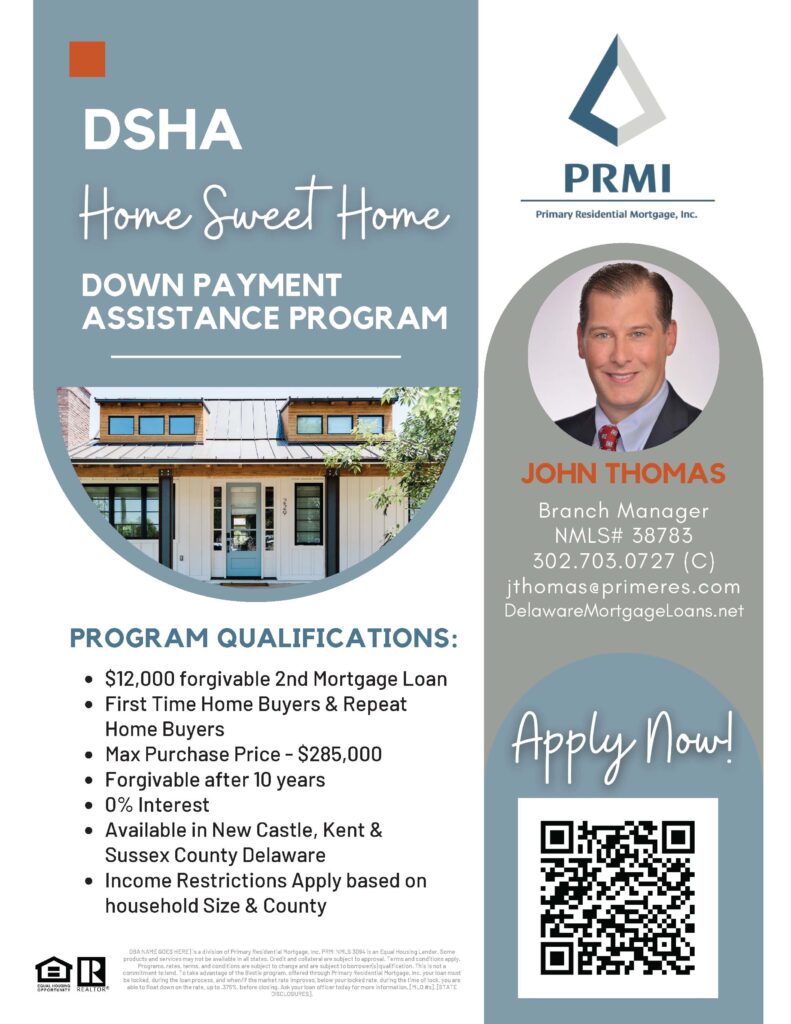
The DSHA Home Sweet Home Down Payment Assistance Program has been one of the most popular DPA options I’ve helped Delaware home buyers use since DSHA first launched it. The program provided $12,000 toward down payment and closing costs as a zero-interest forgivable second mortgage — and the best part is you didn’t have to be a first-time home buyer to qualify. As of April 2026, Home Sweet Home is no longer listed in DSHA’s current Delaware Mortgage Program lineup, but I’m keeping this page up because (1) DSHA has refunded Home Sweet Home multiple times in past years and could do so again, and (2) the buyers who used to qualify for Home Sweet Home almost always qualify for one of the currently-funded DPA programs I’ll walk you through below. If you’re looking at down payment assistance in Delaware right now, call my team at 302-703-0727 or APPLY ONLINE and I’ll match you with the best DPA available today.
| Current status | Not currently listed as an active DSHA DPA option (April 2026) |
| Assistance amount | $12,000 |
| Loan structure | 0% interest forgivable second mortgage |
| Forgiveness schedule | 10% per year over 10 years (fully forgiven after year 10) |
| Maximum purchase price | $285,000 |
| Minimum credit score | 620 (660 for manufactured homes) |
| Buyer type | First-time and repeat home buyers |
| Required first mortgage | DSHA Smart Start (FHA, VA, USDA, or Conventional) |
| Best current alternative | Keys4You (for many repeat buyers) — see comparison below |
| Call to review options | 302-703-0727 |
Find the Right DSHA DPA for You Today
I’ll review your county, income, credit, and purchase goal and tell you exactly which currently-funded DSHA DPA program is the best fit. No pressure, no obligation.
What You’ll Learn on This Page
- What the DSHA Home Sweet Home program was and how it worked
- Why Home Sweet Home is not currently listed as an active DSHA DPA option in 2026
- How the $12,000 zero-interest forgivable second mortgage was structured and forgiven
- The Home Sweet Home eligibility rules — credit score, income limits, purchase price cap, and property types
- Which currently-funded DSHA DPA programs replace Home Sweet Home for today’s Delaware buyers
- Side-by-side comparison of Home Sweet Home vs. Keys4You, First State, Take5, and Diamond in the Rough
- How to find out which DSHA program is the best fit for your situation in about 15 minutes
Table of Contents
What Is the DSHA Home Sweet Home Program?
The Home Sweet Home Program is a Delaware State Housing Authority (DSHA) down payment and closing cost assistance program that has been funded and refunded as a temporary program since DSHA first launched it. When the program is funded, it provides $12,000 to eligible Delaware home buyers as a zero-interest second mortgage on homes priced at $285,000 or less. The $12,000 second mortgage is forgiven at the rate of 10% per year over a 10-year period as long as the home remains the buyer’s primary residence — meaning if you stay in the house for 10 years, you owe nothing back. DSHA designed this program for low-to-moderate-income buyers who need help getting to closing on an entry-level priced home, and it’s open to both first-time and repeat home buyers, which makes it different from most other DPA programs.
Historically, DSHA has funded Home Sweet Home through state appropriations and bond proceeds. In 2023 alone, 180 Delaware families received Home Sweet Home assistance totaling roughly $2.16 million, and the program was refunded again in January 2024. The program has paused and been refunded several times over the years — that’s why I’m keeping this page up even though Home Sweet Home is not part of DSHA’s current Delaware Mortgage Program lineup. If DSHA refunds Home Sweet Home again, this page will be one of the first places to update with the new details.
What Were the Guidelines for the DSHA Home Sweet Home Program?
When the DSHA Home Sweet Home program is funded, it has very specific eligibility guidelines that I want to document here in case the program returns. To qualify, the buyer must be purchasing a home in Delaware as a primary residence and must use a DSHA-approved mortgage lender for the first mortgage. The first mortgage must be the DSHA Smart Start Home Loan — which is the DSHA name for an FHA, VA, USDA, or Conventional loan originated through one of DSHA’s approved lenders. Below are the full Home Sweet Home guidelines as they were when the program was last funded:
- Available to both Delaware first-time home buyers and repeat home buyers
- Property must be the buyer’s primary residence
- All borrowers must have a minimum 620 middle credit score
- Maximum purchase price is $285,000 or less
- $12,000 zero-interest forgivable second mortgage
- Second mortgage forgiven 10% per year over 10 years
- Must use the DSHA Smart Start Home Loan as the first mortgage from a DSHA-approved lender
- Available statewide — New Castle County, Kent County, and Sussex County
- Must be under the household income limit based on county and household size
- Must complete 8 hours of HUD-approved home buyer counseling if credit score is less than 660
- Could be combined with the Delaware Mortgage Credit Certificate (MCC) Program when both programs were funded
Here’s what this means for you: A 620 score may still be workable, but if your score lands between 620 and 659, the 8 hours of HUD-approved counseling is mandatory. We’ll walk through your credit report, income, and DPA pairing options before you make an offer so there are no surprises at underwriting. The same counseling rule applies to most current DSHA DPA programs.
What Were the Eligible Property Types for the Home Sweet Home Program?
The DSHA Home Sweet Home Program allowed buyers to purchase a fairly wide range of property types — wider than some of the other DSHA DPA programs. Eligible property types included:
- Single-family residences (detached homes)
- Townhomes and row homes
- Warrantable condos
- Planned Unit Developments (PUDs)
- Manufactured homes that meet program guidelines (660 minimum credit score)
- 1-4 unit properties as long as the buyer occupies one unit as primary residence
Properties that were not eligible for Home Sweet Home DPA included rental properties, second homes, co-ops, non-warrantable condos, and investment properties. The “primary residence” requirement was strict — the borrower had to occupy the property within 60 days of closing.
What Were the Income Limits for the Home Sweet Home DPA?
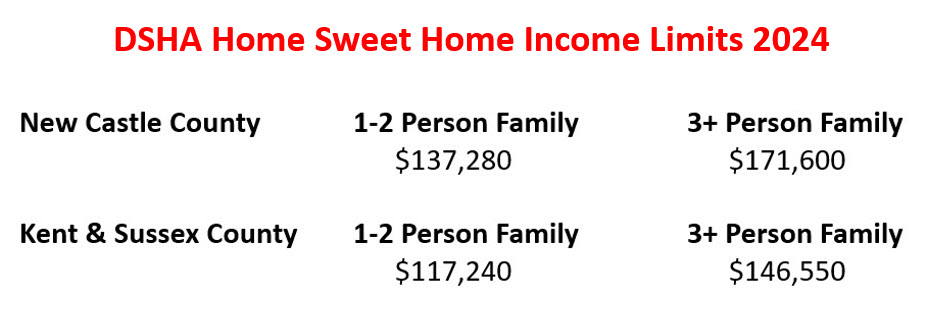
Home Sweet Home is built around an 80% Area Median Income (AMI) cap — meaning to be eligible, the household income had to be at or below 80% of the AMI for the county where the property is located. The income limits change as DSHA periodically updates them, but here are the most recent published limits for the program when it was last funded, as a reference for what to expect if Home Sweet Home returns:
| County | 1–2 Person Household | 3+ Person Household |
|---|---|---|
| New Castle County | $126,480 | $158,100 |
| Kent County | $116,280 | $145,350 |
| Sussex County | $116,280 | $145,350 |
Source: DSHA last-published Home Sweet Home limits at 80% AMI. These figures are reference only — Home Sweet Home is not currently listed as an active DSHA DPA option. If DSHA refunds Home Sweet Home, updated limits will be published at that time. Call 302-703-0727 to confirm the current published figures for any active DSHA DPA program.
Here’s what this means for you: Home Sweet Home historically used the 80% AMI threshold, which is fairly tight by Delaware standards. The currently-funded DSHA DPAs (Keys4You, First State, Take5, Diamond in the Rough) often have higher limits when paired with the Open Door first mortgage track — especially helpful for repeat buyers and dual-income households. We’ll calculate your AMI percentage and tell you which programs you actually qualify for in 15 minutes.
How Was the $12,000 Forgivable Second Mortgage Paid Back?
The $12,000 Home Sweet Home second mortgage is structured as a forgivable loan — not a grant. The forgiveness clock runs over 10 years, and 10% of the original $12,000 balance is forgiven each year that the buyer occupies the property as their primary residence. After year 10, the full balance is forgiven and the buyer owes nothing. If the buyer sold the home, refinanced, transferred title, or moved out before year 10, the unforgiven balance had to be paid back at that time. Here’s the year-by-year breakdown of the remaining balance:
| Year of Occupancy | % Forgiven | Balance Owed if Sold/Refinanced |
|---|---|---|
| After Year 1 | 10% | $10,800 |
| After Year 2 | 20% | $9,600 |
| After Year 3 | 30% | $8,400 |
| After Year 4 | 40% | $7,200 |
| After Year 5 | 50% | $6,000 |
| After Year 6 | 60% | $4,800 |
| After Year 7 | 70% | $3,600 |
| After Year 8 | 80% | $2,400 |
| After Year 9 | 90% | $1,200 |
| After Year 10 | 100% | $0 — Fully Forgiven |
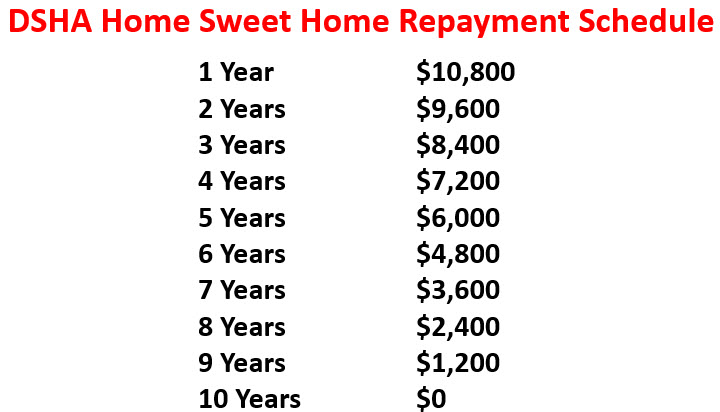
For example, if a buyer sells the home or refinances after 2 years of occupancy, they would owe $9,600 to pay off the Home Sweet Home second mortgage at the time of closing. After year 10, DSHA requires the borrower to provide proof they lived in the property — typically a driver’s license or utility bill showing the property address — and then the loan is fully forgiven and the lien is released. One thing I always tell my buyers up front: don’t take Home Sweet Home (or any forgivable DPA) unless you actually plan to stay in the home for at least 5 years. Otherwise the math starts working against you.
Is the DSHA Home Sweet Home Program Available in 2026?
Quick answer: DSHA Home Sweet Home is not currently listed as an active DSHA down payment assistance option in the 2026 Delaware Mortgage Program. Buyers who would have used Home Sweet Home should compare Keys4You, First State, Take5, and Diamond in the Rough.
As of April 2026, the DSHA Home Sweet Home Program is not listed as an active option in DSHA’s current Delaware Mortgage Program lineup. Home Sweet Home was always officially classified by DSHA as a “Temporary” program, and over the years DSHA has cycled it on and off — funding it through state appropriations and bond proceeds, then pausing it when the funding pool was depleted, then refunding it. The most recent funding refresh happened in January 2024, and after the 2024 allocation was committed, the program paused again. On April 16, 2026, DSHA announced a major rebrand of its single-family lending products — replacing the “Kiss Your Landlord Goodbye” branding with the “Delaware Mortgage Program” and adding two new DPA products (Keys4You and Take5) to its lineup. As of right now, Home Sweet Home is not part of the current DSHA Delaware Mortgage Program offering, but DSHA has refunded it before and could do so again. If the program returns, this page will be the first place I update with new details. The faster path forward, though, is the currently-funded DPA programs below.
What Replaced DSHA Home Sweet Home?
Quick answer: DSHA has not announced a direct replacement for Home Sweet Home. For many repeat buyers, the closest current option is Keys4You because it provides 4% down payment assistance and pairs with the DSHA Open Door first mortgage.
DSHA’s April 16, 2026 rebrand of the Delaware Mortgage Program did not announce a direct one-for-one replacement for Home Sweet Home. Instead, DSHA expanded its overall DPA offering with four products that, taken together, cover most of the buyer profiles Home Sweet Home historically served. For repeat buyers who used to be Home Sweet Home’s strongest fit, the closest current option is DSHA Keys4You: 4% of the first mortgage as a zero-interest deferred second, available to repeat buyers when paired with the Open Door first mortgage. For first-time buyers needing maximum DPA, Take5 provides 5% with the Welcome Home first mortgage. Each program has its own income limits, purchase price tolerance, and pairing rules, which is why a 15-minute call with a DSHA-approved lender almost always saves buyers money.
Was DSHA Home Sweet Home a Grant?
Quick answer: No. DSHA Home Sweet Home was a forgivable second mortgage, not a grant. The $12,000 balance was forgiven 10% per year over 10 years if the buyer kept the home as a primary residence. Sell, refinance, or move out before year 10 and you owed the unforgiven balance back at closing.
This is one of the most common misconceptions about Home Sweet Home, and the distinction matters in a few real-world scenarios. Because the assistance was structured as a recorded second mortgage with a 0% interest rate and a 10-year forgiveness clock, anything that broke the primary-residence requirement before year 10 — selling the home, refinancing the first mortgage, transferring title, or moving out — triggered repayment of the unforgiven balance at the time of that event. After year 10, you provided proof of residency (driver’s license or utility bill at the property address) and DSHA released the lien, fully forgiving the loan. None of the currently-funded DSHA DPAs are technically “grants” either — Keys4You, First State, Take5, and Diamond in the Rough are all second mortgages with their own deferral or forgiveness rules.
What Are the Current Alternatives to Home Sweet Home?
Most of the buyers who used to qualify for Home Sweet Home will qualify for one of the four currently-funded DSHA down payment assistance programs. The right program depends on (1) whether you’re a first-time buyer or repeat buyer, (2) your income relative to the program limits, and (3) whether you need help with closing costs only or both down payment and closing costs. Here’s how the current DSHA DPA lineup compares to Home Sweet Home — these are the programs I’m pairing with first mortgages right now in 2026:
| DSHA DPA Program | DPA Amount | Repeat Buyers? | Status |
|---|---|---|---|
| Home Sweet Home (this page) | $12,000 forgivable | Yes | Not currently listed |
| Keys4You | 4% of first mortgage, deferred 0% | Yes (with Open Door) | Funded |
| First State Home Loan | 3% of first mortgage, deferred 0% | Yes (with Open Door) | Funded |
| Take5 | 5% of first mortgage | Welcome Home (FTHB) only | Funded |
| Diamond in the Rough | 5% DPA + FHA 203k up to $75,000 renovation | Welcome Home (FTHB) only | Funded |
For repeat buyers — which is who Home Sweet Home was historically the best fit for — the closest current replacement is DSHA Keys4You paired with the DSHA Open Door first mortgage. Keys4You provides 4% of the first mortgage amount (so on a $300,000 loan, that’s $12,000 — the same dollar amount as Home Sweet Home) as a zero-interest deferred second. Unlike Home Sweet Home, Keys4You isn’t capped at $285,000 purchase price, so it’s more flexible for today’s market where the median Delaware home price has been running well above the old Home Sweet Home cap.
Which DSHA DPA Should You Use Instead of Home Sweet Home?
The right replacement depends on whether you’re a first-time buyer or a repeat buyer, how much DPA you actually need, and whether the home needs renovation work. Use this decision table to find your starting point — then we’ll fine-tune it on a 15-minute call.
| If you are… | Start here | Why |
|---|---|---|
| A repeat home buyer | Keys4You + Open Door | Largest current DSHA DPA available to repeat buyers — 4% deferred second, no purchase price cap |
| A first-time buyer who needs the most help | Take5 + Welcome Home | Provides 5% assistance with no monthly payment — strongest cash-to-close help for FTHBs |
| Buying a home that needs repairs | Diamond in the Rough | Combines 5% DPA with FHA 203(k) renovation financing up to $75,000 |
| Comfortable with a smaller DPA amount | First State | 3% deferred second mortgage — pairs with both Welcome Home and Open Door |
| Below the income limit and don’t need DPA | Smart Start (unassisted DSHA) | DSHA’s competitive 30-year fixed rate without a second mortgage attached |
Here’s what this means for you: If you would have qualified for Home Sweet Home before, you almost certainly qualify for one of the programs above today. The biggest practical difference is that you’re no longer limited to a $285,000 purchase price — most current DSHA DPAs work on higher-priced homes that match Delaware’s 2026 median sale price. Call my team and we’ll match your county, income, credit, and purchase goal to the best-fit program in about 15 minutes.
How Much Are Closing Costs in Delaware? (Transfer Tax Note)
One of the reasons DPA programs like Home Sweet Home are so important in Delaware is the state’s transfer tax — Delaware has one of the highest transfer taxes in the country at 4% of the purchase price, split equally 2% buyer and 2% seller under the standard Delaware Association of Realtors (DAR) sales contract. On a $250,000 home, that’s $5,000 the buyer typically owes at closing just for transfer tax. Home builders, however, write their own contracts and many require the buyer to pay the entire 4% transfer tax — which would be $10,000 on that same $250,000 home. Always read your sales contract carefully if you’re buying new construction, and ideally, have a buyer’s agent and a Delaware real estate attorney representing your interests so you don’t get stuck paying the full 4% by accident. This is exactly the kind of cost a DPA program like Home Sweet Home was designed to help cover.
Here’s what this means for you: If you’re a Delaware first-time home buyer using the standard DAR contract, you may also qualify for a partial state transfer tax exemption that further reduces your closing costs. Stack that with a current DSHA DPA like Keys4You, Take5, or First State and your cash-to-close can drop dramatically. We’ll run the math on your specific purchase before you sign anything.
How Do I Find Out If a DSHA DPA Is Right for Me?
The fastest way to find out which DSHA program fits your situation right now is to call my team at 302-703-0727 or apply online. Even if Home Sweet Home returns, you’ll get a head start on the qualification process. We start with a soft credit pull (which doesn’t impact your credit score), review your income against the current program limits, and identify which DSHA DPA pairs best with the right first mortgage — Welcome Home for first-time buyers, Open Door for repeat buyers, or one of our other Delaware loan programs if a DSHA loan isn’t the best fit. There’s no cost, no obligation, and no pressure. I’ve been originating DSHA loans since 2004, I’ve helped over 3,000 Delaware buyers close, and I can tell you in 15 minutes whether a DSHA DPA program is the right move for your purchase.
FAQ — DSHA Home Sweet Home Program
Is the DSHA Home Sweet Home program currently accepting new applications?
No. As of April 2026, the DSHA Home Sweet Home program is not currently listed as an active DSHA down payment assistance option in the Delaware Mortgage Program lineup. The program has historically been a temporary, refunded-as-funding-allows program — DSHA refunded it most recently in January 2024 and has paused it since the 2024 allocation was committed. DSHA could refund Home Sweet Home again in the future, but in the meantime there are four currently-funded DSHA DPA programs that cover most of the same buyer profiles. Call John Thomas at 302-703-0727 to find out which is the best fit right now.
How much down payment assistance did Home Sweet Home provide?
Home Sweet Home provided $12,000 as a zero-interest forgivable second mortgage that could be used for down payment, closing costs, or both. The $12,000 was forgiven 10% per year over 10 years, meaning if you stayed in the home as your primary residence for the full 10 years, the entire $12,000 was forgiven and you owed nothing. If you sold or refinanced before year 10, you owed back the unforgiven balance.
What was the maximum purchase price for Home Sweet Home?
The maximum sales price for the DSHA Home Sweet Home program was $285,000. This price cap is one reason the program is more limited than newer DSHA DPA options — the median Delaware home price has been running well above $285,000 since 2023. The currently-funded DSHA DPA programs (Keys4You, First State, Take5, Diamond in the Rough) do not have a $285,000 purchase price cap and can be used on higher-priced homes.
Did I have to be a first-time home buyer to use Home Sweet Home?
No. One of the best features of Home Sweet Home was that it was open to both first-time home buyers and repeat home buyers. This made it different from many other DPA programs, which restrict assistance to first-timers only. Of the currently-funded DSHA DPAs, the closest equivalent for repeat buyers is Keys4You paired with the DSHA Open Door first mortgage, which is also available to repeat buyers.
What credit score did I need for the Home Sweet Home program?
The minimum credit score for DSHA Home Sweet Home was 620 middle FICO score across all borrowers on the loan. Manufactured homes required a higher 660 minimum credit score. If your credit score was between 620 and 659, you were also required to complete 8 hours of HUD-approved home buyer counseling. The same credit score guidelines apply to all current DSHA programs.
What was the Smart Start Home Loan and was it required with Home Sweet Home?
Yes — the DSHA Smart Start Home Loan was the required first mortgage when using Home Sweet Home. Smart Start was DSHA’s name for an FHA, VA, USDA, or Conventional loan originated through a DSHA-approved lender at DSHA’s published interest rate. As of the April 2026 DSHA rebrand, the first-mortgage tracks are now called Welcome Home (for first-time buyers) and Open Door (for repeat buyers and higher-income borrowers), but they work the same way — they’re DSHA’s branded first mortgages that pair with the DSHA DPA second mortgages.
What happened to the $12,000 if I sold the home before 10 years?
You had to pay back the unforgiven balance at the time of sale, refinance, or transfer of title. The forgiveness ran at 10% per year, so after 1 year you owed $10,800; after 5 years you owed $6,000; after 9 years you owed $1,200; and after 10 years the loan was fully forgiven. The unforgiven balance was paid out of the proceeds at closing, just like any other second mortgage payoff, and the lien was released.
Could Home Sweet Home be combined with the Delaware MCC tax credit?
Yes — when both programs were funded, Home Sweet Home could be combined with the Delaware Mortgage Credit Certificate (MCC) Program for first-time buyers in targeted areas or below the MCC income limits. The MCC provided a federal tax credit of up to 35% of annual mortgage interest paid, capped at $2,000 per year. The Delaware MCC program ended August 15, 2025 and is also currently not accepting new applications, so this combination is not currently available.
What is the best DPA program in Delaware right now if Home Sweet Home is unavailable?
It depends on whether you’re a first-time buyer or repeat buyer and on your purchase price. For repeat buyers (the buyers Home Sweet Home historically served well), the strongest current option is DSHA Keys4You — 4% of the first mortgage amount as a zero-interest deferred second, paired with the DSHA Open Door first mortgage. For first-time buyers, Take5 (5% DPA, Welcome Home only) and Diamond in the Rough (5% DPA plus 203k renovation up to $75,000) are excellent options. Call John Thomas at 302-703-0727 to compare them side by side for your specific situation.
Local DSHA Help for Delaware Buyers
I work with home buyers across all three Delaware counties — including Newark, Wilmington, Bear, Middletown, New Castle, Hockessin, Smyrna, Dover, Camden-Wyoming, Milford, Seaford, Georgetown, Lewes, and Rehoboth Beach. Home Sweet Home was historically used most heavily on entry-level homes around the $200,000–$285,000 range, which fits a lot of starter homes in northern New Castle County and central Kent County. With the program paused, here’s how the current DSHA DPA programs typically map to common Delaware buyer scenarios I see every week:
- Newark and Bear first-time buyer with $25k saved: Take5 paired with Welcome Home — 5% DPA covers most of the down payment plus part of closing costs.
- Dover repeat buyer comparing options: Keys4You paired with Open Door — 4% deferred second, no purchase price cap, available to repeat buyers.
- Middletown new-construction buyer: First State paired with Welcome Home or Open Door — 3% deferred second helps offset the full 4% transfer tax that builders often push to the buyer.
- Sussex County buyer eyeing a fixer-upper: Diamond in the Rough — 5% DPA plus FHA 203(k) renovation financing up to $75,000 in one loan.
- Wilmington or New Castle buyer with strong credit, no DPA needed: Smart Start (DSHA’s unassisted track) — competitive 30-year fixed without a second mortgage attached.
If you’re comparing DSHA down payment assistance programs in any of these areas, give my team a call. We’ll review your county, income, credit score, and purchase price before you make an offer — and tell you exactly which DSHA program produces the best result for your specific situation.
Sources Reviewed
The information on this page reflects DSHA’s published program materials and the April 16, 2026 Delaware Mortgage Program rebrand announcement. Sources reviewed for this page include:
- Delaware State Housing Authority — Delaware Mortgage Program (current product lineup)
- DSHA April 16, 2026 single-family mortgage product rebrand announcement
- DSHA Home Sweet Home historical program materials and 2024 program parameters
- HUD published income limits and area median income (AMI) tables
- Delaware Association of Realtors — standard sales contract and transfer tax allocation
- Delaware State Bank Commissioner — lender licensing requirements
Find Out Which DSHA DPA Is Right for You — Today
Home Sweet Home may be paused, but Delaware buyers still have strong DSHA DPA options available right now. I’ll review your income, credit, county, and purchase goal — and tell you exactly which currently-funded DSHA program is the best fit. Over 20 years of experience, 3,000+ Delaware buyers helped, and I’ve been originating DSHA loans since the day Home Sweet Home first launched.
Call 302-703-0727 Schedule Appointment Apply Online Now
Program availability, income limits, credit requirements, interest rates, and assistance amounts are subject to change by DSHA, investor guidelines, and market conditions. This page is for educational purposes and is not a commitment to lend or a guarantee of loan approval. All loans subject to credit and underwriting approval.
About the Author — John R. Thomas
Branch Manager & Mortgage Loan Officer — Primary Residential Mortgage, Inc.
John R. Thomas is a DSHA-approved mortgage loan officer and Branch Manager at Primary Residential Mortgage, Inc. in Newark, Delaware. With over 20 years of mortgage lending experience and 3,000+ Delaware buyers helped, John has originated DSHA Home Sweet Home loans since the program first launched and has guided more than 1,000 buyers through DSHA down payment assistance programs across all three Delaware counties.
John holds a Bachelor of Science in Physics Education from the University of Delaware and a Master of Science in Curriculum and Instruction from Delaware State University — credentials that translate directly into the way he teaches Delaware home buyers about complex topics like DPA forgiveness math, income limit tiers, and program pairing strategy.
John is the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826) and teaches the monthly Delaware First Time Home Buyer Seminar in Newark, Wilmington, and Dover. His firsthand expertise on the DSHA Home Sweet Home program — including the eligibility rules, income limits, repayment math, and pairing it with the right first mortgage — is the kind of lender knowledge national aggregator and bank sites simply cannot match.
248 E Chestnut Hill Rd, Newark, DE 19713
302-703-0727 | Schedule Appointment | See John Thomas Team on Google for reviews, directions, and local office information | YouTube Channel | NMLS #38783 Verified
Last Updated: April 28, 2026
John Thomas, NMLS #38783 | Primary Residential Mortgage, Inc. | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net | Licensed by the Delaware State Bank Commissioner | Equal Housing Lender
Copyright John R. Thomas, All Rights Reserved.
