The Five Factors of Credit Scoring – and How They Affect Your Delaware Mortgage
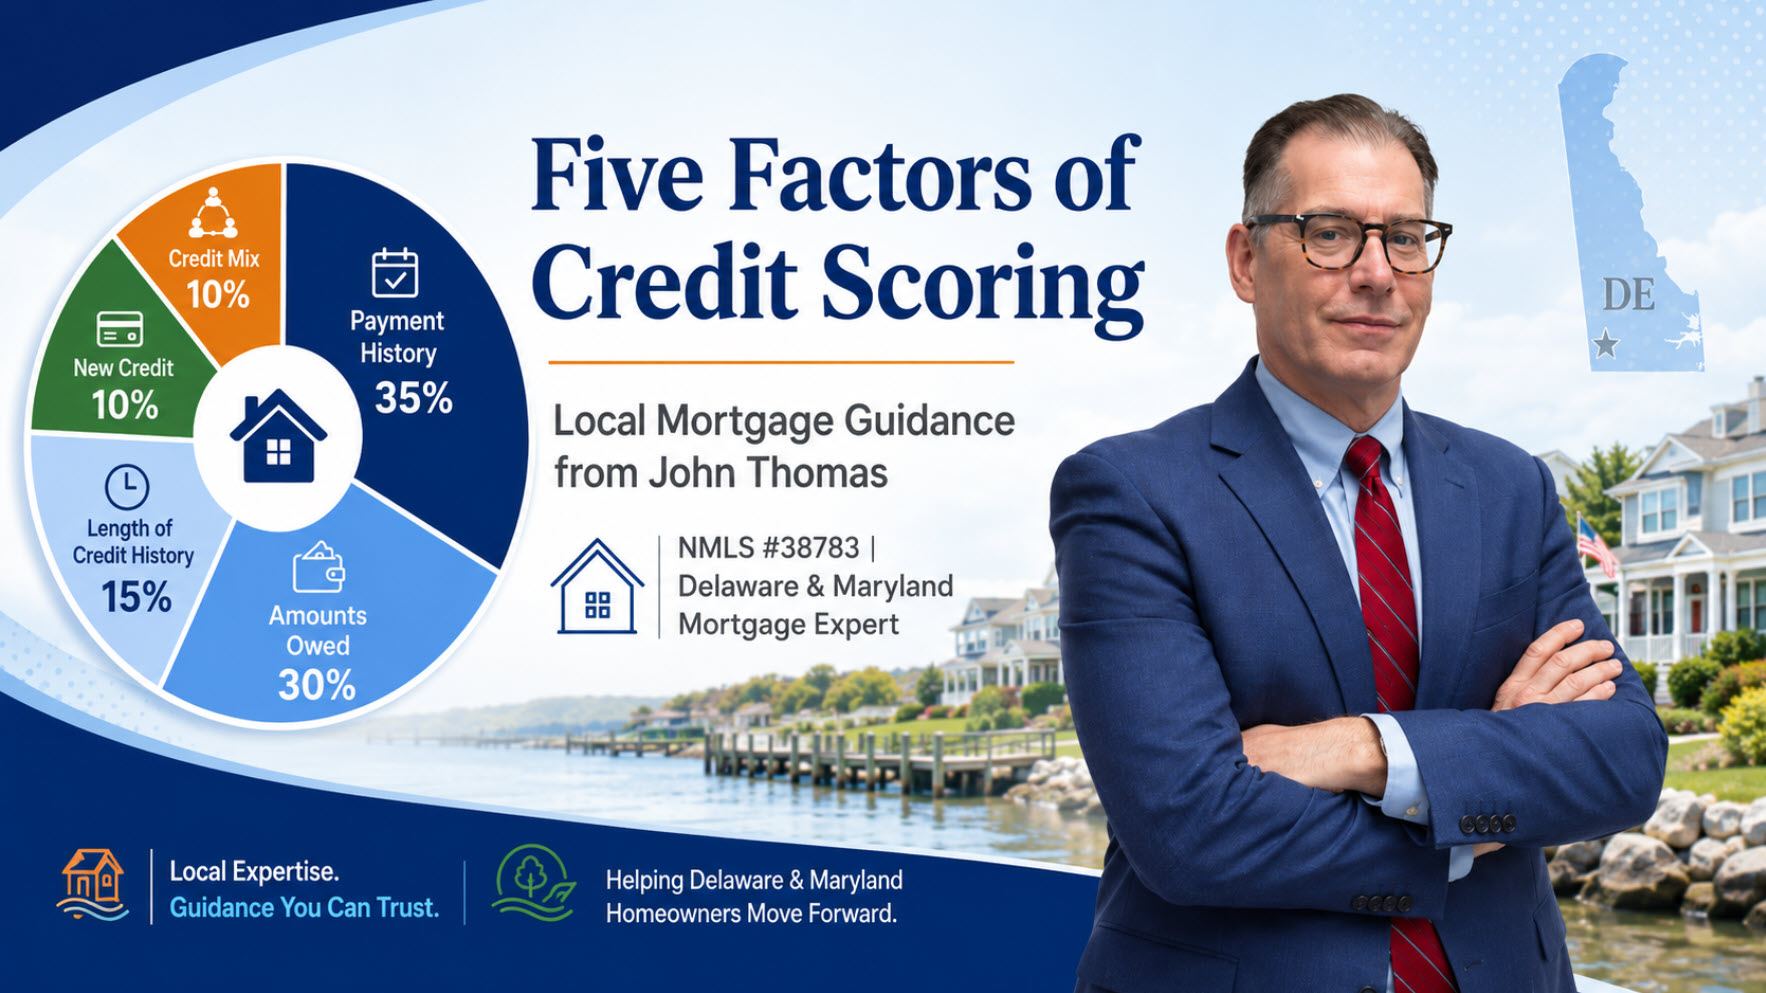
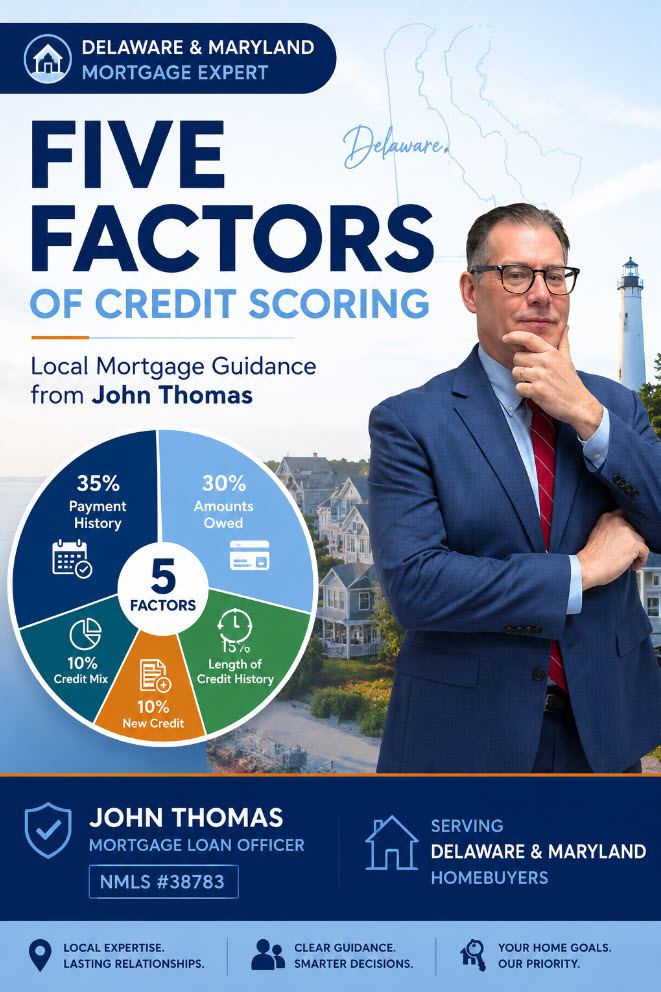
Quick answer: Your FICO credit score is built from five factors, weighted like this:
- Payment history – 35%: whether you pay on time
- Amounts owed – 30%: how much of your available credit you use
- Length of credit history – 15%: how long your accounts have been open
- New credit – 10%: recent applications and new accounts
- Credit mix – 10%: the variety of account types you manage
FICO scores range from 300 to 850, and mortgage lenders typically pull all three credit bureaus and use a representative score – most often your middle score. Current as of June 2026.
I am John Thomas, NMLS #38783, and from my Newark office in New Castle County I have spent more than 20 years helping buyers across Delaware and Maryland understand their credit and qualify for the right loan. I wrote the book “Your Guide to Buying Your First Home in Delaware,” and credit is the topic I am asked about most – because almost nothing affects your mortgage options more than your score. The good news is that a credit score is not a mystery. Fair Isaac Corporation (FICO) has publicly shared the five categories its model uses and roughly how much each one counts. Once you understand those five factors, you can make targeted moves that actually help. If you are early in the process, it also helps to read our guide to Delaware first-time home buyer programs and our overview of Delaware FHA loans, the program most often used by buyers who are still building credit.
Wondering how your credit score affects your loan options?
Let’s review your credit and map out the right program for your situation – no pressure, no obligation.
Table of Contents
What Are the Five Factors of Credit Scoring?
FICO calculates your score from the information in your credit report and groups that information into five categories. Each category carries a different weight, so knowing the weights tells you where your effort pays off the most. The five factors are:
- Payment history (35%): the record of whether you pay your accounts on time.
- Amounts owed (30%): how much of your available revolving credit you are currently using.
- Length of credit history (15%): how long your accounts have been open.
- New credit (10%): recent applications and newly opened accounts.
- Credit mix (10%): the variety of account types you manage.
| Credit Factor | Weight | What It Measures |
|---|---|---|
| Payment History | 35% | Whether you have paid past accounts on time |
| Amounts Owed (utilization) | 30% | How much of your available credit you are using |
| Length of Credit History | 15% | How long your accounts have been open |
| New Credit | 10% | Recent applications and newly opened accounts |
| Credit Mix | 10% | The variety of account types you manage |
Notice that the first two factors – payment history and amounts owed – make up nearly two-thirds of your score. If you only have time to focus on a couple of things before applying for a mortgage, focus there.
Payment History (35% of Your Score)
Payment history is the record of whether you pay your bills on time, and it has the single biggest impact on your score. Paying your debts on time and in full has a positive effect, while late payments and serious issues – judgments, collections, repossessions, and charge-offs – have a negative effect. The best thing you can do for your credit score is to make every monthly payment on time.
A few details matter for mortgage approval. Late payments are typically reported in 30, 60, 90, and 120-day buckets, and they can stay on your report for up to seven years (a Chapter 7 bankruptcy can stay for up to 10). The impact of an older late payment fades over time, especially when newer, positive activity surrounds it – so a mistake from years ago is rarely a dealbreaker if you have been consistent since. When you are within a year of buying, the simplest protection is to set up autopay for at least the minimum on every account so a single forgotten due date does not cost you.
Amounts Owed and Credit Utilization (30%)
Credit utilization is the percentage of your available revolving credit that you are currently using, and it drives most of this factor. The lower your utilization, the better. Keeping it below 30% is wise, and below 10% is even better. FICO has noted that people with the highest scores tend to use a small fraction of their available credit.
How to calculate utilization: Divide your balance by your limit. A card with a $2,000 balance and a $10,000 limit has 20% utilization ($2,000 / $10,000). Utilization is measured both per card and across all your cards, so a single maxed-out card can drag your score down even when your other cards are low. Lower utilization may help a mortgage score, though the exact effect depends on your complete credit file.
Pay your revolving balances down as close to zero as you reasonably can, and spread any remaining balance across your open cards rather than concentrating it on one. Hitting the maximum on any single card is especially negative. It is generally not a good idea to close an old account, because closing it reduces your available credit (which can push utilization up) and shortens the average age of your accounts. If your utilization is high, it can help to ask a card issuer to raise your limit – but only if they can do it without a hard inquiry. Utilization is one of the few factors that can move quickly: paying a balance down before the statement closes may improve your score within a single billing cycle.
What this means for you: If you are within 60 days of applying for a Delaware mortgage, do not open or close credit cards and do not run up balances. Pay revolving cards down before the statement date, and ask before making any big change – a quick conversation can keep a well-meaning move from lowering your score at the wrong moment.
Length of Credit History (15%)
This factor looks at how long your accounts have been open. A longer, seasoned history is stronger because it gives lenders more evidence of how you manage credit over time. Opening new accounts lowers the average age of your credit, which can hurt this portion of your score. That said, buyers with a short history can still earn an excellent score by paying on time and keeping utilization low – a thin file is not a barrier to a mortgage by itself.
Credit Mix and Type of Credit (10%)
FICO rewards a healthy mix of account types – a blend of installment loans (auto loans, student loans) and revolving accounts (credit cards) is viewed more favorably than a file made up entirely of credit cards. You do not need to take on debt you do not want just to diversify, but it is worth knowing that variety helps. Be cautious about opening store cards for very specialized retailers where you are likely to make a single purchase, since those can look like a reach for credit.
New Credit and Inquiries (10%)
When you apply for credit, the lender makes a hard inquiry, and several hard inquiries in a short window can lower your score. The effect is usually small – typically a few points – and it varies from one person to another. There is good news for anyone shopping for a mortgage: FICO treats multiple mortgage or auto inquiries within a focused shopping window as a single inquiry, so comparing lenders does not pile up separate dings. Depending on the scoring model, that window is generally 14 to 45 days, which is why it pays to do your rate shopping within a short, deliberate stretch of time.
Checking your own credit is a soft inquiry and never affects your score, so monitor it as often as you like. Beyond mortgage and auto rate-shopping, apply for new accounts only as you actually need them – a burst of applications can signal financial stress to the model.
What Does NOT Affect Your Credit Score?
Several things people assume hurt or help their score actually have no direct effect on the FICO number itself:
- Your income
- Your bank account balances
- Your job history and current employment status
- Your age and marital status
- Debit card and prepaid card usage
These items can absolutely affect whether you are approved for a mortgage – a lender weighs your income, employment, and assets when underwriting your loan – but they are not part of the credit-scoring formula. Medical collections are also treated differently than they used to be. Under voluntary changes the credit bureaus made in 2022 and 2023 that remain in effect in 2026, paid medical collections are removed regardless of balance, unpaid medical collections with an initial reported balance under $500 are excluded, and the bureaus wait a year before a medical collection can appear at all. (Unpaid medical debt over $500 can still be reported, and you can dispute errors through the CFPB.) If a medical bill has been weighing on your file, it may no longer be the obstacle you think it is.
What Is a Credit Score?
A credit score is a three-digit number lenders use to estimate the risk of lending to you. It is produced by a mathematical model that Fair Isaac Corporation, commonly known as FICO, first developed decades ago. Three major credit bureaus – Equifax, Experian, and TransUnion – each hold a credit file on you, so you actually have three scores, one from each bureau. FICO scores range from 300 to 850. As you will see below, mortgage lenders have a specific rule for which of your three scores they use.
What Is a Good Credit Score? (300-850 Ranges)
FICO scores fall on a 300 to 850 scale, and lenders generally group them into tiers. A “good” score under the common FICO definition starts at 670, but for a mortgage the more useful question is which program your score qualifies you for – which is covered in the next section.
| Score Range | Tier |
|---|---|
| 800-850 | Exceptional |
| 740-799 | Very Good |
| 670-739 | Good |
| 580-669 | Fair |
| 300-579 | Poor |
How often does your score update? Most creditors report to the bureaus about once a month, and your score is recalculated each time a lender pulls it – so it can move from month to month as balances and payment history change. And if you have little or no credit history (a “thin file” or “no score”), you are not automatically shut out: some programs allow manual underwriting using alternative records like rent, utilities, and insurance payments, and the newer scoring models discussed below are designed to score thin files more fairly.
What Credit Score Do You Need for a Delaware Mortgage?
This is the question that matters most if you are buying a home. Each loan program sets its own credit requirements, and individual lenders can layer additional requirements (called overlays) on top. The table below shows the general program guidelines – your real-world approval always depends on your full picture, including income, debt, down payment, and reserves.
| Program | Typical Credit-Score Guideline | Notes |
|---|---|---|
| FHA | 580 with 3.5% down (500-579 may be possible with 10% down) | Many lenders set an overlay around 600-620 |
| VA | No VA-set minimum | Lenders commonly look for roughly 580-620 |
| USDA | 640 for automated approval | Manual underwriting may be possible below 640 |
| Conventional | No fixed minimum for files approved through automated underwriting; 620 commonly applies to manually underwritten loans | Fannie Mae dropped its 620 floor in Nov 2025; lenders and PMI companies may still set their own minimums |
| DSHA Welcome Home | 620 | This is a published DSHA program guideline |
One 2026 update is worth flagging on the conventional side. In November 2025, Fannie Mae removed the long-standing 620 minimum from its Desktop Underwriter system, and Freddie Mac made a similar change – so a file can now receive an automated conventional approval without clearing a hard 620 score cutoff, based on the full risk profile instead. That is real progress, but here is the part most headlines miss: a low-score conventional loan can still cost more than FHA once you factor in the interest rate and mortgage insurance, so “approved” and “best deal” are not always the same loan. That is exactly the kind of comparison I run with you.
A few practical takeaways for Delaware buyers. If your score is in the upper 500s, an FHA loan is usually the most accessible path. If your score is 620 or higher, you also open the door to DSHA Welcome Home and the down payment assistance programs that pair with it. If you are not sure which program fits, that is exactly the kind of question I can answer in a short call.
How Do Mortgage Lenders Use Your Credit Score?
Mortgage lenders use your credit a little differently than a credit-card issuer does, and the differences surprise a lot of buyers:
- All three bureaus, representative score. We typically pull Equifax, Experian, and TransUnion and use a representative score – most often your middle score. If two borrowers are on the loan, lenders generally use the lower of the two middle scores. The exact method can vary by loan program, scoring model, and underwriting system.
- Mortgage-specific scoring models. The score a mortgage lender sees often comes from older FICO models built for mortgage lending, which can differ from the FICO 8 or VantageScore you see in a free consumer app. Here is a closer look at mortgage FICO scores vs. online consumer credit scores and why they often do not match. Do not be alarmed if the number is not identical.
- Rate shopping is protected. Comparing several mortgage lenders within a short window counts as one inquiry, so shopping for the best loan does not punish your score.
2026 mortgage credit-score update: For decades, mortgage lenders relied on Classic FICO models. On April 22, 2026, the Federal Housing Finance Agency (FHFA) and HUD announced that Fannie Mae, Freddie Mac, and the FHA will accept VantageScore 4.0 and FICO 10T alongside Classic FICO. VantageScore 4.0 is available now through a limited rollout to approved lenders for eligible conventional loans, while Classic FICO remains approved. FICO 10T is approved for future use – the FHFA expects to publish historical FICO 10T data in summer 2026, with lender adoption at a later date. Both newer models use 24 months of “trended” credit data and can factor in on-time rent, which may help some thin-file borrowers. The practical takeaway: the score and model used can vary by lender, program, and underwriting system during this transition. Current as of June 2026.
Here is how the most common scores compare for a mortgage:
| Score Type | Where You Usually See It | Used for a Mortgage? |
|---|---|---|
| Classic FICO (FICO 2, 4, 5) | Pulled by mortgage lenders (tri-merge) | Yes – the traditional mortgage score |
| FICO 8 / FICO 9 | Many credit cards and free apps | Not the classic mortgage score |
| VantageScore 3.0 / 4.0 | Credit Karma and many free apps | VantageScore 4.0 is now approved for eligible conventional loans (2026 transition); 3.0 is not a mortgage score |
| FICO 10T | Newer trended-data model | Approved; broader mortgage use phasing in |
Program guideline vs. lender overlay: A program guideline is the minimum a loan program (FHA, VA, USDA, DSHA, Fannie Mae, Freddie Mac) sets. A lender overlay is an extra requirement a particular lender adds on top – for example, FHA program rules allow 580, but a lender’s overlay may require 620. Two lenders can quote the same program differently because of overlays, which is why a turn-down at one lender is not always a turn-down everywhere.
Once you are under contract, treat your credit as frozen in place. Opening a new account, financing furniture, or even co-signing for someone else can change your score or your debt-to-income ratio enough to affect your approval. Our guide to mortgage loan do’s and don’ts covers exactly what to avoid between application and closing, and our explainer on your monthly mortgage payment shows how your rate ties back into the payment you will actually make.
How Can You Improve Your Credit Score Before You Apply?
You do not need a perfect score to buy a home, but a few targeted moves can lift your number and improve your loan terms. Most of these map directly back to the five factors above:
- Make every payment on time – this protects the largest factor (35%).
- Pay revolving balances down before the statement date and keep utilization low (the 30% factor that moves fastest).
- Avoid opening or closing accounts in the months before you apply.
- Leave old accounts open to preserve your length of history and available credit.
- Check all three reports for errors and dispute anything inaccurate.
When a borrower is just a few points away from a better rate tier or a program threshold, there is also a lender tool called a rapid rescore that can update corrected information in a matter of days rather than a full billing cycle. It only works with verifiable, legitimate changes – it is not credit repair – but for the right buyer it can be the difference between qualifying now and waiting. A national online calculator cannot do that for you; a one-on-one review can. The best first step is to let me look at your actual credit with you, because the right move depends on what is in your file.
A Delaware Borrower Example
Here is a realistic illustration of how this plays out. A Delaware buyer comes to me with a 605 mortgage score, about $6,000 in credit-card balances, and roughly 42% utilization across their cards. By paying those revolving balances down before the statement dates, they may lower their utilization and open up more loan options – sometimes within a single billing cycle. At the same time, depending on income, debt, and the program, they may already qualify at 605 today through FHA, so we look at both paths in parallel rather than waiting on the score alone. This is an illustration, not a quote – your actual numbers, the program, and a full underwriting review drive the real outcome.
Common Credit Mistakes Before a Mortgage
Most of the credit problems I see in the weeks before a closing are avoidable. The most common ones:
- Opening a new furniture, appliance, or store account before closing.
- Closing old credit cards (which can raise utilization and shorten your history).
- Paying off a collection without guidance, which can occasionally do more harm than good.
- Co-signing for someone else, which adds the debt to your profile.
- Moving balances between cards right before applying.
- Assuming the score in a consumer app is the same as your mortgage score.
A Step-by-Step Credit Review Process
When a Delaware buyer asks me to look at their credit before applying, here is the process we follow:
- Pull all three credit reports (you can get them free each week at AnnualCreditReport.com).
- Identify errors and high-utilization accounts.
- Compare your current mortgage scores with the program guidelines you are aiming for.
- Prioritize changes that may help without creating new risk.
- Recheck the file before pre-approval or underwriting.
How Do You Apply for a Delaware Mortgage Loan?
If you are ready to find out where your credit stands and which Delaware home loan fits your situation, the John Thomas Team is here to help. You can apply online, schedule a 30-minute call, or call us directly at 302-703-0727. We also teach free Delaware first-time home buyer seminars where credit readiness is one of the most-asked topics. Either way, we will review your credit with you, explain what is helping and what is holding you back, and map out a clear plan – whether that means applying today or taking a few weeks to position your file first.
Let’s turn your credit into a clear plan to buy.
I’ll review your three credit scores with you, explain what’s driving them, and show you which Delaware loan programs you may qualify for, based on your credit, income, debt, property, and a full underwriting review.
Frequently Asked Questions About Credit Scores
What credit score do I need to buy a house in Delaware?
It depends on the program. FHA loans generally start at a 580 credit score with 3.5% down, DSHA Welcome Home generally requires 620, and USDA looks for 640 for automated approval. Conventional loans no longer have a fixed minimum through Fannie Mae’s automated underwriting (the 620 floor was removed in late 2025), though 620 still commonly applies to manually underwritten loans and many lenders keep their own minimums. VA does not set a minimum, though lenders usually look for roughly 580 to 620. Your full profile – income, debt, down payment, and reserves – also matters, so the best way to know is to have your credit reviewed.
Will checking my own credit hurt my score?
No. Checking your own credit is treated as a soft inquiry and never affects your FICO score, no matter how often you do it. Only hard inquiries from new credit applications can lower your score, and even those usually cost just a few points.
Will shopping for a mortgage with multiple lenders hurt my credit?
Not in a meaningful way. FICO treats multiple mortgage inquiries made within a focused shopping window – generally 14 to 45 days depending on the scoring model – as a single inquiry. That means you can compare lenders to find the best loan without stacking up separate dings on your score.
Do my income, job, or bank balance affect my credit score?
No. Your income, employment status, job history, and bank account balances are not part of the FICO scoring formula. They can affect whether a lender approves your mortgage, but they do not move the credit score itself.
How far back do mortgage lenders look at my credit?
Mortgage lenders review your full credit report, but recent activity matters most. Late payments and most negative items can stay on your report for up to seven years, and a Chapter 7 bankruptcy can stay for up to 10 – though the impact of older items fades as newer positive history builds. Lenders also look closely at the last 12 to 24 months of payment activity.
Do medical collections affect my mortgage approval?
Less than they used to. Under voluntary bureau changes still in effect in 2026, paid medical collections are removed regardless of balance, unpaid medical collections with an initial reported balance under $500 are excluded, and the bureaus wait a year before a medical collection can appear at all. Unpaid medical debt over $500 can still be reported. If a medical bill has been on your file, it is worth having your credit reviewed before you assume it will be a problem.
Should I pay off a collection before applying for a mortgage?
Sometimes, but not always – it depends on the loan program and the age and type of the collection. Paying off the wrong account at the wrong time can occasionally do more harm than good, and some programs do not require certain collections to be paid. Before you pay anything, let me review your file so we make the move that actually helps your approval.
How long does it take to improve my credit score before buying?
Some factors move quickly and some move slowly. Lowering your credit utilization by paying down card balances may improve your score within a single billing cycle, while building payment history takes longer because each month adds only one data point. When a buyer is just a few points from a better rate tier, a lender rapid rescore can sometimes update corrected information in days rather than weeks.
Can I get a mortgage with a 580 or 600 credit score in Delaware?
Often, yes. A 580 credit score generally opens the door to an FHA loan with 3.5% down, which is the most common path for Delaware buyers who are still building credit, and a 600 score may also work for FHA and – since Fannie Mae removed its 620 automated-underwriting floor in late 2025 – potentially for conventional financing. Keep in mind that some lenders apply an overlay that sets a higher minimum, and your income, debt, and down payment all factor into the final approval.
Why is my mortgage credit score different from the score in my app?
Mortgage lenders pull all three bureaus and use your middle score, and the score often comes from older FICO models built specifically for mortgage lending. The free score in a consumer app is frequently a FICO 8 or VantageScore, which can differ from the mortgage version. A difference between the two numbers is normal and not a cause for concern. Our guide to mortgage FICO scores vs. online consumer credit scores explains why the two differ.
About Your Loan Officer
John R. Thomas is a Certified Mortgage Planner with the John Thomas Team at Primary Residential Mortgage, Inc., based at the Newark, Delaware office. For more than 20 years he has helped Delaware and Maryland buyers understand their credit and qualify for the right loan – including thousands of first-time buyers who started out worried that their credit score would hold them back.
John is the author of “Your Guide to Buying Your First Home in Delaware” and teaches free first-time home buyer seminars across the state. Credit is one of the topics he is asked about most, because a clear plan for the five factors above is often what turns a “not yet” into an approval. Learn more about John Thomas and the John Thomas Team.
Licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA). NMLS #38783.
John Thomas Team – Primary Residential Mortgage, Inc. | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | Schedule Appointment | YouTube channel | See our reviews on Google Business Profile (285 reviews, 4.8 stars).
Sources: myFICO – What’s in my FICO Scores (five-factor weights); FHFA – Credit Scores (2026 VantageScore 4.0 / FICO 10T transition); CFPB (consumer credit resources); AnnualCreditReport.com (free credit reports).
Last Updated: June 2026. Mortgage content reviewed by John R. Thomas, NMLS #38783.
John Thomas, NMLS #38783 | Primary Residential Mortgage, Inc. | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com | delawaremortgageloans.net
Copyright John R. Thomas, All Rights Reserved.
