Understanding Your Debt-to-Income Ratio (DTI) for a Delaware Mortgage

Debt-to-income ratio (DTI) is the share of your gross monthly income that goes toward your housing payment and recurring debts. Delaware lenders review a housing (front-end) ratio and a total (back-end) ratio. A common guideline is 31% housing and 43% total, but your real limit depends on loan type, credit, reserves, and automated underwriting findings – approval rests on the full file. Current as of June 2026.
If you are getting ready to buy or refinance a home in Delaware, your debt-to-income ratio is one of the biggest factors that decides how much you can borrow. I am John Thomas, NMLS #38783, and I have helped Delaware and Maryland buyers work through this number for more than 20 years from the office at 248 E Chestnut Hill Rd in Newark. The good news is that DTI is just arithmetic once you know what goes into it. Before we walk through it, it helps to understand the housing payment itself, because that payment is the centerpiece of both ratios – here is a plain-English breakdown of what makes up your monthly mortgage payment (PITI).
Quick Answer for Delaware Buyers:
Your DTI compares your gross monthly income to your monthly debt payments: DTI = monthly debt payments / gross monthly income x 100. Lenders calculate two ratios – housing (your new mortgage payment of principal, interest, taxes, insurance, and mortgage insurance, divided by gross income) and total (housing plus credit cards, auto loans, student loans, and other obligations, divided by gross income). A ratio at or below roughly 31% housing and 43% total is a common baseline, but FHA and VA programs may allow higher ratios when automated underwriting, residual income, compensating factors, and the full file support the decision. The only way to know your real number is to run it against the program you are using.
Find Out the Loan Amount Your DTI Supports
Get a clear, scenario-by-scenario look at the maximum payment your income can support across FHA, VA, USDA, and conventional financing.
Table of Contents
What Is a Debt-to-Income Ratio (DTI)?
Your debt-to-income ratio is the tool Delaware mortgage lenders use to decide how much you can borrow to purchase or refinance a home. It is simply a comparison of your gross monthly income to your monthly liability payments, written as a percentage. Lenders use it because it measures one thing the underwriter cares about most: whether the new payment fits comfortably inside your monthly cash flow. Lenders rely on two separate ratios when reviewing your file – your housing DTI and your total DTI.
Key terms in one place:
- Gross monthly income – your income before taxes and deductions, not your take-home pay.
- Housing DTI (front-end) – your full new housing payment divided by gross income.
- Total DTI (back-end) – housing plus all other monthly debt payments, divided by gross income.
- PITI and MI – principal, interest, property taxes, homeowners insurance, and mortgage insurance if it applies. This is the payment your housing DTI is built on.

How Is Your Housing DTI Calculated?
Your housing DTI – sometimes called the front-end ratio – compares your gross monthly income to your full new mortgage payment of principal, interest, property taxes, homeowners insurance, and mortgage insurance if it applies. Many Delaware buyers will also carry private mortgage insurance or an FHA mortgage insurance premium until they reach enough equity, and that amount is part of the housing payment the lender uses. Here is a sample calculation:
| Gross monthly income | $5,000 |
| New housing payment (PITI and MI) | $2,000 |
| Formula | Housing payment / Gross income x 100 |
| Math | $2,000 / $5,000 = 0.40 x 100 = 40% |
| Housing DTI | 40% |
In this example the housing payment is 40% of gross monthly income, so the housing DTI is 40%. This is an illustration only – it does not reflect any specific rate, payment, or approval.
How Is Your Total DTI Calculated?
Your total DTI – the back-end ratio – compares your gross monthly income to your new housing payment plus all the other monthly liabilities on your credit report, along with obligations that may not appear on credit such as judgment payments, tax liens, child support, or alimony. Here is a sample calculation that builds on the one above:
| Gross monthly income | $5,000 |
| New housing payment (PITI and MI) | $2,000 |
| Other monthly liabilities from credit report | $1,000 |
| Formula | (Housing payment + Other liabilities) / Gross income x 100 |
| Math | ($2,000 + $1,000) / $5,000 = 0.60 x 100 = 60% |
| Total DTI | 60% |
In this example the total DTI is 60%, meaning 60% of gross monthly income would go toward the housing payment plus other required monthly debt payments. A 60% total ratio is high for most programs, which is exactly why running your real numbers early matters – it tells us which loan type fits and whether paying down a debt before applying would open up more options.
What Is the Maximum DTI to Qualify for a Mortgage in Delaware?
There is no single maximum DTI that applies to every buyer. Several factors set the ceiling on each file, including loan type, credit score, automated underwriting approval, down payment, cash reserves, and whether you are using a Delaware down payment assistance program. The broad general guideline is 31% for the housing payment and 43% for total debt, often written as 31/43. A borrower at or below 31/43 is within a common qualifying baseline, which keeps the risk to the lender low – but that does not automatically mean the payment will feel comfortable, because take-home pay, child care, utilities, transportation, and savings goals still matter for your real budget. Most loan programs, though, will allow higher ratios than the general guideline when the rest of the file supports it. The table below summarizes the common upper ranges by loan type as of June 2026.
| Loan type | Common housing (front-end) DTI | Common total (back-end) DTI | Key condition |
|---|---|---|---|
| General guideline | ~31% | ~43% | Comfortable baseline for most buyers; you will also see the older 28/36 rule of thumb (see below) |
| FHA | 31% manual baseline | 43% manual baseline | Manual underwriting starts at 31/43 and allows higher ratios only with documented compensating factors; FHA’s automated system (TOTAL Scorecard) governs higher ratios on an Approve/Eligible result. There is no universal 57% FHA entitlement |
| VA | flexible | 41% benchmark but No Max | 41% is the underwriting benchmark; higher ratios may be possible when residual income, automated underwriting, and the full file support the decision. VA has No Max DTI. |
| Conventional | varies | ~36% manual, up to ~45-50% with AUS | Many conventional scenarios commonly start around a 620 qualifying score, but this varies by product, underwriting findings, and lender overlays; manually underwritten files are tighter, while a Desktop Underwriter approval with strong credit and reserves may allow more. Overlays can lower these |
| USDA | ~29% baseline | ~41% baseline | Stricter because there is no down payment; a GUS automated approval may allow more, while manual underwriting uses tighter baselines and requires documented compensating factors and a stronger score |
| Jumbo | varies | ~43% (investor-specific up to 55%) | No single agency maximum; varies by lender and product, and typically requires higher credit scores and a larger down payment |
Sources for the ratios above (current as of June 2026; lender overlays can be stricter): FHA – HUD Handbook 4000.1; VA – VA Lender’s Handbook (residual income); Conventional – Fannie Mae Selling Guide B3-6 / Desktop Underwriter; USDA – USDA Handbook HB-1-3555 / GUS; general definition – CFPB. Confirm current thresholds for your scenario.
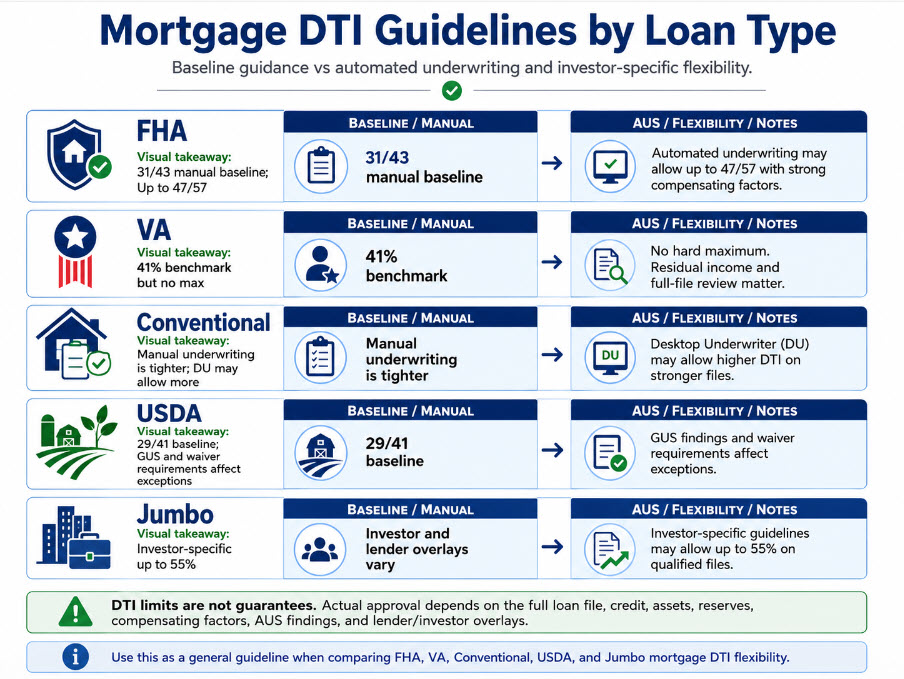
A few points are worth slowing down on, and the most important one is that almost every “maximum” depends on how the file is underwritten. Manual underwriting applies the program’s published baseline ratios, while automated underwriting (the AUS – Fannie Mae’s Desktop Underwriter, FHA’s TOTAL Scorecard, USDA’s GUS) can allow higher ratios when credit, reserves, and other factors are strong. So the same income can qualify at two different ceilings depending on the approval path. FHA starts at the 31/43 manual baseline and allows higher ratios only with documented compensating factors, or on an Approve/Eligible result from TOTAL Scorecard – there is no universal FHA maximum that applies to every borrower. VA uses 41% as its underwriting benchmark, but higher ratios may be possible when the veteran’s residual income, the AUS, and the full file support the decision. Conventional loans run tighter under manual underwriting (around 36%) and looser with a Desktop Underwriter approval, where strong credit and reserves matter. USDA commonly uses 29/41 baseline ratios, and a GUS automated approval is treated differently from a manually underwritten or Refer file, which determines whether higher ratios may be considered. Jumbo limits are set by the investor, not an agency. These are common guidelines, not guaranteed approval thresholds, and lender overlays can make any of them tighter; your real ceiling depends on your full file. Confirm current program thresholds with us before you rely on a specific number.
Why do I see both 28/36 and 31/43 online? Both are real guidelines, just from different programs. The older 28/36 rule is a conservative rule of thumb tied to conventional lending – 28% of gross income toward housing, 36% toward total debt. The 31/43 figures are FHA’s manual baseline and are a little more generous. Neither is a hard cutoff today, because automated underwriting routinely approves higher ratios when the rest of the file is strong. Treat 28/36 as the “comfortable” target and 31/43 as a common program baseline, then let the actual program and approval path set your real ceiling.
What this means for you: the same income can support very different loan amounts depending on which program you use. If your total DTI comes in high, an FHA or VA loan may keep the door open where a conventional or USDA loan would not. Choosing the right program around your ratio is one of the most valuable things we do together before you write an offer.
What Counts and What Does Not Count Toward Your DTI?
One thing that surprises many buyers is how little of their real budget actually shows up in DTI. The ratio your lender uses does not include every bill you pay, so it does not give you a complete picture of what you can comfortably afford to spend on a mortgage payment. Two details matter most here.
First, the lender uses your gross monthly income – your income before taxes and deductions – which is more than what you actually bring home. Second, the lender only counts debts that appear as monthly obligations, mainly on your credit report.
| Usually counted in DTI | Usually not counted in DTI |
|---|---|
| Proposed housing payment (PITI and mortgage insurance) | Groceries |
| HOA or condominium dues on the home you are buying | Utilities, gas, internet |
| Minimum credit card payments | Cell phone |
| Auto loans and leases | Car and health insurance |
| Student loan qualifying payment | Child care |
| Personal loans, HELOC, and co-signed loan payments | Retirement contributions |
| Court-ordered obligations (child support, alimony, judgments, tax liens) | Most other day-to-day living costs |
The exact treatment of any single item depends on your loan program and how it is documented. One useful detail: your current rent drops off once you buy, because the new housing payment replaces it.
Because so many real expenses are left out, I always encourage Delaware buyers to build a household budget alongside the DTI calculation. The lender’s ratio tells you the maximum the program will allow; your budget tells you the payment you will actually be happy with. The smartest buyers borrow somewhere below their ceiling, not right at it.
How Does Your Credit Score Affect Your Maximum DTI?
Credit score and DTI work together. On most programs, a higher credit score unlocks a higher allowable DTI, because the score is one of the compensating factors automated underwriting weighs. A conventional file, for example, may be held closer to 45% total DTI at a lower score but stretch toward 50% with a stronger score and reserves. USDA can be more flexible on its guideline ratios when the automated system (GUS) returns an approval and the score and reserves support it. If your ratio is on the edge, improving your score before you apply can sometimes be the difference between an approval and a decline – here is how the five factors of credit scoring shape the number lenders see. None of this is automatic; the score expands the room underwriting will allow, it does not guarantee a specific outcome. And while DTI itself does not change your credit score, and is not a direct pricing adjustment by itself, a higher DTI may affect which programs or loan structures are available to you. Credit score, down payment, property type, occupancy, and loan program are more direct pricing factors – and because credit score and down payment often move alongside DTI, the overall picture matters. Your DTI is also re-checked before closing, so taking on new debt mid-process can change both your approval and your terms.
How Can You Lower Your Debt-to-Income Ratio?
If your DTI is higher than the program you want will allow, you usually have more levers than you think. The two ways to move the ratio are to lower the monthly debt side or raise the documented income side. Common moves that may help, depending on your situation:
- Pay off or pay down a debt with a small balance. Eliminating a payment removes it from the ratio entirely. A car loan or credit card with only a few payments left can sometimes be paid off to qualify – we look at whether that money is better used here or toward your down payment.
- Avoid taking on new debt before closing. A new car, a furniture loan, or a fresh credit card opened during the process can push your ratio up and jeopardize the approval. Hold off until after you close.
- Document all qualifying income. Bonus, overtime, commission, part-time, or self-employment income may count when there is enough history. If you are self-employed, the way income is documented matters a great deal – here is how a self-employed Delaware mortgage qualifies.
- Add a qualified co-borrower. A spouse or family member with income and manageable debt can sometimes bring the combined ratio into range.
- Choose a more flexible loan program. Moving from a conventional or USDA loan to an FHA or VA loan can raise the allowable ratio on the same income.
- Increase your down payment. A larger down payment lowers the loan amount and the housing payment, which lowers the housing DTI directly.
Does Down Payment Assistance Affect Your DTI in Delaware?
Down payment assistance changes the cash you bring to closing, but it can also affect your ratios in ways worth planning for. Delaware State Housing Authority (DSHA) programs typically pair their down payment assistance with a first mortgage, and the structure of that assistance – whether it is a deferred second with no monthly payment or a repayable second – determines whether it adds a payment to your total DTI. Many DSHA assistance options are structured so they do not add a monthly payment, which keeps your back-end ratio clean while still reducing the cash you need. Because using a larger down payment lowers your loan amount and your housing payment, assistance can also indirectly improve your housing DTI. This is program-specific and changes from time to time, so we confirm the current structure for your situation. You can compare the current options on the Delaware down payment assistance programs page, and if you are buying your first home, the Delaware first-time home buyer guide walks through how the pieces fit together.
Common DTI Mistakes Delaware Buyers Make
- Assuming take-home pay is what counts. Lenders use gross income, so the number is usually friendlier than buyers expect – but it also means your real cash flow is tighter than the ratio suggests. Budget accordingly.
- Forgetting that the full housing payment is counted. Property taxes, homeowners insurance, and mortgage insurance are part of the payment the lender uses, not just principal and interest. In some Delaware areas, taxes and insurance can move the ratio meaningfully.
- Opening new credit during the process. A new monthly payment added before closing can break an approval that was fine at application.
- Borrowing right at the maximum. Just because a program allows a high ratio does not mean it is comfortable. Leave yourself room.
- Waiting until you are under contract to run the numbers. By then your options are narrower. Running DTI before you shop tells you your real price range and which program fits.
What this means for you: the best time to look at your DTI is before you start house hunting. A quick review now tells you the payment your income supports, whether a debt is worth paying off first, and which loan program gives you the most room – so you can write a confident offer.
Delaware Borrower Example: How Paying Off One Debt Changes Your DTI
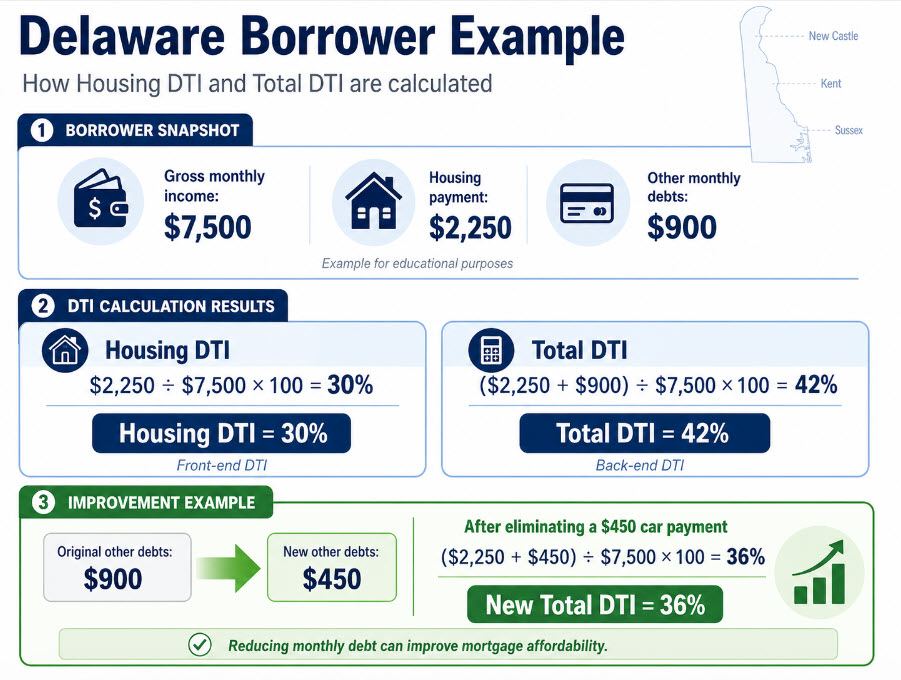
Numbers make this easier to see. Say a Delaware buyer earns $7,500 per month before taxes, the estimated housing payment is $2,250, and the buyer has $900 in car, student loan, and credit card payments.
- Housing (front-end) DTI: $2,250 / $7,500 = 30%
- Total (back-end) DTI: ($2,250 + $900) / $7,500 = 42%
- After paying off a $450 car payment: total monthly debt drops to $2,700, so total DTI falls to 36%
That single move can open up more loan-program options, though approval still depends on credit, income documentation, assets, property eligibility, and full underwriting review. One Delaware-specific wrinkle worth planning for: because the housing payment includes property taxes, the same home price can produce a different housing DTI in different counties – New Castle County property tax bills often run higher than Kent or Sussex County, which nudges the housing ratio up. We factor your actual county and tax estimate into the math before you write an offer. Figures here are an illustration only, not a quote or an approval.
How We Review Your DTI, Step by Step
When you call, here is the order we work through to find the program that gives your income the most room:
- Confirm your stable qualifying income and how it is documented.
- List your credit-report and non-credit-report monthly obligations.
- Estimate the complete housing payment – principal, interest, taxes, insurance, mortgage insurance, and any HOA or condo dues.
- Calculate your housing and total DTI.
- Compare the result across FHA, VA, USDA, conventional, and any applicable Delaware assistance programs.
- Decide whether paying off a debt, preserving reserves, or changing programs makes the most sense for you.
- Recheck your debts and income before closing, since a late change can affect both approval and terms.
Sources and Guidelines
The DTI ranges on this page reflect published agency and automated-underwriting guidelines, current as of June 2026. Program limits change, and lender overlays can be stricter. Primary references:
FHA: HUD Handbook 4000.1. VA: VA Lender’s Handbook (residual income). Conventional: Fannie Mae Selling Guide (B3-6, Desktop Underwriter). USDA: USDA Handbook HB-1-3555 (GUS). General definition: Consumer Financial Protection Bureau (CFPB). For your exact scenario, the right number is the one your loan file produces – call 302-703-0727 and we will run it.
Frequently Asked Questions About Debt-to-Income Ratio
What is a good debt-to-income ratio to buy a house in Delaware?
A common comfortable guideline is about 31% for your housing payment and 43% for total debt, often written as 31/43. At or below those numbers, most buyers have plenty of cushion. That said, FHA and VA loans regularly approve higher ratios when credit, reserves, and automated underwriting support the file. The right target depends on the program you use, so it is worth running your real numbers before you shop.
Can I get a mortgage in Delaware with a high DTI?
Often, yes. A high total DTI does not automatically disqualify you. FHA can allow higher ratios when automated underwriting returns an Approve/Eligible result or documented compensating factors support the file, and VA can go above its 41% benchmark when the veteran meets the residual income requirement for household size. The key is matching the right program to your ratio. Call 302-703-0727 and we can review which option keeps the door open for your situation.
Does the lender count my full credit card balance or just the minimum payment?
Lenders count the minimum monthly payment shown on your credit report, not the full balance. So a card with a large balance but a small minimum payment affects your DTI less than you might expect. If a card reports no minimum, the lender will typically use a small percentage of the balance as an assumed payment. Paying a card down before applying can lower or remove that monthly figure.
Do student loans in deferment count toward my DTI?
Usually yes, even when the loan is in deferment or forbearance. Different programs calculate the payment differently – some use the actual documented payment, some use a percentage of the balance, and some use the payment that would apply once repayment begins. Because the rules vary by loan type, an income-driven or deferred student loan can have a real impact on which program fits best. We confirm the exact treatment for your loans up front.
Can I use 1099 or self-employment income to qualify?
Yes. Self-employment, 1099, commission, and small-business income can all count when there is enough documented history, typically through tax returns or, on some programs, bank statements. Because the income side of your DTI is what self-employed documentation establishes, how it is presented matters. Our Delaware self-employed mortgage page explains how this income is calculated and which programs fit different business types.
Will paying off a car loan help me qualify?
It can, especially if the car payment is large or the loan has only a few payments left. Paying off a debt removes that monthly payment from your total DTI entirely, which can move you back under a program limit. Before you do it, though, we look at whether that cash is better used toward your down payment or reserves. Sometimes paying off the debt helps; sometimes keeping the cash helps more.
Does down payment assistance lower my DTI?
It depends on how the assistance is structured. Many Delaware DSHA assistance options are set up as a deferred second with no monthly payment, which keeps your total DTI clean while reducing the cash you need at closing. Because a larger down payment also lowers your loan amount and housing payment, assistance can indirectly improve your housing DTI as well. We confirm the current structure of each program for your specific scenario.
Do utilities, groceries, and insurance count in my DTI?
No. Your lender’s DTI only includes your housing payment and the monthly debt obligations on your credit report, plus court-ordered items like child support or alimony. Everyday costs such as groceries, utilities, gas, car insurance, cell phone, and child care are not counted. That is exactly why it is smart to build a household budget alongside the lender’s ratio so you choose a payment you are comfortable with, not just one the program allows.
Can a co-signer or co-borrower help me meet the DTI limit?
A qualified co-borrower can help in many cases. Adding a spouse or family member with income and manageable debt can bring the combined DTI into range, since the lender looks at both incomes and both sets of obligations. The co-borrower’s credit and debts factor in too, so it works best when their addition improves the overall picture. We can model it both ways to see whether it actually helps your file.
How is DTI calculated if I am self-employed and write off expenses?
For self-employed borrowers, lenders generally use net income after business write-offs from your tax returns, not gross revenue. Deductions that lower your taxable income also lower the income used to qualify, which can raise your DTI. Some programs add certain non-cash deductions like depreciation back to income. Because write-offs cut both ways, planning ahead matters – we review your returns and walk through the options before you apply.
About the Author: John R. Thomas
John R. Thomas is a Branch Manager and Mortgage Loan Officer in Newark, Delaware, and has helped more than 3,000 Delaware and Maryland families navigate qualifying questions like debt-to-income ratio for over 20 years. He holds a BS in Physics Education from the University of Delaware and an MS in Curriculum and Instruction from Delaware State University, and he wrote “Your Guide to Buying Your First Home in Delaware” to make the mortgage process clearer for local buyers.
John works directly with buyers to run real DTI numbers before they shop, so they know their true price range and which loan program gives them the most room. Licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA). NMLS #38783. The 17-state licensing is a professional credential; this site serves Delaware and Maryland buyers.
20+ Years | 3,000+ Buyers Helped | DE & MD | CMP
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com
Schedule Appointment (30 minutes) | YouTube | See John Thomas Team on Google
Not Sure Where Your DTI Lands? Let’s Run the Numbers Together.
In a quick conversation, I can tell you the payment your income supports, whether paying down a debt first would help, and which Delaware loan program gives you the most room. There is no cost and no pressure – just a clear answer.
Last Updated: June 2026. Mortgage content reviewed by John R. Thomas, NMLS #38783.
John Thomas, NMLS #38783 | John Thomas Team with AnnieMac Home Mortgage | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
Copyright John R. Thomas, All Rights Reserved. DTI ranges shown are common agency and automated-underwriting guidelines as of June 2026 and are not guarantees of approval; your maximum depends on your full file. This page is educational and not a commitment to lend.
John R. Thomas, NMLS #38783 | John Thomas Team with AnnieMac Home Mortgage | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
AnnieMac Home Mortgage is an Equal Housing Lender. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access.
(c) Copyright John R. Thomas, All Rights Reserved.
