
Doctor Mortgage Loans in Delaware for Physicians, Dentists, Residents, and Fellows
Doctor mortgage loans Delaware homebuyers ask about most often: how to qualify with student loan debt, whether you can use an employment contract before your first paycheck, and how much down payment you actually need. The PRMI Doctor Loan Program is a doctor mortgage loans Delaware option for eligible physicians, dentists, residents, fellows, and certain medical professionals who want to buy or refinance a primary residence with low or no down payment and no required private mortgage insurance. The program may offer up to 100% financing on loans up to $1,000,000 with a 720+ credit score, employment contract or offer letter qualification, and income-driven student loan payment treatment for qualified Delaware buyers, subject to full program guidelines and underwriting approval.
Current as of May 2026. Program guidelines, loan tiers, and credit requirements are reviewed and updated as PRMI publishes changes.
John Thomas helps Delaware medical professionals compare doctor mortgage loans against conventional, FHA, VA, and jumbo loan options so you understand your real down payment, student loan treatment, employment contract requirements, and cash to close before you make an offer. This can feel overwhelming when you are juggling student loans, a new role, and a fast-moving Delaware housing market — so we walk through your options step-by-step. If you are also weighing other Delaware loan programs, you can compare side-by-side on the Delaware Loan Programs page after you finish reviewing this guide.
Talk to John Thomas about your Delaware doctor loan options.
Free consultation. Same-day pre-approval available for qualified borrowers.
Call 302-703-0727 Schedule Appointment Apply Online Now
John Thomas, NMLS #38783 | Primary Residential Mortgage, Inc. | 248 E Chestnut Hill Rd, Newark, DE 19713
Table of Contents
Watch John Thomas explain the PRMI Doctor Loan Program, then review the eligibility, down payment, student loan, and cash-to-close rules below.
Delaware Doctor Mortgage Loan Quick Facts
| Doctor Loan Feature | PRMI Doctor Loan Program |
|---|---|
| Minimum Credit Score | 680 |
| 0% Down Available? | May be available up to $1,000,000 with a 720+ credit score |
| PMI Required? | No private mortgage insurance required |
| Maximum Loan Amount | Up to $2,500,000 with required down payment based on credit score and loan size |
| Employment Contract Accepted? | Yes, a signed employment contract or offer letter may be used |
| Student Loan Treatment | IBR, PAYE, or income-driven payment may be used in qualifying |
| Property Type | Primary residence only |
| Best For | Eligible physicians, dentists, residents, fellows, veterinarians, podiatrists, and optometrists |
Can You Qualify for a Doctor Mortgage Loan in Delaware?
You may qualify for a Delaware doctor mortgage loan if at least one occupying borrower holds an eligible medical license, meets credit and income guidelines, and is buying or refinancing a primary residence. This program is often helpful for residents, fellows, new attendings, dentists, veterinarians, and practicing doctors who have strong income potential but do not want to wait until they save a 20% down payment.
Here’s what that means for you: you may still qualify even if you have large student loans, are starting a new job in the next 60–90 days, or have not saved a large down payment. The key is reviewing your credit score, employment contract, student loan payment, property type, and estimated cash to close before you start making offers.
Who Qualifies for the Delaware Physician Mortgage Program?
At least one occupying borrower must hold an active, valid license in an eligible medical field. Program guidelines can change, so John Thomas will verify your license type and full eligibility before you apply.
- Medical Doctor (MD)
- Doctor of Osteopathy (DO)
- Doctor of Dental Surgery (DDS)
- Doctor of Dental Medicine (DMD)
- Doctor of Optometry (OD)
- Doctor of Podiatric Medicine (DPM)
- Doctor of Veterinary Medicine (DVM)
Not eligible for this specific PRMI Doctor Loan Program: chiropractors, pharmacists, nurse practitioners, and physician assistants. If you are in one of those fields, you may still have other strong mortgage options. You can review the Nurses Mortgage Loan Program, or ask John Thomas to compare FHA, conventional, VA, jumbo, and available assistance programs side-by-side.
Additional requirements: the borrower must be actively practicing in the eligible profession and must have either completed residency within the last 10 years or currently be a resident, fellow, or intern. U.S. Citizens and Permanent Residents are eligible for this program. Non-permanent residents should ask about other mortgage options.
Doctor Loan Credit Score and Down Payment Requirements
The PRMI Doctor Loan uses credit score and loan amount to determine the required down payment. A higher credit score may allow a lower down payment. Here’s what that means for you: if your credit score is 720 or higher, you may have more flexibility than you would with many conventional or jumbo loan options.
720+ Credit Score
| Loan Amount | Down Payment Required | Maximum LTV |
|---|---|---|
| Up to $1,000,000 | 0% Down | 100% |
| $1,000,001–$1,750,000 | 5% Down | 95% |
| $1,750,001–$2,500,000 | 10% Down | 90% |
680–719 Credit Score
| Loan Amount | Down Payment Required | Maximum LTV |
|---|---|---|
| Up to $750,000 | 5% Down | 95% |
| $750,001–$1,500,000 | 10% Down | 90% |
| $1,500,001–$2,500,000 | 25% Down | 75% |
No private mortgage insurance is required on this Doctor Loan Program. That can help reduce the monthly payment compared with a conventional loan that requires PMI when the borrower puts less than 20% down. Exact savings depend on loan amount, credit profile, rate, property type, and available program terms at the time of your application.
Doctor Loan vs. Conventional Loan vs. Jumbo Loan in Delaware
Delaware physicians often compare the doctor loan against conventional and jumbo financing. The right answer depends on your credit score, down payment, student loan payment, contract income, and purchase price.
| Feature | PRMI Doctor Loan | Conventional Loan | Jumbo Loan |
|---|---|---|---|
| Minimum Down Payment | 0% may be available up to $1M with 720+ credit | 3%–5% may be available, usually with PMI below 20% | Often 10%–20%, depending on lender |
| PMI Required? | No PMI required | Usually required below 20% down | Usually no PMI, but stricter approval rules |
| Loan Amount | Up to $2,500,000 | Subject to conforming loan limits | Varies by lender and borrower profile |
| Maximum DTI | Up to 50% | Often lower, depending on automated underwriting | Often stricter |
| Employment Contract | May be accepted | May require current income documentation | May require current income documentation |
| Student Loan Treatment | May use actual IBR/PAYE payment | May use a calculated payment depending on program rules | Often stricter |
| Best For | Eligible medical professionals with student loans or limited down payment | Borrowers with lower loan amounts or strong savings | Higher-priced homes with strong assets and credit |
Doctor Loan vs. FHA Loan and VA Loan
A doctor mortgage loan is not always the only option. Some Delaware medical professionals may be better served by an FHA loan, VA loan, conventional loan, or jumbo loan.
Here’s what that means for you: if you are a veteran or active-duty medical professional, VA financing may be worth reviewing. If your credit score, license type, or residency status does not fit the PRMI Doctor Loan, FHA or conventional financing may still work. John Thomas will compare the real numbers so you can move forward with confidence.
Eligible and Ineligible Property Types
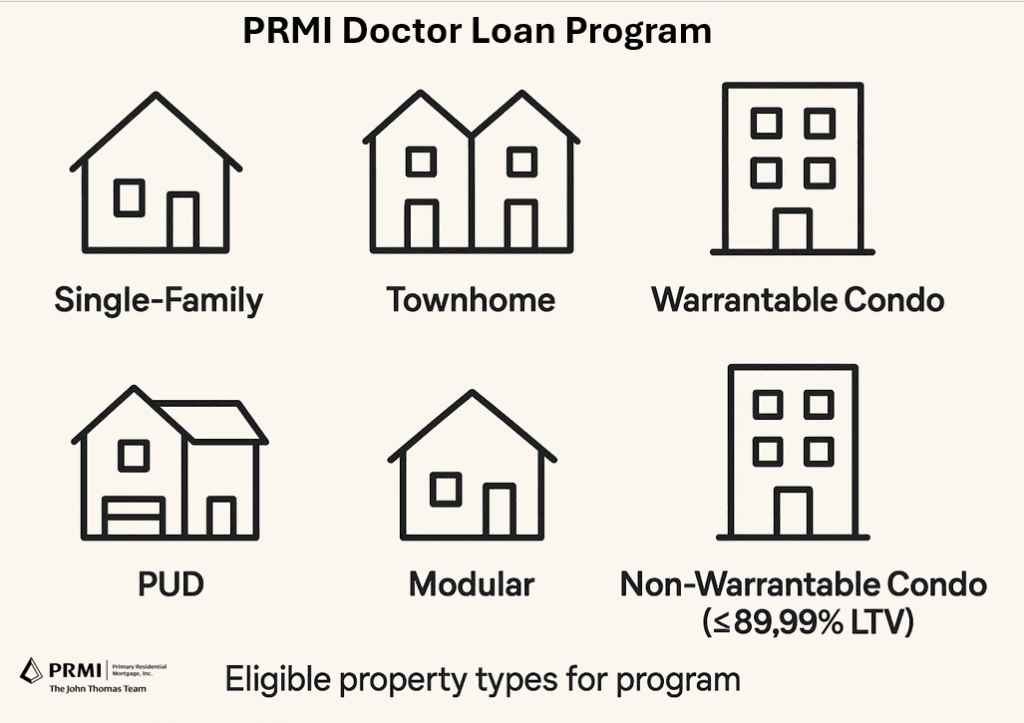
Eligible Property Types
- 1–2 unit primary residences, including single-family homes and duplexes
- Fannie Mae warrantable condominiums
- Planned Unit Developments, also called PUDs
- Townhomes
- Modular homes
- Non-warrantable condos, subject to additional loan-to-value limits
Ineligible Property Types
- Investment properties
- Second homes
- Manufactured homes
- Properties held in irrevocable trusts
Here’s what that means for you: the doctor loan is designed for your primary residence. If you are buying a rental property, vacation home, or manufactured home, we’ll review other financing options instead.
How Student Loans Are Handled on a Doctor Mortgage Loan
Student loan debt is one of the biggest reasons physicians worry they cannot qualify for a mortgage. The PRMI Doctor Loan Program may use your actual income-driven repayment amount, including IBR or PAYE, instead of using a larger calculated payment based only on the total student loan balance.
Here’s what that means for you: a Delaware physician with $250,000 or more in medical school debt may still qualify if the documented monthly payment fits the program rules. We’ll review your student loan statement, income documentation, and full debt-to-income ratio before you apply. Many conventional lenders use 0.5%–1% of the outstanding balance as the assumed monthly payment, which can add $1,400–$2,800 per month to your DTI calculation and knock you out of qualification — the doctor loan’s actual-payment treatment is often what makes the difference for residents and new attendings.
Employment Contracts and Offer Letters
A signed employment contract or offer letter may be used to qualify for the PRMI Doctor Loan Program. This can help residents, fellows, and new attendings who are relocating to Delaware or starting a new role before receiving their first pay stub.
Here’s what that means for you: you may not need to wait months after starting your new job before buying a home. We’ll review your start date, base salary, contract terms, and any required reserves so there are no surprises along the way.
What If I’m Paid 1099, wRVU, or Locum Tenens?
Many Delaware physicians are paid through 1099, work-relative-value-unit (wRVU) compensation plans, or locum tenens contracts rather than a straight W-2 base salary. Those structures can complicate qualifying because guaranteed base income is typically what underwriters lean on most heavily.
Here’s what that means for you: 1099 and wRVU income may still qualify for the PRMI Doctor Loan Program when properly documented, often using your guaranteed minimum salary, contract base, or hourly rate paired with stated minimum hours. Locum tenens income usually requires a stronger work history. We’ll review your contract structure, pay history, and tax returns before you make an offer so you know exactly which income components will count.
Relocating to Delaware From Out of State
Delaware attracts physicians relocating from Pennsylvania, New Jersey, Maryland, and beyond — often for new roles at ChristianaCare, Bayhealth, Nemours, or Beebe Healthcare. If you are still licensed only in your prior state, this is rarely a deal-breaker for the doctor loan, but timing matters.
Here’s what that means for you: the PRMI Doctor Loan Program generally requires that you be actively licensed and in or about to begin practice. Your Delaware medical license application timeline, your employment contract start date, and your move-in date all need to line up with closing. We’ll coordinate with your employer’s HR or credentialing team if needed so the loan file matches your actual transition. If you are buying before your start date, expect to document reserves, the signed contract, and any required pre-employment items.
Estimated Cash to Close on a Delaware Doctor Loan
One of the most common questions physicians ask is, “How much cash do I actually need?” The answer depends on your purchase price, credit score, down payment requirement, taxes, insurance, title costs, rate, and seller credits.
Here is a simple example for a $650,000 Delaware home purchase using a 0% down doctor loan option for a qualified borrower with a 720+ credit score.
| Item | Estimated Amount |
|---|---|
| Down Payment | $0 |
| Lender Origination / Fees | ~$1,500–$2,500 |
| Appraisal | ~$600–$900 |
| Title Insurance and Settlement | ~$2,000–$3,500 |
| Prepaid Interest | ~$1,000–$2,000 |
| Homeowners Insurance | ~$1,200–$1,800 |
| Property Tax Escrow | ~$1,500–$2,500 |
| Estimated Total Cash to Close | ~$8,000–$15,000 |
These are estimates only. Seller credits and gift funds may reduce your cash to close. Your actual Loan Estimate will depend on your full application, rate, purchase contract, taxes, insurance, and closing costs.
Gift Funds and Seller Contributions
- Gift funds may be allowed for down payment and closing costs from acceptable donors under program guidelines.
- Seller-paid closing costs may be allowed and must follow applicable interested party contribution rules.
- Non-occupant co-borrowers may be allowed when program requirements are met, including limits on how much of the total qualifying income may come from the non-occupant borrower.
Here’s what that means for you: even with a low down payment option, you still need to plan for closing costs, prepaid taxes, insurance, and reserves. We’ll walk through your cash-to-close estimate before you write an offer.
Pros and Cons of Doctor Mortgage Loans
Doctor mortgage loans can be a strong option, but they are not right for every borrower. A clear comparison helps you avoid buying too much house or choosing a loan only because it has a low down payment.
| Potential Benefits | Potential Drawbacks |
|---|---|
| Low or no down payment may be available | Lower down payment means less starting equity |
| No PMI can help lower the monthly payment | Rate and terms may differ from conventional financing |
| Employment contracts may be accepted | Program rules are more specific than standard loans |
| Flexible student loan treatment may help qualifying | Higher loan amount can create a larger monthly payment |
| Useful for residents, fellows, and new attendings | Not all medical professionals qualify |
Here’s what that means for you: the goal is not just to get approved. The goal is to choose a mortgage payment that fits your income, career stage, student loan plan, and long-term goals.
Real-World Example: Delaware Physician Using a Doctor Loan
Scenario: Dr. Sarah is a DO completing residency at ChristianaCare in Newark, Delaware. She has a signed employment contract for an attending position starting soon at a salary of $230,000 per year. She has $280,000 in student loans on an income-driven repayment plan, a 740 credit score, and $35,000 in savings.
With a conventional loan: the lender may require current income documentation, may count a larger student loan payment, and may require PMI if she puts less than 20% down.
With the PRMI Doctor Loan: her employment contract may be used, her documented income-driven student loan payment may be considered, and 0% down may be available if she meets the full program requirements.
This is the type of situation the doctor loan was designed to help solve. It does not guarantee approval, but it gives qualified Delaware medical professionals another path to consider.
Doctor Mortgage Loans Delaware Buyers Use Near Major Medical Employers
Many Delaware physicians and medical professionals search for homes near major healthcare employers and medical hubs, including ChristianaCare in Newark and Wilmington, Bayhealth in Kent County, Nemours Children’s Hospital, Beebe Healthcare near the beaches, and medical offices throughout New Castle, Kent, and Sussex County.
John Thomas helps buyers compare doctor mortgage loans based on where they are buying, how much they want to put down, whether they are relocating, and how their student loans are counted. This local guidance matters because Delaware buyers also need to understand property taxes, settlement costs, title timing, and local market conditions.
Local Delaware Areas Served
The John Thomas Team helps eligible medical professionals using doctor mortgage loans Delaware-wide, including Newark, Wilmington, Hockessin, Greenville, Pike Creek, Bear, Middletown, Smyrna, Dover, Milford, Lewes, Rehoboth Beach, Bethany Beach, and surrounding communities — and we also help qualified borrowers in nearby Maryland.
States Where the PRMI Doctor Loan Is Available
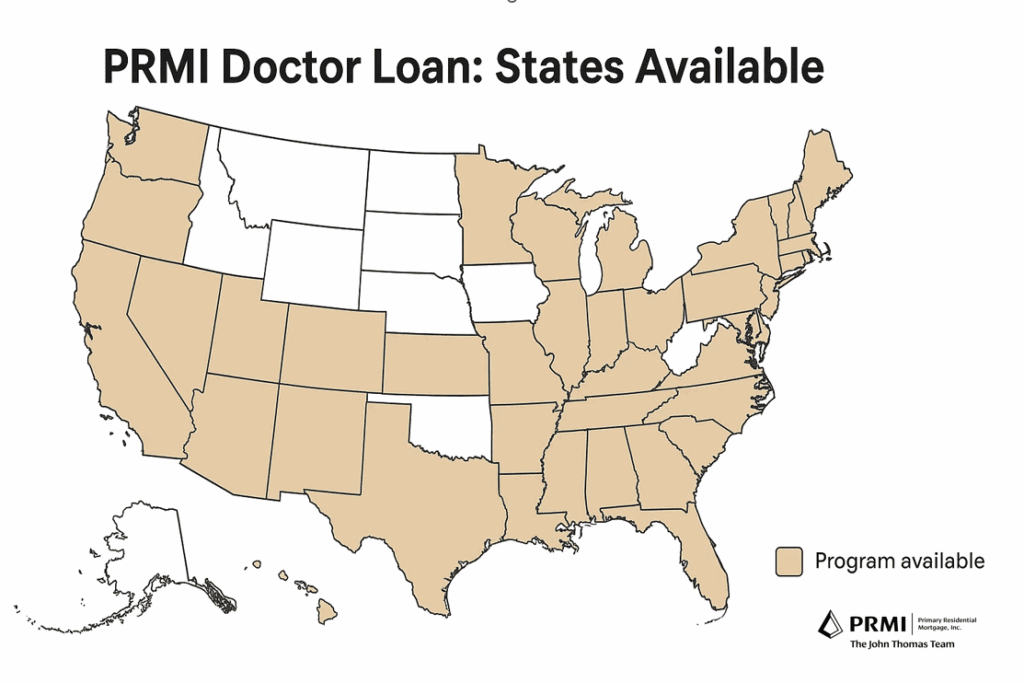
The PRMI Doctor Loan Program is available in 45+ states, which gives medical professionals flexibility when relocating within the Mid-Atlantic region. John Thomas works directly with Delaware-based physicians and is licensed to originate mortgages in Delaware, Maryland, and additional states (see the credentials block at the bottom of this page).
How to Apply for a Doctor Mortgage Loan in Delaware
The process is easier when you know what to expect. We’ll walk through everything step-by-step so you understand your options before you apply.
- Call or start online. Contact John Thomas at 302-703-0727, schedule a 30-minute appointment, or start your application online.
- Review your eligibility. We confirm license type, credit score, income, employment contract, student loans, property type, and down payment options.
- Gather documents. You may need ID, medical license, employment contract or pay stubs, bank statements, and student loan documentation.
- Get pre-approved. Once your file is reviewed, we work toward a strong pre-approval letter so you can shop with confidence.
- Make an offer. Your real estate agent can use your pre-approval when submitting offers in Delaware’s housing market.
- Move through processing and underwriting. Our team coordinates the loan file, appraisal, title, conditions, and closing communication.
- Review final numbers and close. You review your Closing Disclosure before settlement so there are no surprises at the table.
Common Mistakes Physicians Make When Applying for a Mortgage
- Waiting too long to get pre-approved. Delaware homes can move quickly. It is better to review your numbers before you begin making offers.
- Assuming student loans automatically disqualify you. You may still qualify when your income-driven student loan payment is handled correctly.
- Comparing only the down payment. A low down payment matters, but rate, payment, closing costs, PMI, and long-term goals matter too.
- Opening new credit before closing. New debt can change your approval. Ask before financing furniture, cars, or major purchases.
- Using a lender who does not understand physician income. Employment contracts, residency transitions, and student loans need careful review.
Visit Our Newark, Delaware Mortgage Office
The John Thomas Team is based in Newark, Delaware and helps buyers throughout Delaware and nearby Maryland. Call ahead to schedule a doctor loan review, pre-approval consultation, or mortgage planning appointment.
Primary Residential Mortgage, Inc. — John Thomas Team
248 E Chestnut Hill Rd
Newark, DE 19713
Phone: 302-703-0727
Website: DelawareMortgageLoans.net
Google Business Profile: See John Thomas Team on Google
FAQ — Delaware Doctor Mortgage Loans
What is a doctor mortgage loan in Delaware?
A doctor mortgage loan in Delaware is a specialized home loan for eligible physicians, dentists, residents, fellows, and certain medical professionals buying or refinancing a primary residence. The PRMI Doctor Loan Program may offer low or no down payment options, no PMI, employment contract qualification, and flexible student loan treatment for qualified borrowers.
Who qualifies for the Delaware physician mortgage loan?
To qualify for this specific program, at least one occupying borrower must hold an active eligible medical license, such as MD, DO, DDS, DMD, OD, DPM, or DVM. The borrower must be actively practicing or entering practice under acceptable program guidelines. Program rules can change, so John Thomas will verify your eligibility before you apply.
Can residents and fellows qualify for a doctor mortgage loan?
Yes, residents, fellows, interns, and new attendings may qualify if they meet the program requirements. A signed employment contract or offer letter may be used for income qualification, which can help medical professionals buy before receiving their first pay stub.
Can I get a doctor mortgage loan in Delaware after a Chapter 7 bankruptcy?
You may still qualify for a doctor mortgage loan after a Chapter 7 bankruptcy, but typically only after the standard waiting period has passed (often two to four years from discharge depending on the loan product) and you have re-established credit. The PRMI Doctor Loan Program reviews the discharge date, post-bankruptcy credit profile, and overall borrower file. We’ll review your specific timeline before you apply.
Can I use 1099 or wRVU income for a Delaware doctor mortgage loan?
Yes, 1099 income, wRVU compensation, and locum tenens earnings may be used to qualify when properly documented, often by leaning on guaranteed minimum salary, contract base, or stated minimum hours. The program typically wants to see a stable history. We’ll review your contract, pay history, and tax returns to confirm which income components will count toward qualification.
What if my employer just changed in the last 60 days?
A recent employer change is often manageable for the PRMI Doctor Loan, especially with a signed employment contract or offer letter. Underwriting will review your new role, salary, start date, and any required reserves. If you are still in the gap between roles, we’ll walk through documentation steps and timing so the loan file matches your actual transition.
How are student loans in deferment counted on a doctor mortgage loan?
Student loans in deferment may still count toward your debt-to-income ratio depending on the loan product and program rules. The PRMI Doctor Loan Program may use the documented income-driven repayment amount, even if that amount is low or $0. Loans in administrative forbearance or true deferment without a payment may still require a calculated payment for qualifying. We’ll review your most recent statement to confirm.
Can I use gift funds for my down payment or closing costs?
Yes. Gift funds may be allowed for down payment and closing costs when they meet program guidelines, including documentation of the donor relationship and the funds transfer. Seller-paid closing costs may also be allowed under applicable contribution limits. These options can help reduce the amount of cash you need at closing.
How much can I borrow with no money down?
Qualified borrowers with a 720 or higher credit score may be eligible for up to 100% financing on loan amounts up to $1,000,000. Larger loan amounts may require 5% to 10% down depending on the loan size. Borrowers with credit scores from 680 to 719 may need a larger down payment.
Is PMI required on a Delaware doctor loan?
No. Private mortgage insurance is not required on the PRMI Doctor Loan Program. This can help lower the monthly payment compared with conventional loans that usually require PMI when the borrower puts less than 20% down.
What property types are eligible for the doctor loan?
Eligible property types may include 1–2 unit primary residences, townhomes, warrantable condos, planned unit developments, modular homes, and some non-warrantable condos subject to additional limits. Investment properties, second homes, manufactured homes, and properties in irrevocable trusts are not eligible for this specific program.
How do I apply for a doctor mortgage loan in Delaware?
Call John Thomas at 302-703-0727, schedule a 30-minute appointment, or start your application online. The John Thomas Team will review your medical license, credit score, income, employment contract, student loans, property type, and estimated cash to close before moving forward with pre-approval.
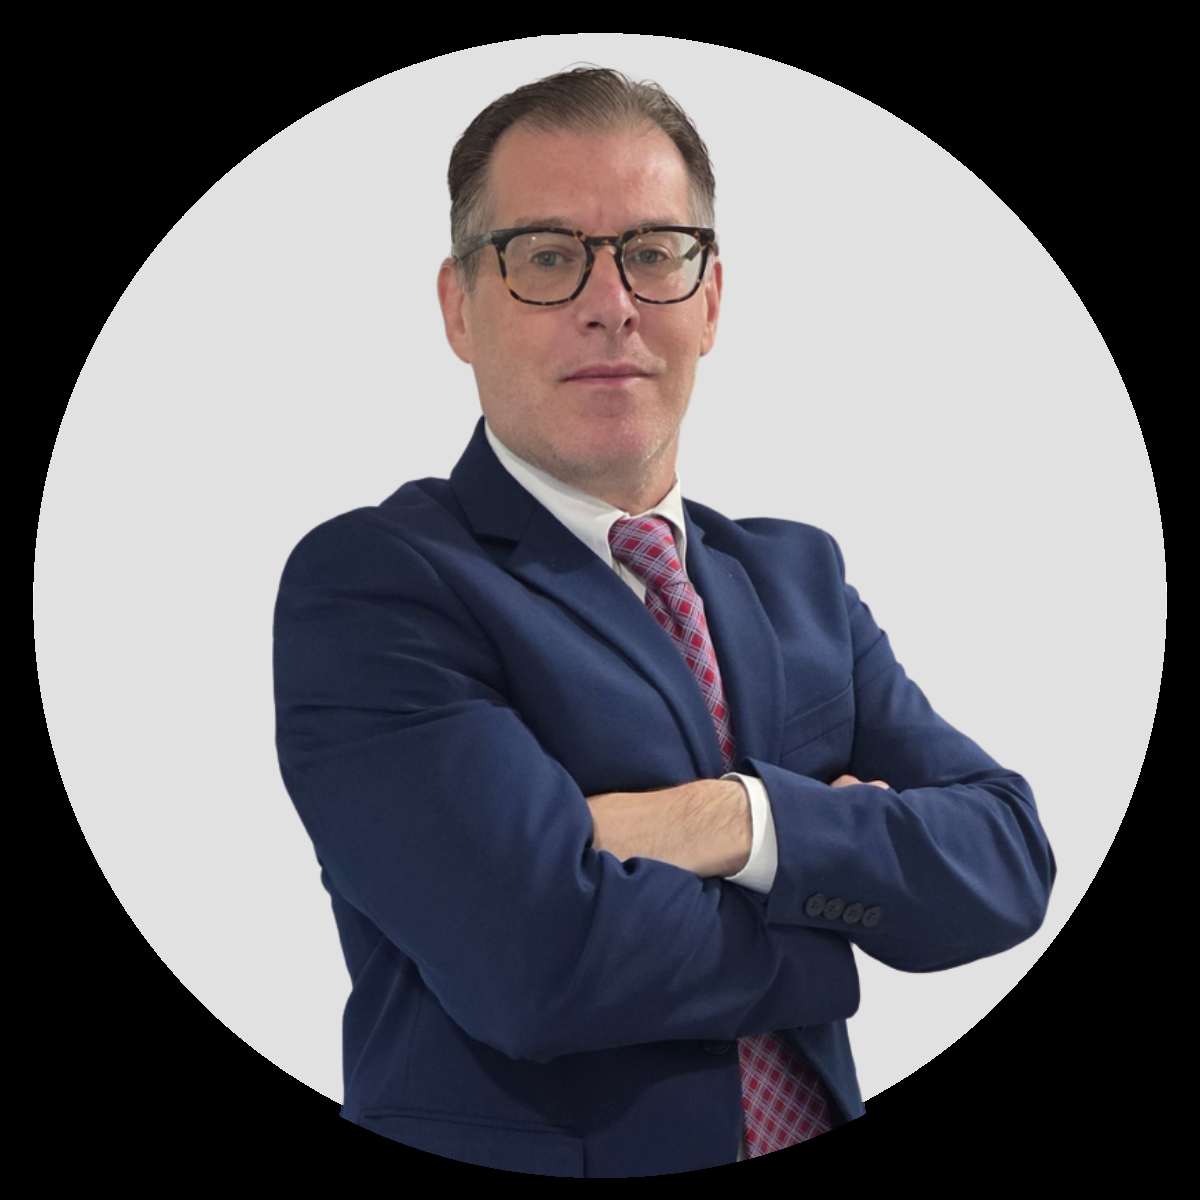
John R. Thomas
Branch Manager and Mortgage Loan Officer
Primary Residential Mortgage, Inc.
NMLS #38783 Physician Loan Specialist DSHA Approved Author
John R. Thomas is a Branch Manager and Mortgage Loan Officer with Primary Residential Mortgage, Inc., based in Newark, Delaware. He has spent more than 20 years originating mortgages for Delaware homebuyers — including hundreds of Delaware physicians, dentists, residents, fellows, and medical professionals navigating student loan debt, employment contracts, and relocations to ChristianaCare, Bayhealth, Nemours, and Beebe Healthcare.
John holds a Bachelor of Science in Physics Education from the University of Delaware and a Master of Science in Curriculum and Instruction from Delaware State University. He is the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826), and he runs a YouTube mortgage education channel with hundreds of plain-English videos walking Delaware buyers through doctor loans, FHA, VA, conventional, jumbo, DSHA programs, and more. His teaching background shapes how he explains complex loan structures to physicians who often only review one mortgage in their entire career.
Licensing: John Thomas is licensed as a mortgage loan officer in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA). NMLS #38783. Verify on NMLS Consumer Access. The PRMI Doctor Loan Program is available in Delaware and 45+ additional states; this page focuses on Delaware buyers.
John Thomas Team — Primary Residential Mortgage, Inc.
248 E Chestnut Hill Rd, Newark, DE 19713
Phone: 302-703-0727
Email: JohnThomasTeam@primeres.com
Schedule: Schedule Appointment
YouTube: youtube.com/@Delawaremortgage
Google Business Profile: See John Thomas Team on Google
Ready to Review Your Delaware Doctor Loan Options?
John Thomas and the PRMI team can review your eligibility, run your numbers, and help you understand whether a doctor mortgage loan, conventional loan, FHA loan, VA loan, or jumbo loan is the best fit. Delaware homes can move fast, so it is better to review your mortgage options before you begin making offers.
Talk to a Delaware Physician Mortgage Specialist Today
Free consultation. Same-day pre-approval available for qualified borrowers.
Helpful mortgage resources: Nurses Mortgage Loan Program | Home Town Heroes Grant Program | Delaware Jumbo Loans | Delaware Conventional Loans | All Loan Programs
Last Updated: May 2026 | John Thomas, NMLS #38783 | Primary Residential Mortgage, Inc. NMLS #3094 | Newark Branch NMLS #106170 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | JohnThomasTeam@primeres.com | delawaremortgageloans.net | Copyright John R. Thomas, All Rights Reserved.
