
Wilmington First Start Program: Up to $15,000 in Wilmington Down Payment Assistance for First-Time Buyers

Quick answer: Wilmington down payment assistance for first-time buyers comes mainly from the City’s First Start Program: a 0% forgivable loan of the lesser of $15,000 or 6% of the purchase price, forgiven only after 10 full years as your primary residence. It can stack with DSHA assistance. Current as of October 2026.
If you are buying your first home inside the City of Wilmington, the First Start Program is one of the most generous local down payment resources available to you. I am John Thomas, NMLS #38783, and The John Thomas Team has helped Delaware first-time buyers navigate down payment assistance for more than 20 years. First Start is a City of Wilmington program (separate from the statewide Delaware down payment assistance programs run through DSHA), and it is built specifically for buyers purchasing inside Wilmington city limits. If you are weighing your options across the whole Wilmington market, you may also want to read our Wilmington, Delaware mortgage guide. On this page I will walk through how much help you can get, who qualifies, the current income limits, and exactly how to apply.
Want to know if First Start fits your purchase?
Let’s review your eligibility and which programs you may qualify for, subject to full underwriting review.
Table of Contents
What Is the Wilmington First Start Down Payment Program?
The Wilmington First Start Program is the City of Wilmington’s down payment and closing cost assistance for first-time buyers purchasing inside city limits. It provides the lesser of $15,000 or 6% of the purchase price, secured by a City mortgage behind your first mortgage and forgiven after 10 years of owner occupancy.
The program is funded and administered by the City of Wilmington Department of Real Estate and Housing to promote homeownership inside the city. On its own, First Start records in second position, directly behind your first mortgage; when it is stacked with DSHA assistance it moves to third position (more on that below). You can review the official rules on the City of Wilmington First Start program page.
First Start is separate from the statewide DSHA programs. DSHA assistance is available across all of Delaware; First Start is available only for properties inside the City of Wilmington. The two programs are aimed at the same goal – getting first-time buyers into a home with less cash out of pocket – but they have different income limits, different assistance amounts, and different rules, which is why it helps to look at both before you choose.
How Much Down Payment Help Can You Get?
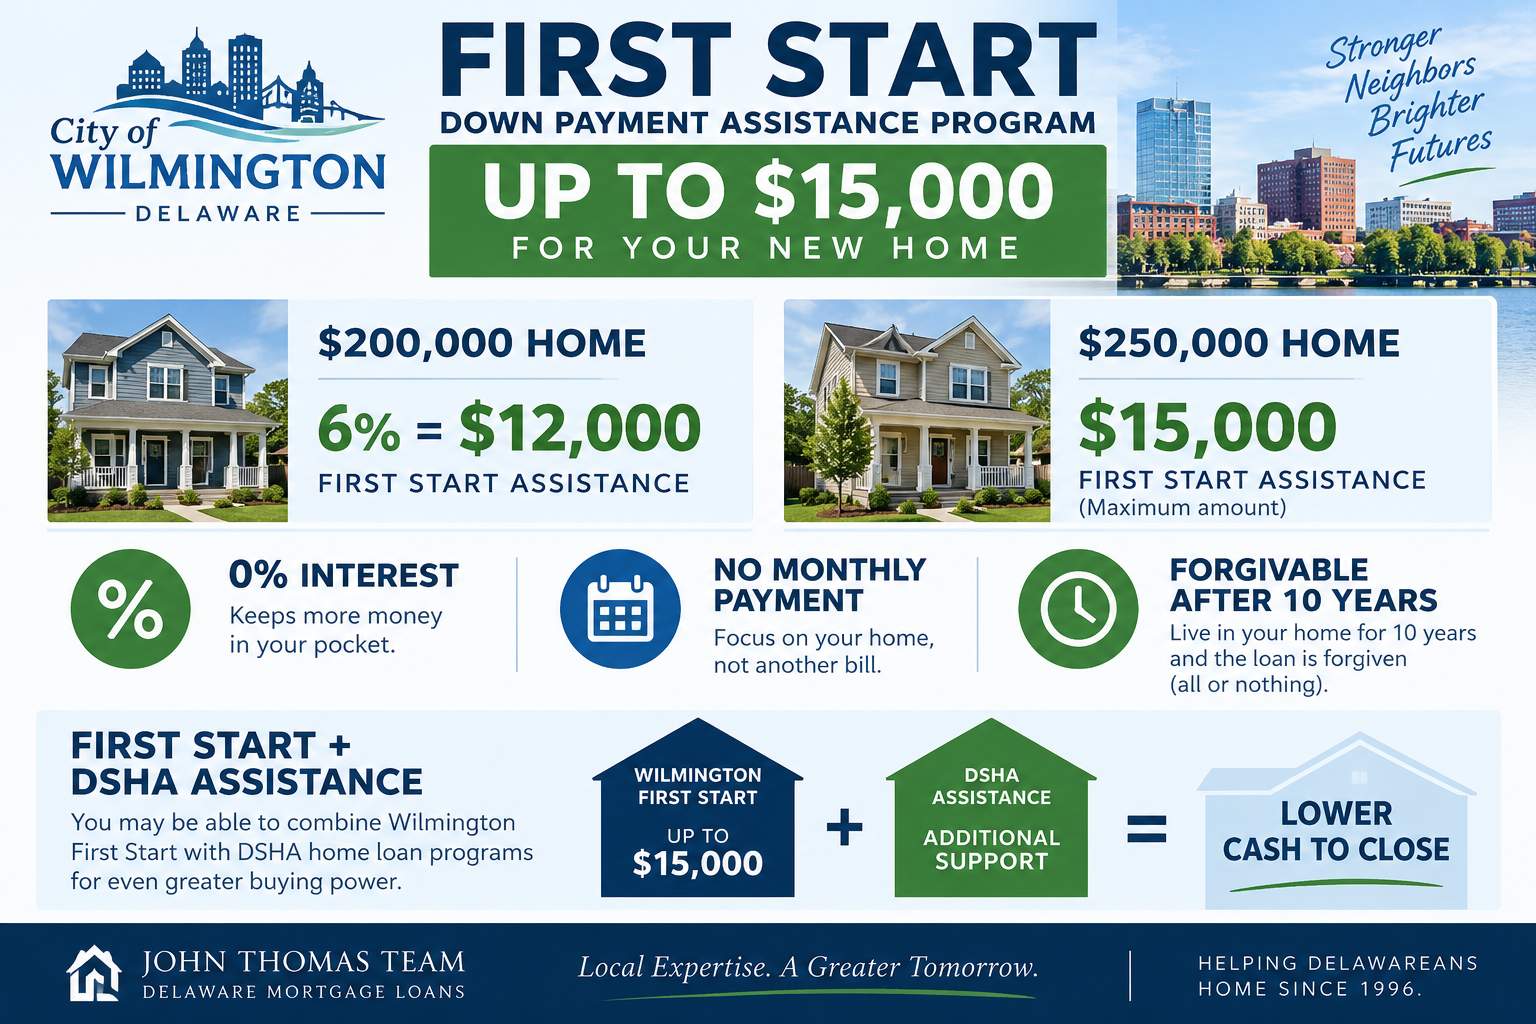
Wilmington First Start provides the lesser of $15,000 or 6% of the purchase price, as of October 2026. A $250,000 purchase reaches the $15,000 maximum; a $200,000 purchase receives $12,000. The final award is based on demonstrated need and on City funds being available when your completed application is submitted.
Plan on staying the full 10 years. Under the City’s terms, the First Start loan becomes payable in full if you sell or transfer the home, stop living in it as your primary residence, or fall behind on your mortgage, City property taxes, or water and sewer bills during the 10-year period. You confirm your occupancy to the City each year. There is no monthly payment on First Start in the meantime.
How the award is split. The City’s manual sets the down payment portion at no less than 25% and no more than 50% of your required down payment; the rest of the award goes to closing costs. The down payment portion is a 0% conditional loan, and the closing cost portion is a grant. In the City’s own example, a $240,000 appraisal with a $230,000 mortgage leaves a $10,000 down payment, so $2,500 to $5,000 of the award goes toward it. The award is sized from your lender’s Loan Estimate: if costs come in higher at closing, you cover the difference, and any unused funds go back to the City.
- Assistance amount: 6% of the purchase price, up to $15,000
- Structure: Down payment portion is a 0% conditional loan; closing cost portion is a grant; both secured by a City mortgage behind your first mortgage (no monthly payment)
- Forgiveness: Forgiven after 10 years of primary-residence occupancy; payable in full if you sell, move out, or fall behind on mortgage, City tax, or water and sewer payments before then
- Use of funds: Down payment and settlement (closing) costs; prepaid fees are not reimbursed
- Your contribution: Minimum $1,000 of your own funds toward settlement (gift funds do not count toward the $1,000); the City encourages buyers to put up to 3% of their own funds toward the down payment
First Start can be stacked with DSHA down payment assistance. Eligible buyers who also qualify for a DSHA program can combine First Start with up to an additional 5% in down payment assistance – for example, through DSHA Take5, which provides up to 5%. Stacking the two can meaningfully lower your cash to close. How much you can combine depends on your income, the programs’ rules, and the first mortgage you use, and is confirmed at application subject to full underwriting review.
Where First Start sits on the title. On its own, First Start records in second position, directly behind your first mortgage. When you stack it with DSHA down payment assistance, the DSHA loan takes second position – DSHA will only record in second – and First Start moves to third. Both setups are normal, and the First Start terms do not change.
First Start is subject to current program funding availability. Because it is funded by the City of Wilmington each program year, and each award is based on demonstrated need, it is a good idea to confirm that funds are still available when you are ready to write an offer. We can check current availability with you as part of your consultation.
Who Qualifies for the Wilmington First Start Program?
Most Wilmington First Start buyers qualify by being first-time buyers (no home owned in the past three years, with exceptions for displaced homemakers and single parents), buying a primary residence inside city limits, staying within the City income limits, finishing HUD counseling before signing a contract, and bringing $1,000 of non-gift funds.
Final eligibility is confirmed by the City of Wilmington at application. The full checklist:
- First-time buyer status: You must not have owned your primary residence at any point in the three years prior to settlement, except for displaced homemakers or single parents, who may still qualify.
- Primary residence: The home must be your primary residence – where you live more than 183 days a year (no investment or second homes).
- City limits: The property must be located inside the City of Wilmington.
- Lender: You do not have to use a particular lender, but your lender must accept the City’s loan terms in writing, including a fixed-rate first mortgage with a term of 30 years or less.
- Minimum contribution: You must contribute at least $1,000 of your own funds toward settlement costs. Gift funds do not count toward this $1,000.
- Demonstrated need: The City bases each award on demonstrated need, up to the program maximum.
- Homebuyer counseling: You must complete at least 8 hours of homebuyer counseling with a HUD-certified agency, before signing a sales contract or applying for a mortgage. The completion certificate is valid for one year.
- Income limits: Your household income must fall within the City of Wilmington limits for your household size (see the table below). The City counts the gross income of every adult in the household, not just the borrowers.
- Citizenship: You must be a U.S. citizen or permanent legal resident (green card holder).
- Reserves: The City’s manual says buyers should have liquid assets equal to about six months of housing payments left after closing.
- Ownership and current address: You must own the home after purchase. You do not need to live in Wilmington now to apply.
- Lead-based paint: A visual lead assessment must be completed on any home built before 1978. If it finds peeling or chipping paint, a lead test is needed and the hazards must be corrected before closing; if the seller refuses the test, the City will not fund the purchase.
- Home inspection: A home inspection by an American Society of Home Inspectors (ASHI) certified inspector must be completed and shared with the City, and major defects identified by the inspection must be repaired by a licensed contractor before closing.
- New construction: New construction homes must carry a one-year HUD-approved warranty.
Wilmington First Start Income Limits for 2026
First Start income eligibility is tied to the HUD median income for New Castle County by household size, and the City counts the gross income of every adult in the household under HUD’s Part 5 rules – a different test from DSHA, which counts only the borrowers. The City funds the program through two sources with two income tiers. The primary tier – funded through federal Community Development Block Grant (CDBG) dollars – serves households at or below 80% of the area median income. The figures below are the City of Wilmington’s published 80% limits, effective June 1, 2026. Current as of October 2026.
| Household Size | 80% AMI Income Limit (FY2026) |
|---|---|
| 1 Person | $68,750 |
| 2 People | $78,550 |
| 3 People | $88,350 |
| 4 People | $98,150 |
| 5 People | $106,050 |
| 6 People | $113,900 |
| 7 People | $121,750 |
| 8 People | $129,600 |
The City also funds a higher-income tier through its General Fund, which serves households up to 100% of the area median income (AMI). If your income is above the 80% limits shown above, you may still qualify under the General Fund tier while funds last. The City’s current posting lists $300,000 in CDBG funds for the 80% tier and $200,000 in general funds for the 100% tier. These are the City of Wilmington’s published 100% limits, effective June 1, 2026. Current as of October 2026.
| Household Size | 100% AMI Income Limit (General Fund Tier) |
|---|---|
| 1 Person | $85,900 |
| 2 People | $98,200 |
| 3 People | $110,500 |
| 4 People | $122,700 |
| 5 People | $132,600 |
| 6 People | $142,400 |
| 7 People | $152,200 |
| 8 People | $162,000 |
Because program limits and remaining funds change by program year, confirm your current eligibility with the City of Wilmington Department of Real Estate and Housing, or call us and we will check it with you. You can also review the program on the City of Wilmington Real Estate and Housing site.
What Homes Can You Buy with First Start?
Wilmington First Start is limited to single-family homes inside City of Wilmington limits that you will own and live in as your primary residence, as of October 2026: detached homes, semi-detached homes, and row homes. Condominiums are not among the City’s listed property types, and pre-1978 homes need a lead assessment.
- Single-family detached homes
- Semi-detached single-family homes
- Row homes (single-family attached)
First Start applies to homes inside the City of Wilmington limits – including areas like Trolley Square, the Highlands, Browntown, the East Side, and the Riverfront. Wilmington has a large stock of older row homes and townhouses, so the lead-based paint assessment and ASHI inspection requirements come up often. They are there to protect you as the buyer. If a home you love needs repairs to pass, that does not automatically end the deal – it just means the repairs need to be addressed before closing, and in some cases a renovation loan can help. We can talk through your options if the property you want needs work.
Which First Mortgage Programs Work with First Start?
First Start pairs with a fixed-rate FHA, VA, or conventional first mortgage with a term of 30 years or less, including the DSHA Welcome Home and Open Door first mortgages when you also want DSHA assistance. The best pairing depends on credit, income, cash available, and veteran status.
First Start is down payment assistance, not a first mortgage, so you choose a first mortgage to go with it. Your lender must accept the City’s loan terms in writing – a fixed interest rate and a term of no more than 30 years – and when a buyer’s debt-to-income ratio is above 45%, the City asks lenders to consider income from other household members as a compensating factor:
- FHA loans – low down payment and flexible credit guidelines, a common pairing for first-time buyers
- VA loans – for eligible veterans, active-duty service members, and surviving spouses, often with no down payment
- Conventional loans – a strong option when your credit and down payment are solid
The right first mortgage depends on your credit, your income, how much you want to bring to closing, and whether you are a veteran. Many Wilmington first-time buyers I work with qualify for more than one of these, so part of my job is helping you compare them side by side before you commit.
How First Start Compares to DSHA Down Payment Assistance
Many Wilmington buyers qualify for both First Start and the statewide DSHA down payment assistance programs. They are not always interchangeable, and in some cases you can stack a strategy across them. Here is how the main options compare at a high level:
| Program | Assistance | Where It Applies | Best For |
|---|---|---|---|
| Wilmington First Start | 6% of price, up to $15,000 (forgivable over 10 years) | City of Wilmington only | First-time buyers inside Wilmington city limits who meet City income limits |
| DSHA Keys4You | 4% of the first mortgage | Statewide (Delaware) | First-time and repeat buyers using DSHA Welcome Home or Open Door |
| DSHA First State | 3% of the first mortgage | Statewide (Delaware) | Buyers who want a smaller, lower-cost DPA option |
| DSHA Take5 | 5% of the first mortgage | Statewide (Delaware) | DSHA Welcome Home first-time buyers wanting the largest DSHA DPA |
If you are buying inside Wilmington, First Start is often the headline program because the assistance is a flat dollar amount tied to the purchase price rather than a percentage of the loan, and it is forgivable. But in many cases you do not have to choose – eligible buyers can combine First Start with a DSHA down payment assistance program for up to an additional 5% in help, on top of the First Start amount, with First Start moving to third position behind the DSHA loan (DSHA assistance is paired with a DSHA Welcome Home or DSHA Open Door first mortgage). The right setup depends on your income, your purchase price, and which first mortgage you use, and we map out which combination leaves you with the lowest cash to close.
When the Wilmington First Start Program Is Not a Good Fit
First Start is a strong program for the right buyer, but it is not the best path for everyone. It may not be a good fit if:
- You are buying outside the City of Wilmington. First Start only applies inside the city limits. If your home is in the suburbs or elsewhere in New Castle County, look at the New Castle County DPS program and the statewide Delaware down payment assistance programs instead.
- Your household income is above both the 80% and 100% City tiers. If you are over the income limits, a conventional loan with a smaller down payment or a different DPA strategy may serve you better.
- You are not planning to stay 10 years. The forgiveness clock runs 10 years. If you expect to move or sell sooner, the First Start loan becomes payable in full, which can change the math.
- You are buying an investment property, second home, or condominium. First Start is for single-family primary residences only.
- You plan a cash-out refinance within 10 years. The City will subordinate its loan for a refinance that lowers your rate, but not for a cash-out refinance.
- You are not a U.S. citizen or permanent legal resident. The City requires one or the other. If you file taxes with an ITIN, ask us about other financing paths.
- You need to close very quickly. The required HUD counseling, lead assessment on pre-1978 homes, and ASHI inspection add steps. They are worth it, but they take time, so a fast-closing situation may not line up.
If any of these describe your situation, that is fine – it usually just means a different program fits better, and we can point you to it.
How to Apply for the Wilmington First Start Program
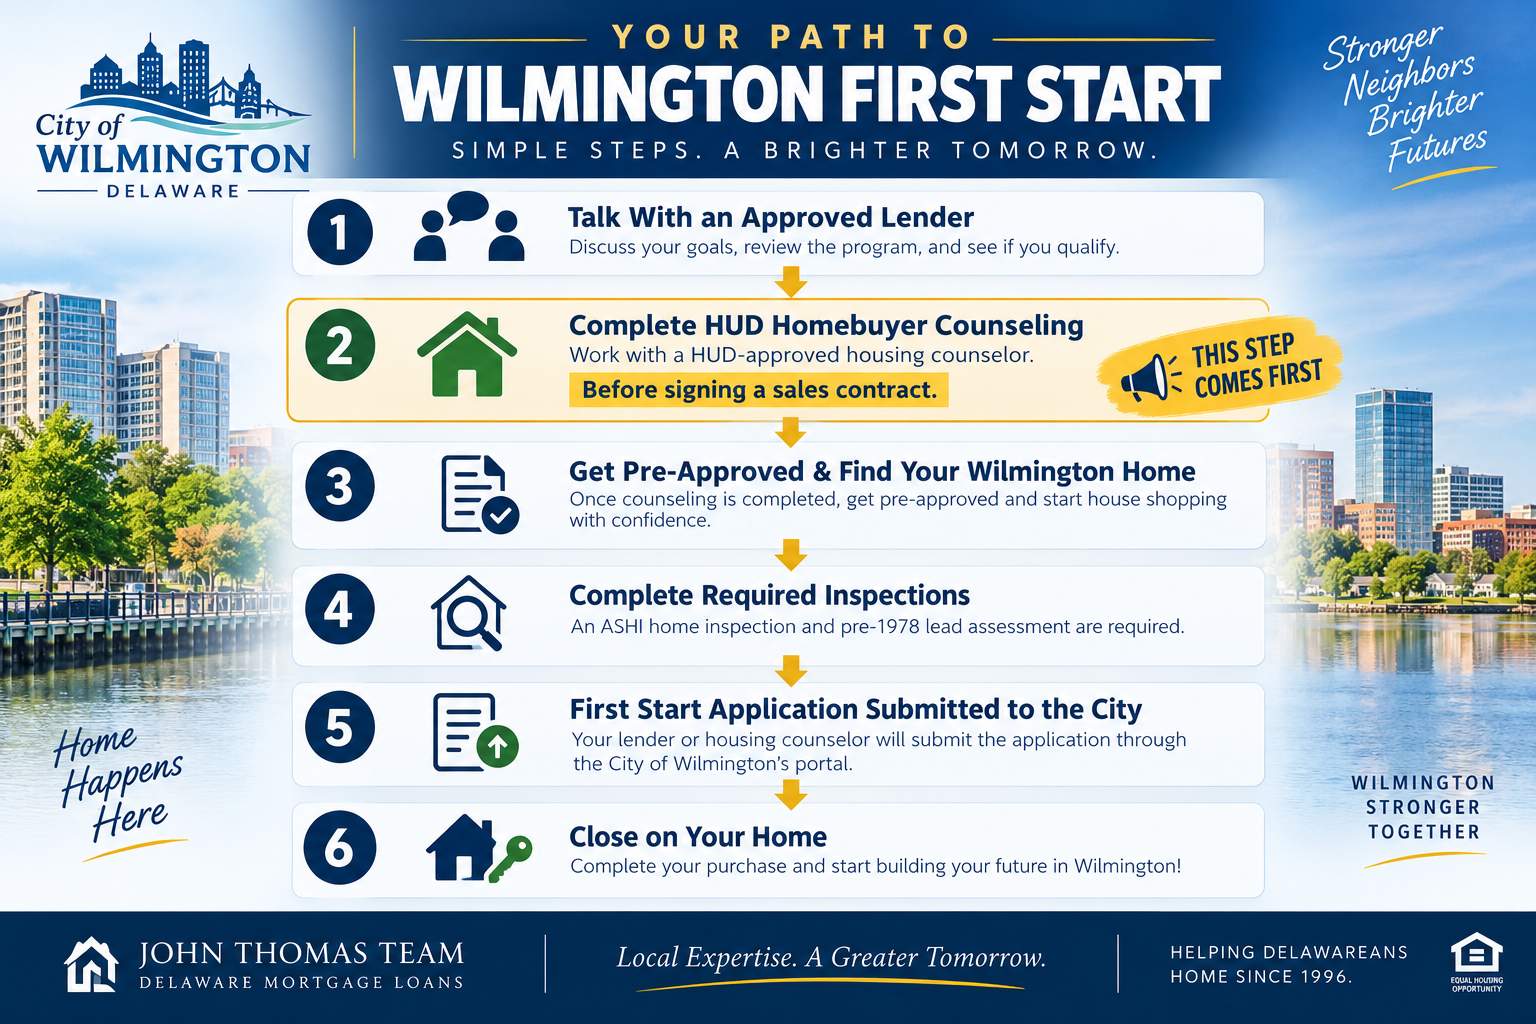
Here is the typical path to using First Start. The order matters: complete your HUD-approved homebuyer counseling before you sign a sales contract – completing it afterward can make you ineligible.
- Talk with a lender that works with First Start first. Call The John Thomas Team so we can review your income, credit, and the price range that works for you, and confirm whether First Start funds are currently available.
- Complete HUD-approved homebuyer counseling. At least 8 hours with a HUD-certified agency, before you sign a sales contract or formally apply for a mortgage (see the resources below). Your certificate is good for one year.
- Get pre-approved and find a home inside the city limits. Shop with your agent for a primary residence in the City of Wilmington that fits your budget.
- Complete the inspections. Arrange the home inspection with an ASHI-certified inspector, and the lead-based paint assessment if the home was built before 1978. Address any required repairs before closing.
- Your lender or counselor submits the First Start application. Applications go through the City’s online portal (Neighborly) in steps, submitted by your lender, real estate agent, or housing counselor. Incomplete applications are rejected and do not hold funds. Once the City issues an eligibility letter, it reserves funds for 90 days or until your closing date, and it needs the funding request and Closing Disclosure at least two weeks before closing – so allow for that when you set your settlement date.
- Close with First Start applied. We coordinate the First Start assistance with your first mortgage so it lands at the closing table.
To get started, give The John Thomas Team a call at 302-703-0727 or apply online. We will tell you where you stand and which programs you may qualify for, subject to full underwriting review.
Wilmington First-Time Buyer Resources
First Start requires homeownership counseling with a HUD-certified counselor before you sign a contract. City of Wilmington Real Estate and Housing runs the program (800 French St., 7th Floor; 302-576-3000; firststarthousing@wilmingtonde.gov). These HUD-approved Delaware housing counseling agencies provide buyer-side education and counseling (they are independent resources, not lender partners):
- West End Neighborhood House (Wilmington) – HUD-approved housing counseling
- YWCA Delaware (statewide) – HUD-approved housing counseling
- NeighborGood Partners (statewide) – HUD-approved housing counseling
For more on getting started as a buyer in Delaware, see our Delaware first-time home buyer guide. For broader federal homebuyer education, the CFPB Owning a Home resources are a helpful neutral reference, and you can locate HUD-approved counselors near you through the CFPB housing counselor search. If you work for the City of Wilmington, also compare the Wilmington Employee Homebuyer Assistance Program, which is built for City employees and has its own rules. And if you were searching for the older City of Wilmington Home Buyer Assistance Program (HAP), see our note on the City of Wilmington HAP program status and current alternatives.
Watch a quick overview of the City of Wilmington First Start down payment program:
FAQ – Wilmington First Start Program
What is the City of Wilmington First Start Down Payment Program?
First Start is a City of Wilmington program that gives eligible first-time buyers the lesser of $15,000 or 6% of the purchase price toward down payment and settlement costs on a single-family primary residence inside Wilmington city limits. The down payment portion is a 0% conditional loan and the closing cost portion is a grant, forgiven after 10 years of owner occupancy. It is run by the City of Wilmington Department of Real Estate and Housing, separate from DSHA.
What are the income limits for the Wilmington First Start Program in 2026?
The City’s limits, effective June 1, 2026: the CDBG tier (80% of median) is $68,750 for 1 person, $78,550 for 2, $88,350 for 3, $98,150 for 4, $106,050 for 5, $113,900 for 6, $121,750 for 7, and $129,600 for 8. The General Fund tier (100% of median) is $85,900 for 1, $98,200 for 2, $110,500 for 3, $122,700 for 4, $132,600 for 5, $142,400 for 6, $152,200 for 7, and $162,000 for 8. The City confirms limits at application. Unlike DSHA, the City counts the gross income of every adult in the household.
Do I have to pay back the Wilmington First Start loan?
Not if you stay. The First Start loan is forgiven after 10 years of living in the home as your primary residence. It becomes payable in full if you sell or transfer the home, stop living in it, or fall behind on your mortgage, City property taxes, or water and sewer bills during those 10 years.
Can I combine Wilmington First Start with an FHA, VA, or conventional loan?
Yes. First Start is down payment assistance, not a first mortgage, so you pair it with an FHA, VA, or conventional first mortgage. The City requires that first mortgage to have a fixed rate and a term of 30 years or less. The right loan depends on your credit, income, down payment, and veteran status, which we review with you.
Can I use Wilmington First Start together with DSHA down payment assistance?
Yes. Eligible buyers who qualify for both can combine First Start with a DSHA down payment assistance program for up to an additional 5% in assistance – for example, DSHA Take5. When the two are stacked, the DSHA loan records in second position and First Start moves to third. The exact amounts depend on your income, the programs’ rules, and your first mortgage, and are confirmed at application subject to full underwriting review.
Can I qualify for First Start after a Chapter 7 bankruptcy?
Possibly. First Start eligibility is tied to the City’s income, residency, and first-time-buyer rules, while your first mortgage (FHA, VA, or conventional) has its own waiting periods and credit guidelines after a bankruptcy. Many buyers qualify once enough time has passed and credit has been re-established, depending on the loan program and overall profile. We can review your timeline and tell you where you stand.
What if the home I want needs repairs or was built before 1978?
Homes built before 1978 need a visual lead-based paint assessment; if it finds peeling or chipping paint, a lead test is required and hazards must be fixed before closing. Every property needs an inspection by an ASHI-certified inspector, shared with the City, with serious defects addressed before closing. If a home needs repairs, the buyer and seller agree in writing who makes them, and in some cases a renovation loan can help.
Do I need to take a homebuyer education class for First Start?
Yes. You need at least 8 hours of homebuyer counseling with a HUD-certified agency, completed before you sign a sales contract or apply for a mortgage; the certificate is valid for one year. HUD-approved Delaware agencies include West End Neighborhood House, YWCA Delaware, and NeighborGood Partners.
How do I apply for First Start – directly to the City or through a lender?
Through your lender, real estate agent, or housing counselor, who submits a completed application in the City’s online portal; the City does not take applications directly from buyers. Incomplete applications are rejected and do not reserve funds, and the City needs the funding request at least two weeks before closing. Call the John Thomas Team at 302-703-0727 to get started.
What happens to the First Start forgiveness if I refinance my first mortgage?
The City will subordinate its loan – agree to stay behind your new first mortgage – if you refinance to a lower interest rate. It will not subordinate to a cash-out refinance. Forgiveness still depends on living in the home as your primary residence for the full 10 years, so confirm the details with the City and your lender before you refinance.
John R. Thomas, NMLS #38783
Branch Manager & Division Vice President of Sales, John Thomas Team with AnnieMac Home Mortgage
I am John Thomas, Branch Manager and Division Vice President of Sales with the John Thomas Team. For more than 20 years I have helped Delaware first-time buyers find the right combination of loan program and down payment assistance, including City of Wilmington buyers using First Start. I wrote “Your Guide to Buying Your First Home in Delaware” to make the process clearer for first-time buyers, and I lead a free Delaware home buyer seminar to walk people through it step by step.
My background is in teaching – I hold a BS in Physics Education from the University of Delaware and an MS in Curriculum and Instruction from Delaware State University – which is a big part of why I focus on explaining the process clearly rather than rushing you through it. When you call, you talk with someone who knows how Wilmington’s local programs work alongside FHA, VA, conventional, and DSHA financing, so you can see your real options side by side before you commit to anything. My day-to-day work is helping buyers across Delaware and Maryland.
Years 3,000+
Delaware Buyers DE and MD
Service Area Newark, DE
Office CMP
Certified Mortgage Planner
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713
Phone: 302-703-0727
Email: team@johnthomasteam.com
Schedule: Schedule Appointment
State licensing: John R. Thomas, NMLS #38783, on NMLS Consumer Access.
See John Thomas Team on Google for reviews, directions, and local office information.
YouTube · Facebook · Instagram · TikTok · X / Twitter · LinkedIn
- Whether the home is inside City of Wilmington limits (First Start only applies in the city)
- Which income tier you fall under and whether you are within the current limits
- Which first mortgage fits best – FHA, VA, or conventional
- Your HUD counseling timing, so it is finished before you sign a contract
- Property-condition items that could affect the appraisal or inspection on older homes
- Current First Start funding availability for the program year
Let’s review your income, your price range, and which programs you may qualify for – so you walk into your Wilmington home search knowing your real options. Subject to full underwriting review.
Last Updated: October 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
John R. Thomas, NMLS #38783 | John Thomas Team with AnnieMac Home Mortgage | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
AnnieMac Home Mortgage is an Equal Housing Lender. State licensing: John R. Thomas, NMLS #38783, on NMLS Consumer Access.
(c) Copyright John R. Thomas, All Rights Reserved.
