Fresh Start Loan Program in Delaware: Buy or Refinance After Bankruptcy or Foreclosure

FRESH START LOAN PROGRAM – QUICK ANSWER
The Fresh Start Loan Program is a non-QM mortgage for Delaware borrowers who can document income but may not qualify for FHA, VA, USDA or conventional financing after a bankruptcy, foreclosure, short sale or mortgage lates. Eligible borrowers may buy or refinance sooner, subject to underwriting and program guidelines. Current as of October 2026.
If a past bankruptcy, foreclosure, short sale, or a stretch of late mortgage payments is standing between you and a home, you have more options than you may think. I am John Thomas, NMLS #38783, and my goal on this page is to show you how the Fresh Start Loan Program works, who it fits, and when a lower-cost traditional loan is the better move. I have spent 20+ years helping Delaware families through exactly this situation. Fresh Start is built for people who can prove they can repay a mortgage today but do not yet fit the credit box for a traditional loan. If your credit event is further behind you, it is also worth reading about your options for a Delaware mortgage after bankruptcy, because in many cases an FHA, VA, or conventional loan with a lower rate becomes available once enough time has passed.
Ready to Talk Through Your Fresh Start?
A short, no-pressure conversation will tell you whether Fresh Start, or a better-priced traditional loan, is the right path for your situation. Have your discharge or settlement paperwork handy and we can usually tell you which path is open.
Table of Contents
What Is the Fresh Start Loan Program?
The Fresh Start Loan Program is a non-QM mortgage for borrowers who can document their income but cannot yet qualify for FHA, VA, USDA or conventional financing after a bankruptcy, foreclosure, short sale or mortgage late payments. It weighs current ability to repay instead of multi-year waiting periods, and it usually carries a higher rate.
The program is designed for borrowers who can prove their ability to repay a mortgage but may not qualify for traditional financing because of past credit challenges. It is what the industry calls a non-prime or non-QM loan: instead of measuring you against the strict bankruptcy and foreclosure waiting periods that government and conventional loans require, a Fresh Start loan looks more closely at your current ability to repay. It is a home loan for buying or refinancing real estate, not a small personal credit-builder loan of the kind some banks and nonprofits also call “fresh start.”
That makes it a fit for people who have worked through a real financial setback – a foreclosure, deed-in-lieu, short sale, mortgage charge-off, a run of late mortgage payments, or a bankruptcy – and who want to buy or refinance a home now rather than wait several more years for a traditional program to open up. The trade-off is that a Fresh Start loan typically carries a higher interest rate than an FHA, VA, or conventional loan, which is why I always look at both paths with you before recommending one.
Key terms in plain English
- Non-QM / non-prime mortgage: a loan that does not follow the standard Qualified Mortgage agency rules, so it can consider borrowers who do not fit FHA, VA, USDA, or conventional guidelines.
- Loan-to-value (LTV): the loan amount as a percentage of the home’s value. 85% LTV means roughly 15% down on a purchase, or 15% equity on a refinance.
- Debt-to-income (DTI): your total monthly debt payments as a percentage of your gross monthly income. Our guide to understanding your debt-to-income ratio shows how lenders calculate it.
- Seasoning: the waiting time a loan program requires after a credit event such as a bankruptcy or foreclosure before you can be approved.
Fresh Start at a glance
- Fresh Start is for buyers who can document income but were declined after a credit event.
- You may be eligible as soon as one day after a discharged bankruptcy or a settled foreclosure or short sale, subject to underwriting.
- Credit scores start at 620, with financing up to 85% loan-to-value and loan amounts up to $3 million.
- Income can be documented with full documentation, 12-24 months of bank statements, profit-and-loss (P&L) only, or 1099.
- It works for primary residences, second homes, and investment properties.
- It usually costs more than a traditional loan, so we compare both before you decide.
Video: Fresh Start Loan Program Explained by John Thomas
If you’d rather watch than read, I walk through this whole guide in about 13 minutes: who Fresh Start fits, how soon you may be able to buy after a bankruptcy or foreclosure, what it takes to qualify, how it compares with FHA, VA and conventional loans, and when it’s the wrong choice. The program terms in the video reflect Fresh Start guidelines as of October 2026, and your own terms depend on your credit, income, property and full underwriting.
Jump to a chapter
- 0:00 What is the Fresh Start Loan Program?
- 2:12 Who is the Fresh Start Loan Program for?
- 2:57 How soon can you buy a home after bankruptcy or foreclosure?
- 4:11 What are the Fresh Start Loan Program benefits?
- 4:57 What do you need to qualify for a Fresh Start loan?
- 5:33 What does a Fresh Start loan look like in practice?
- 6:55 How does Fresh Start compare to FHA, VA and conventional loans?
- 7:45 When is the Fresh Start Loan Program not the right fit?
- 8:48 What mistakes should you avoid with a Fresh Start loan?
- 9:33 Where in Delaware can you use a Fresh Start loan?
- 10:00 How do you apply for a Fresh Start loan in Delaware?
- 10:46 What do borrowers ask about the Fresh Start Loan Program?
- 12:17 How do you get started with Fresh Start in Delaware?
Who Is the Fresh Start Loan Program For?
Fresh Start fits Delaware buyers and homeowners who can document income and afford the payment but were declined after a recent credit event, including self-employed and 1099 earners, second-home buyers and investors. Borrowers whose credit event is old enough to meet agency waiting periods usually do better with FHA, VA, USDA or conventional.
The program tends to fit Delaware buyers and homeowners in situations like these:
- You can document your income and afford a monthly payment, but a recent bankruptcy, foreclosure, short sale, or mortgage lates put a traditional approval out of reach for now.
- You want to buy before home prices climb further, rather than wait out a multi-year seasoning period.
- You are self-employed, 1099, or commission-based. Fresh Start accepts full documentation, 12-24 months of bank statements, profit-and-loss (P&L) only, or 1099 income, so a non-traditional income file can still work – a bank statement loan may also be worth comparing.
- You are buying a second home or an investment property after a credit event. Fresh Start covers all three occupancy types, and investors may also want to compare a DSCR loan or the Equity First loan program.
- You need to refinance, take unlimited cash out, or consolidate debt but were declined by a traditional lender because of credit history.
A past mark on your credit does not automatically disqualify you. If you can show you can repay the loan today, there is usually a path worth exploring. Understanding the five factors of credit scoring also helps you see which parts of your profile you can strengthen before or after you buy.
How Soon Can You Buy a Home After Bankruptcy or Foreclosure?
A Fresh Start borrower may be eligible as soon as one day after a bankruptcy is discharged or a foreclosure or short sale is settled, and recent mortgage late payments may be permitted (program guidelines as of October 2026). Agency loans typically require a wait of about two to seven years. Full underwriting confirms final eligibility.
This is the question I hear most. Traditional loans make you wait a set number of years after a major credit event before you can be approved. Fresh Start is not built around a multi-year wait: depending on your overall profile, you may be eligible as soon as one day after a bankruptcy is discharged or a foreclosure or short sale is settled, and recent mortgage late payments may be permitted. Your exact terms – including your rate and the 85% maximum loan-to-value – are confirmed through full underwriting, because the answer depends on the type of event, how recent it was, and the rest of your borrower profile.
When a buyer calls me after a bankruptcy or foreclosure, the first thing I ask for is the discharge or settlement paperwork. That date, not the date you filed, decides whether Fresh Start or a lower-cost traditional loan is open to you, so I confirm it before we talk about anything else.
One important detail: “one day” refers to one day after a bankruptcy is discharged or a foreclosure or short sale is settled – not one day after you filed. If you are still making payments in a Chapter 13 plan, you may not have to wait for the discharge: an open Chapter 13 may be eligible with court or trustee approval of the new mortgage, subject to underwriting. If your credit event is far enough behind you, a traditional loan with a lower rate may already be within reach. For the standard agency waiting periods and the full set of after-credit-event options, see our detailed guide to getting a Delaware mortgage after bankruptcy. The comparison table further down this page summarizes how Fresh Start stacks up against FHA, VA, USDA, and conventional waiting periods.
Fresh Start Loan Program Benefits
Where it fits your situation, the Fresh Start Loan Program can offer flexibility that traditional programs do not. Specific terms vary by borrower and are confirmed at application:
- A way to buy or refinance now and rebuild your credit over time.
- No multi-year seasoning requirement – eligible as soon as one day after a discharged bankruptcy or a settled foreclosure or short sale, with recent mortgage late payments permitted.
- Fixed-rate or adjustable-rate (ARM) options.
- Eligible property types may include a single-family residence, condominium, co-op, a 2-4 unit property, or a home in a Planned Unit Development (PUD).
- Available for purchase, rate-and-term refinance, unlimited cash-out refinance, and debt consolidation.
- Eligible for primary residences, second homes, and investment properties.
- Flexible income documentation – full doc, 12-24 months of bank statements, profit-and-loss (P&L) only, or 1099.
- Financing up to 85% loan-to-value on loan amounts up to $3 million, with debt-to-income considered up to 50%.
- Mortgage or rental payment history may not be required, subject to current program guidelines.
- Seller concessions of up to 6% of the price toward your closing costs may be allowed.
- Gift funds from family members may be allowed toward your down payment and costs – see our gift funds and gift of equity guidelines.
- Mortgage insurance is generally not required, subject to current program guidelines – unlike many low-down-payment traditional programs. Our explainer on what mortgage insurance (PMI) is covers how it works on those loans.
What Do You Need to Qualify for a Fresh Start Loan?
A Fresh Start loan typically needs a credit score of 620 or higher, at least 15% down or 15% equity (85% maximum loan-to-value), debt-to-income up to 50%, and income documented through full documentation, bank statements, profit-and-loss or 1099, per program guidelines as of October 2026. Underwriting confirms the final terms.
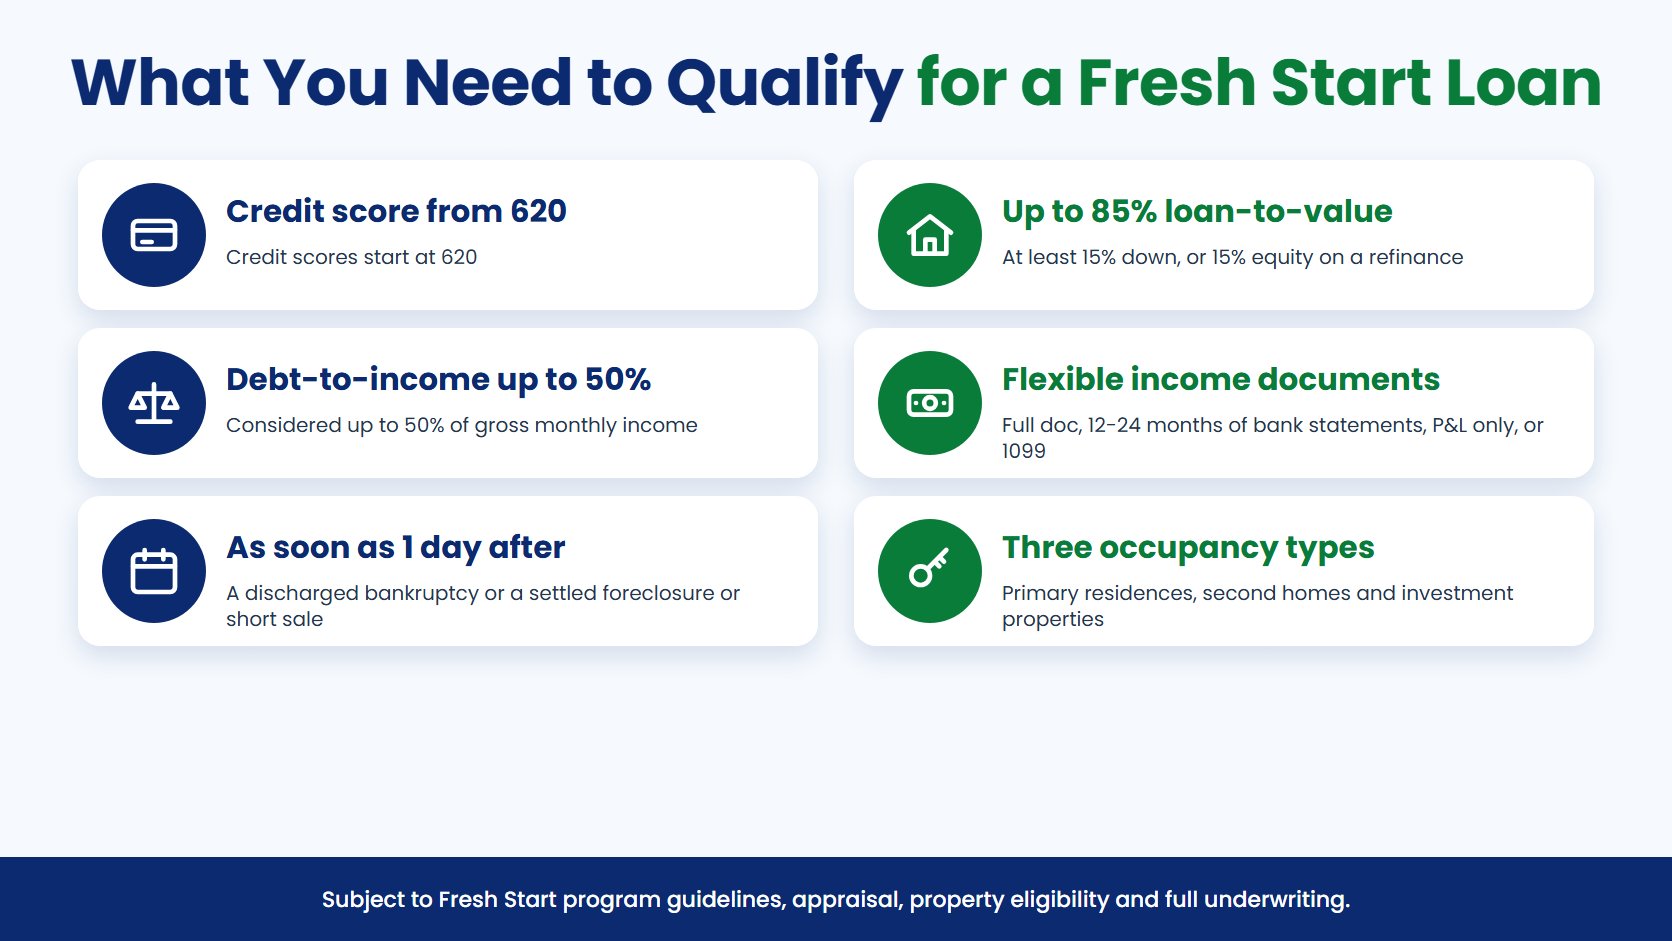
Fresh Start guidelines are more flexible than agency loans, but there is still a profile we look for. The figures below reflect current Fresh Start program guidelines as of October 2026; your exact rate and terms are finalized when we review your file:
- Credit score: starting at 620.
- Maximum loan-to-value: up to 85% LTV (at least 15% down on a purchase or 15% equity on a refinance).
- Loan amounts: up to $3 million.
- Debt-to-income (DTI): up to 50%.
- Income documentation: full doc, 12-24 months of bank statements, profit-and-loss (P&L) only, or 1099 – flexible options for self-employed and 1099 earners.
- Occupancy: primary residences, second homes, and investment properties.
- Recent credit or housing events: a bankruptcy, foreclosure, short sale, or mortgage late payments may be permitted – eligible as soon as one day after a discharged bankruptcy or a settled foreclosure or short sale. An open Chapter 13 may also be eligible with court or trustee approval of the new mortgage.
- Tradelines: no minimum number of tradelines required when you have three credit scores.
- Seller concessions: up to 6% of the price toward closing costs.
- Cash-out: unlimited cash-out available on a refinance.
- Gift funds: allowed toward your down payment and costs.
Your debt-to-income ratio and the credit factors that shaped your score are central to this conversation, so we walk through both together before you commit to anything. The goal is to get you into a loan you can comfortably carry while you rebuild toward a traditional refinance later.
What a Fresh Start Loan Looks Like in Practice
Example (illustrative only): A Delaware buyer wants to purchase a $300,000 home after a recently discharged Chapter 7 bankruptcy. At up to 85% financing, the buyer would plan for at least 15% down – about $45,000 – plus closing costs, although seller concessions of up to 6% may offset part of those costs. Final eligibility, rate, and terms would still depend on credit, income, debt, reserves, property type, and full underwriting. This is a simplified illustration, not a quote.
What this means for you: Fresh Start can open an earlier path to ownership, but it usually requires more cash up front than many FHA, VA, USDA, or down payment assistance options. We compare the real cost of moving now against the cost of waiting for a lower-rate traditional program, so the decision is yours with the numbers in front of you.
Many borrowers use Fresh Start as a bridge. Once your credit recovers, you build on-time payment history, and enough time passes to clear the agency waiting periods, you may be able to refinance into a lower-cost FHA, VA, USDA, or conventional loan. Whether and when that is possible depends on your credit, equity, payment history, market conditions, and the program guidelines in place at the time – but having an exit strategy from day one is part of how we plan your loan.
Fresh Start vs. FHA, VA, and Conventional Loans in Delaware
The biggest practical difference between a Fresh Start loan and a traditional loan is the waiting period after a major credit event. The table below shows typical agency waiting periods alongside the Fresh Start approach. Agency periods follow the HUD Handbook 4000.1 (FHA), the VA Lenders Handbook, Chapter 4 (VA), the USDA Single Family Housing Guaranteed Loan Program, and the Fannie Mae Selling Guide B3-5.3-07, and can be shortened in cases of documented extenuating circumstances – we confirm the exact figures for your situation, and our mortgage-after-bankruptcy guide covers the details.
| Loan Type | Typical wait after Chapter 7 bankruptcy | Typical wait after foreclosure | Mortgage insurance |
|---|---|---|---|
| Fresh Start | As soon as 1 day after discharge | As soon as 1 day after the event is settled | Not required |
| FHA | About 2 years (less with documented extenuating circumstances) | About 3 years | Required (MIP) |
| VA | About 2 years | About 2 years | Not required (funding fee may apply) |
| USDA | About 3 years | About 3 years | Guarantee fee applies |
| Conventional | About 4 years (2 with documented extenuating circumstances) | About 7 years (3 with documented extenuating circumstances) | Required under 20% down (PMI) |
Typical waiting periods only. Exact requirements depend on your situation and current agency guidelines. Sources: FHA (HUD Handbook 4000.1), VA (Lender’s Handbook), USDA (HB-1-3555), and Fannie Mae (Selling Guide B3-5.3-07). Current as of October 2026. If a VA loan or USDA loan is open to you, those programs usually cost less than Fresh Start.
When the Fresh Start Loan Program Is Not the Right Fit
Fresh Start is a bridge, not the only option. It may not be your best choice if:
- Your credit event is far enough behind you that you already meet the FHA, VA, USDA, or conventional waiting periods – those loans usually carry lower rates, so qualifying for one of them first will typically cost you less.
- Your credit issues are minor or stem from a single fixable item; a short period of focused credit work may move you into a traditional approval.
- You cannot document stable income to support the payment; Fresh Start still requires that you demonstrate the ability to repay.
- You are an eligible veteran or service member – a VA loan is often the stronger path even after a credit event, given its shorter waiting periods and no monthly mortgage insurance.
The honest answer is that the right loan is the one that gets you into a home at the lowest reasonable cost for your situation. Sometimes that is Fresh Start now; sometimes it is waiting a few months and using a traditional program. I will tell you which one I see.
Common Mistakes to Avoid with a Fresh Start Loan
- Assuming “one day after bankruptcy” means one day after filing – for a Chapter 7 it means one day after an eligible discharge. If you are still in a Chapter 13 plan, the path is court or trustee approval of the new mortgage.
- Shopping only for the lowest advertised rate instead of comparing the total cost of moving now versus waiting for a traditional loan.
- Moving large gift deposits without documenting the source – see our gift funds guidelines.
- Failing to disclose every property and credit event early in the process.
- Assuming every condo, co-op, or investment property will automatically qualify – property type and use affect eligibility.
- Using all available cash for the down payment and leaving no reserves.
- Choosing Fresh Start when a lower-cost FHA, VA, USDA, or conventional loan is already available to you.
Fresh Start Mortgage Options for Delaware Buyers
Fresh Start financing may be an option for qualified buyers throughout Delaware – including Newark, Wilmington, and across New Castle, Kent, and Sussex Counties. Property type, occupancy, income documentation, credit history, and available equity all affect your final terms, so the goal is always to review both Fresh Start and traditional financing before you choose a path. If you are early in the process, our Delaware first-time home buyer resources and down payment assistance programs are also worth a look once your credit qualifies.
- Fresh Start mortgage options in Newark, Delaware
- Mortgage options after a credit setback in Wilmington, Delaware
How to Apply for a Fresh Start Loan in Delaware
Getting started is simple. Call me at 302-703-0727, schedule a 30-minute review, or apply online, and we will work through these steps together:
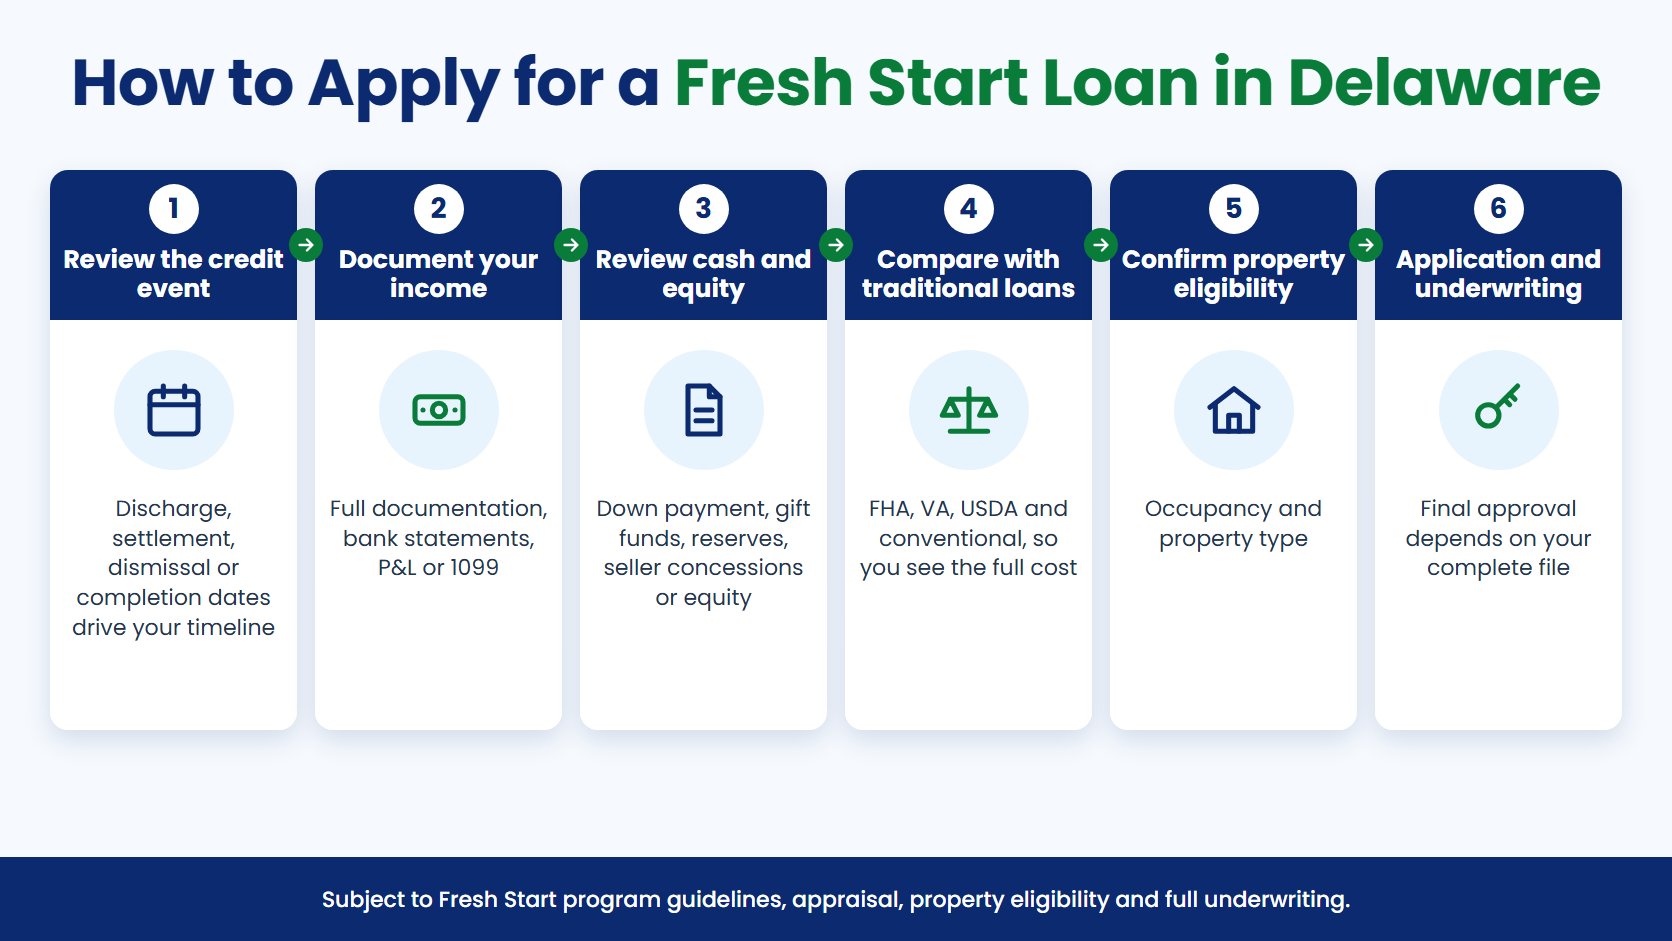
- Review the credit event – identify the discharge, settlement, dismissal, or completion dates that drive your timeline.
- Document your income – full documentation, bank statements, P&L, or 1099, whichever fits how you earn.
- Review cash and equity – down payment, gift funds, reserves, seller concessions, or refinance equity.
- Compare Fresh Start with traditional options – FHA, VA, USDA, conventional, and relevant Delaware programs, so you see the full cost picture.
- Confirm property eligibility – occupancy and property type.
- Complete the application and underwriting review – final approval depends on your complete file and current guidelines.
What to have ready. You do not need to gather everything before you reach out, but having these on hand helps us give you straight answers faster:
- A government-issued photo ID for each borrower.
- Your bankruptcy discharge, foreclosure, short-sale, or deed-in-lieu paperwork showing the completion or settlement date.
- Income documentation that fits how you earn – recent pay stubs and W-2s, 12-24 months of personal or business bank statements, a year-to-date profit-and-loss statement, or 1099s.
- Recent bank and asset statements, plus a paper trail for any gift funds.
- A two-year history of where you have lived, with any mortgage or rent payment record.
- Details on the property you are buying or refinancing – address, type, and how you will use it.
- A short letter of explanation for the credit event, if we request one.
If Fresh Start is the right fit, we will map out the path. If a traditional loan would serve you better – now or after a short wait – I will tell you that too. Either way, you will leave the conversation knowing your real options.
Fresh Start Loan Program FAQ
Can I get a mortgage with bad credit in Delaware?
Often, yes. A low score or a recent bankruptcy, foreclosure, short sale or mortgage late payments does not automatically rule you out. FHA, VA, USDA and conventional loans may work once you meet their waiting periods and score minimums. If a recent credit event rules them out, the Fresh Start Loan Program, with credit scores starting at 620, looks at your current ability to repay instead. We compare both paths before you choose, subject to program guidelines and full underwriting.
Can I get a Fresh Start loan right after a bankruptcy or foreclosure in Delaware?
You may be eligible as soon as one day after a bankruptcy is discharged or a foreclosure or short sale is settled, depending on your overall profile, and recent mortgage late payments may be permitted. There is no multi-year seasoning to wait out, but final eligibility and terms, including the 85% maximum loan-to-value, are confirmed through full underwriting. Note that this is one day after discharge or settlement, not one day after filing. If you are still in a Chapter 13 repayment plan, you may be able to qualify before the discharge with court or trustee approval of the new mortgage.
What credit score do I need for a Fresh Start loan?
The Fresh Start program starts at a 620 minimum credit score. Your rate and loan-to-value (up to 85%) depend on your overall profile – credit, income, reserves, and down payment – which we confirm when we review your file. The best first step is a quick conversation to see where you stand.
Can I use the Fresh Start program to refinance or consolidate debt, not just buy?
Yes. The Fresh Start Loan Program can be used for a purchase, a rate-and-term refinance, an unlimited cash-out refinance, or debt consolidation, where it fits your situation and the property qualifies. Many homeowners use it to consolidate higher-cost debt and stabilize their finances while they rebuild credit toward a future traditional refinance.
Can I use gift funds for the down payment on a Fresh Start loan?
In many cases, yes. Gift funds from family members may be allowed toward your down payment and closing costs, subject to current program guidelines and proper documentation. We will walk through the gift letter and sourcing requirements so the funds are accepted without delays.
Does the Fresh Start loan require mortgage insurance?
Mortgage insurance is generally not required on a Fresh Start loan, subject to current program guidelines, which sets it apart from many low-down-payment traditional programs. That said, a Fresh Start loan typically carries a higher interest rate than an FHA, VA, or conventional loan, so we compare the total cost of each option before you decide.
When is the Fresh Start program not the right choice?
If your credit event is far enough behind you that you already meet the FHA, VA, USDA, or conventional waiting periods, those loans usually carry lower rates and will typically cost less, so qualifying for one of them first is the better move. Fresh Start is best when you need to buy or refinance before you would otherwise be eligible for a traditional loan.
Can I use a Fresh Start loan for a second home, investment property, or condo in Delaware?
Yes. Fresh Start works for primary residences, second homes, and investment properties, and eligible property types may include a single-family residence, condominium, co-op, a 2-4 unit property, or a home in a Planned Unit Development, subject to program guidelines. Tell us the property type and how you will use it up front so we can confirm eligibility before you write an offer.
Can I use Fresh Start with Delaware down payment assistance (DSHA)?
Generally no. Delaware State Housing Authority down payment assistance is paired with DSHA first mortgages such as Welcome Home or Open Door, not with a non-prime Fresh Start loan. If your credit and timeline let you qualify for a DSHA program, that is usually the lower-cost path. If a recent credit event rules DSHA out for now, Fresh Start may bridge the gap until you can qualify – and we will compare both so you can see the difference.
How do I apply for a Fresh Start loan in Delaware?
Call John Thomas at 302-703-0727, schedule a 30-minute review, or apply online. We will look at your credit, income, and goals together and tell you whether Fresh Start or a better-priced traditional loan is the right path for your situation.
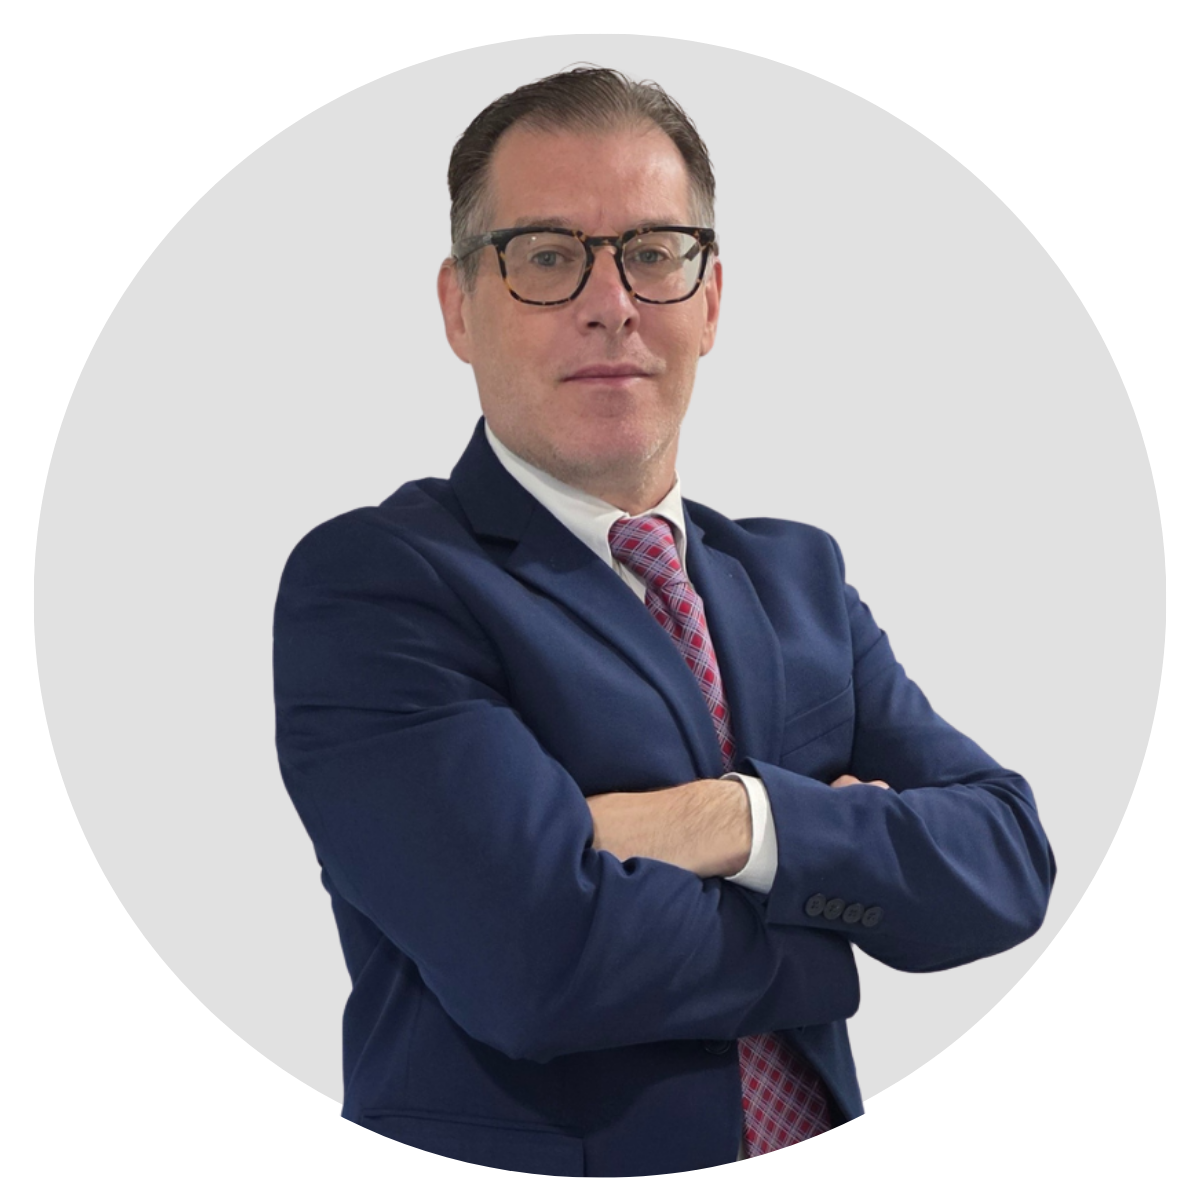
John R. Thomas is Branch Manager and Division Vice President with the John Thomas Team in Newark, Delaware, and has helped Delaware families finance homes for more than 20 years, including many who were told no by another lender after a credit setback. When a buyer calls after a bankruptcy or foreclosure, John starts with the dates on the paperwork: the discharge, dismissal or settlement date, not the filing date, decides whether Fresh Start or a lower-cost traditional loan is open, and he looks at both paths honestly before recommending one.
John holds a BS in Physics Education from the University of Delaware and an MS in Curriculum and Instruction from Delaware State University. He is the author of Your Guide to Buying Your First Home in Delaware and a frequent host of Delaware home buyer seminars. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access. Read more on his loan officer bio page.
Years 3,000+
Buyers Helped 1,000+
Govt Loans DE & MD
Service Area CMP
Certified Mortgage Planner
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com
Schedule Appointment (30 min)
See John Thomas Team on Google for reviews, directions, and local office information.
YouTube | Facebook | Instagram | TikTok | X / Twitter | LinkedIn
Get Your Fresh Start in Delaware

You may not have to wait years to own a home. Let’s find out today whether the Fresh Start Loan Program, or a better-priced traditional loan, can get you to the closing table.
Last Updated: October 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
John R. Thomas, NMLS #38783 | John Thomas Team with AnnieMac Home Mortgage | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
AnnieMac Home Mortgage is an Equal Housing Lender. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access.
(c) Copyright John R. Thomas, All Rights Reserved.
