Delaware Reverse Mortgage: HECM Loans for Homeowners 62+ in DE & MD (2026 Guide)
Delaware reverse mortgage overview: A Delaware reverse mortgage is a federally insured HECM (Home Equity Conversion Mortgage) that lets homeowners 62 and older in Delaware and Maryland turn part of their home equity into cash with no required monthly mortgage payment. You keep title, and the loan is repaid when the home is sold or the last borrower moves out or passes away. The 2026 HECM limit is $1,249,125, and Delaware law requires a counselor’s written certification before the loan can close. Current as of November 2026.
You are 62 or older, your home is paid down, and your monthly budget is tighter than you want it to be. Or you are comfortable, and you want a line of credit to draw on in a bad market year instead of selling investments. I’m John Thomas, NMLS #38783, and for more than 20 years I’ve helped Delaware and Maryland homeowners from our Newark office on Chestnut Hill Road. On this page I explain how a HECM works, who qualifies, how the amount is figured, what it costs, what happens for your heirs, and when it is the wrong loan. If you are under 62 or want to keep payments flexible, compare our Delaware HELOC and home equity loan guide.
Is a reverse mortgage right for you?
You don’t need to know the answer before you call. Tell me your age, your home’s value and any mortgage balance, and I’ll show you about how much may be available, what it costs, and how it compares with your other options. Bring an adult child or advisor if you like.
Table of Contents
What Is a Reverse Mortgage (HECM Loan) in Delaware and Maryland?
A reverse mortgage is an FHA-insured Home Equity Conversion Mortgage (HECM) for homeowners 62 and older. It turns part of your home equity into cash with no required monthly mortgage payment. You keep title, keep paying taxes, insurance and upkeep, and the loan is repaid when the home is sold or the last borrower leaves.
Almost every reverse mortgage in Delaware and Maryland is a HECM. It follows federal HUD and FHA rules on age, counseling, eligible homes and the yearly limit. It is not right for everyone: for some homeowners it solves a real cash-flow problem, and for others a HELOC, a cash-out refinance or downsizing makes more sense. The right answer depends on your age, your home’s value, your retirement income, how long you plan to stay, and what you want to leave to your heirs.
Watch: John Thomas explains how a HECM works, who qualifies, the 2026 limit, costs, pros and cons, common myths and the step-by-step process for Delaware and Maryland homeowners (6:21).
How Does a Reverse Mortgage Work?
A reverse mortgage works in the opposite direction of a regular mortgage. Instead of paying the lender each month, the lender pays you as a lump sum, monthly payments, a line of credit or a mix. Interest and mortgage insurance are added to the balance, so the balance grows over time.
You keep title to your home for as long as you live in it as your primary residence and keep paying property taxes, homeowners insurance (and flood insurance if required), HOA dues and basic upkeep. The loan becomes due when the last borrower sells the home, permanently moves out or passes away. The home is then usually sold to repay the loan, and any equity left over belongs to you or your heirs.
A HECM is a non-recourse loan. If the balance ends up larger than the home’s value when the loan is repaid, neither you nor your heirs owe the difference. FHA mortgage insurance, which you pay for through the upfront and annual premiums, covers the shortfall, and your heirs cannot lose other assets to pay the loan.
Who Qualifies for a Reverse Mortgage in Delaware in 2026?
You qualify for a HECM in Delaware if you are 62 or older, live in the home as your primary residence, have enough equity, complete HUD-approved counseling, and pass a financial assessment showing you can keep up with taxes, insurance and upkeep. The same federal rules apply in Maryland.
- Age 62 or older at closing. With two borrowers, the younger borrower’s age is used to figure the amount, which usually means less money than a single older borrower would get.
- Primary residence. Vacation homes, second homes and investment properties do not qualify.
- Enough equity. Most homeowners need substantial equity, often 50% or more, depending on age, rates and value. Any existing mortgage is paid off at closing, usually with the HECM money.
- HUD-approved counseling before you apply (federal rule 24 CFR 206.41). Delaware adds its own rule: under Delaware Code Title 5, Section 2244, a Delaware lender cannot finalize a reverse mortgage until it receives written certification from an independent housing counselor that you were counseled. Counseling is usually by phone. HUD keeps a list of approved counseling agencies.
- HUD financial assessment to confirm you can keep paying property taxes, insurance and upkeep (HUD Mortgagee Letter 2014-22).
- The home meets FHA standards. It must pass an FHA appraisal, and health and safety repairs the appraiser calls for, such as peeling paint on a home built before 1978, a damaged roof or a heating system that does not work, are done before closing or paid from a set-aside.
- No delinquent federal debt, such as federal taxes or federal student loans. In some cases the debt can be paid from the loan at closing.
- Your spouse’s age counts even if your spouse is not on the loan. The age of an eligible non-borrowing spouse is used to figure the amount, and age is counted at the nearest birthday.
What the HUD Financial Assessment Looks At
There is no minimum credit score for a HECM. Instead, the underwriter looks at your payment history and income, not to see whether you can make a mortgage payment (you will not have one) but to see whether you can keep up with taxes, insurance and upkeep:
- Mortgage and installment loans (like car loans): paid on time for the last 12 months, and no more than two 30-day late payments in the last 24 months.
- Credit cards: no payment more than 90 days late, and no three payments more than 60 days late, in the last 12 months.
- Property taxes, insurance and HOA dues: paid on time, with no delinquencies in the last 24 months.
- Residual income: the money left each month after your bills must meet HUD’s minimum for your household size and region.
A bankruptcy does not disqualify you by itself; the underwriter looks at when it was discharged or how the plan has been paid. A one-time event such as a serious illness or the death of a spouse can explain a credit problem, and strengths such as large savings can offset a weakness. If there is a concern, the underwriter can require a Life Expectancy Set-Aside (LESA): money held back so the servicer pays your property taxes and insurance, much like an escrow account. A LESA reduces the money available to you, and some borrowers choose one on purpose.
What Types of Homes Are Eligible for a Reverse Mortgage?
Most owner-occupied homes are eligible: single-family homes, townhomes, 2- to 4-unit homes where you live in one unit, FHA-approved condos, and manufactured homes that meet FHA rules. Vacation homes, investment property, co-ops and single-wide manufactured homes are not eligible for a HECM.
| Home | Eligible for a HECM? |
|---|---|
| Single-family detached | Yes (most common) |
| Townhome | Yes, if it meets FHA property standards |
| 2 to 4 units | Yes, if you live in one unit as your primary residence |
| Condo | Yes, if the project is FHA-approved or qualifies for FHA single-unit approval; see Delaware condo loans |
| Manufactured home | Yes, if titled as real estate on a permanent foundation, built after June 15, 1976 with a HUD label, generally double-wide or larger; see Delaware manufactured home loans |
| Mixed-use | Sometimes, depending on how much of the property is used for business |
| Vacation home, second home, investment property, co-op, single-wide | No |
What Is the 2026 Reverse Mortgage Loan Limit?
As of November 2026, the HECM limit, called the maximum claim amount, is $1,249,125 for FHA case numbers assigned from January 1, 2026, in every Delaware and Maryland county. It is one national figure, up from $1,209,750 in 2025, and it caps the home value used to figure your money.
HUD announced the 2026 figure in its 2026 loan limits release. Unlike forward FHA loan limits, which vary by county, the HECM limit is the same everywhere. If your home appraises for $1,500,000, FHA still uses $1,249,125 in the calculation. A home worth more than the limit still qualifies; FHA simply counts the value up to the limit. Our team does not offer private jumbo reverse mortgages in Delaware or Maryland (see the types section below). For the full breakdown, see our 2026 HECM reverse mortgage loan limits guide.
How Much Money Can You Get From a Reverse Mortgage?
HUD multiplies your home value, up to the HECM limit, by a percentage based on the youngest borrower’s age and the expected rate. Anything that must be paid at closing, such as an existing mortgage, comes out of that amount, and the rest is yours to use. It is usually less than half of the home’s value.
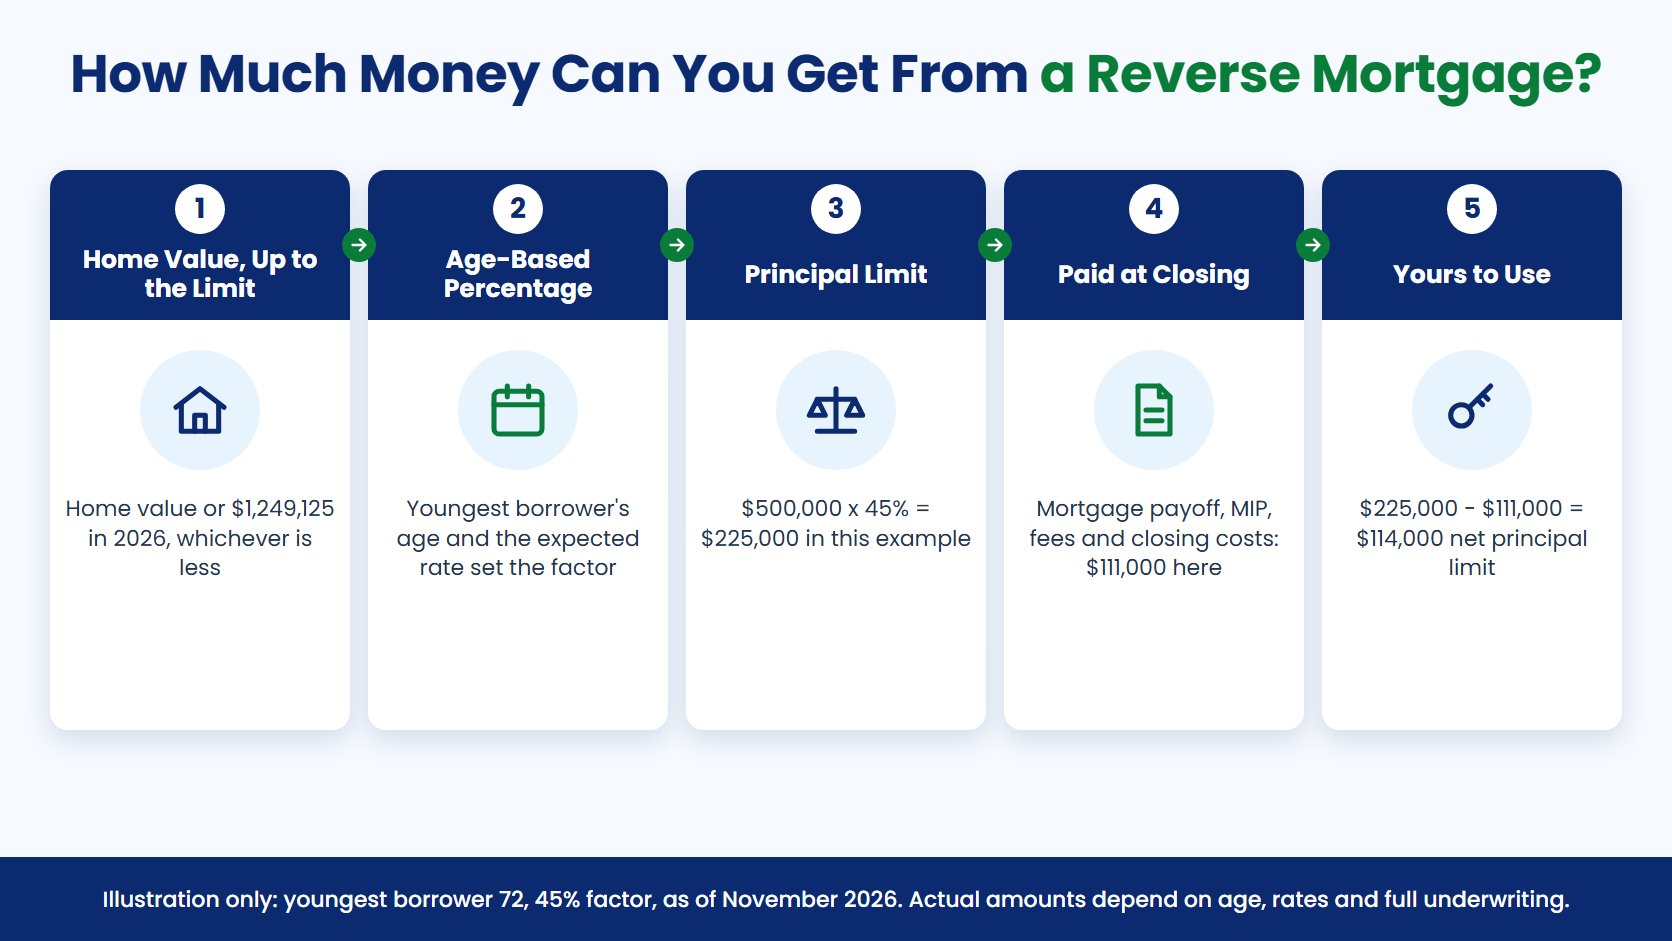
- Maximum claim amount. Your home value or the HECM limit ($1,249,125 in 2026), whichever is less.
- Principal limit factor. A percentage from HUD’s table, based on the youngest borrower’s (or eligible non-borrowing spouse’s) age and the expected rate. Older age and lower rates mean a higher percentage.
- Principal limit. The maximum claim amount times that percentage: the most the loan can provide.
- Mandatory obligations. What must be paid at closing: existing mortgage and liens, upfront FHA mortgage insurance, the origination fee, closing costs, any delinquent federal debt, and any required repairs or set-aside.
- Net principal limit. The principal limit minus the mandatory obligations: the money you can actually use.
Short to close. If what must be paid at closing is more than the principal limit, you would bring the difference to closing, for example from savings, or the loan does not work. We check this in the first conversation.
Educational Example: Estimated HECM Proceeds on a $500,000 Home
Estimate only, not a quote
These figures are a made-up example to show how the math works, not a prediction for your home. Actual proceeds depend on the youngest borrower’s exact age at closing, the expected rate on the day your case number is issued, your payout choice, any mortgage that must be paid off, and other loan details. Current as of November 2026.
| Step | What it means | Example (illustration only) |
|---|---|---|
| 1. Maximum claim amount | Home value or the HECM limit, whichever is less | Home value $500,000 |
| 2. Principal limit factor | HUD percentage for the youngest borrower’s age and the expected rate | Youngest borrower 72; factor 45% |
| 3. Principal limit | Maximum claim amount times the factor | $500,000 x 45% = $225,000 |
| 4. Mandatory obligations | Paid at closing: mortgage payoff, upfront MIP, origination fee, closing costs | $90,000 + $10,000 + $6,000 + $5,000 = $111,000 |
| 5. Net principal limit | What is left for you to use | $225,000 – $111,000 = $114,000 |
The first-year limit in this example. In the first 12 months you can use the greater of 60% of the principal limit ($135,000) or the mandatory obligations plus 10% ($111,000 + $22,500 = $133,500). The greater amount is $135,000. After the $111,000 of obligations are paid, about $24,000 is available in year one. On an adjustable-rate HECM, the remaining $90,000 becomes available after the first 12 months. On a fixed-rate HECM, the year-one amount is all you would receive. Our 2026 HECM loan limits guide shows how the limit and age change the numbers.
Paying Off Debts on the Home (Lien Seasoning)
Every mortgage and lien on the home is paid off at closing. HUD also looks at how long a debt has been on the home, so a reverse mortgage is not used to pay off money borrowed just before applying. A lien is fine if it has been on the home for more than 12 months, or if it gave you less than $500 in cash; a loan used to buy or build the home usually qualifies. A recent cash-out refinance, or a newer home equity line you have drawn on, can be a problem.
- Do not take out new debt on the home before applying, and tell us about any new loan or line of credit on the home.
- A HECM cannot pay off credit cards or other unsecured debt at closing. You can use the money available after closing for those bills.
HECM Terms in Plain English
- Maximum claim amount: your home value or the HECM limit, whichever is less.
- Principal limit: the most the loan can provide, based on age, the expected rate and the maximum claim amount.
- Mandatory obligations: what must be paid at closing, such as an existing mortgage, upfront MIP and fees.
- Initial disbursement limit: the most you can use in the first 12 months.
- Expected rate: the longer-term rate HUD uses only to figure how much money is available.
- LESA (Life Expectancy Set-Aside): money held back so the servicer pays your property taxes and insurance.
- Eligible non-borrowing spouse: a spouse not on the loan who can stay in the home if HUD conditions are met.
What Does a Reverse Mortgage Cost?
Closing costs are higher than on a regular mortgage, mainly because of FHA mortgage insurance: as of November 2026, 2% upfront and 0.5% a year on the balance. Add an origination fee capped at $6,000, normal third-party costs and a counseling fee. Most costs can be financed into the loan.
- Upfront FHA mortgage insurance premium (MIP): 2% of the home value or the HECM limit, whichever is lower (24 CFR 206.105). It is what makes the loan non-recourse and is usually financed.
- Annual MIP: 0.5% of the loan balance per year, added to the balance rather than paid out of pocket.
- Origination fee: the greater of $2,500 or 2% of the first $200,000 of home value plus 1% of the value above that, with a maximum of $6,000 (24 CFR 206.31). Usually financed.
- Third-party closing costs: FHA appraisal, title insurance, recording fees, credit report, flood certification and similar costs.
- Counseling fee: set by the HUD-approved agency, often around $125 to $200, and usually the only cost before closing. Agencies may waive it if you can’t afford it.
- Interest: charged on the balance and added to it, which is why the balance grows. Rates change daily; call for current pricing.
Because most costs are financed, the practical question is not what you pay today but how your equity looks over time. That is the math we walk through side by side with your other options.
How Can You Receive the Money, and Fixed or Adjustable?
You can take a lump sum, a line of credit, monthly payments for a set number of years, monthly payments for as long as you live in the home, or a mix. A fixed-rate HECM pays one lump sum at closing; every other choice uses an adjustable-rate HECM.
- Lump sum. All the money at closing. A fixed-rate HECM pays only a lump sum. Common when there is one large need, such as paying off a mortgage.
- Line of credit (adjustable-rate only). Draw as needed. The unused part grows at the same rate as the balance: the note rate plus the 0.5% annual mortgage insurance. It cannot be reduced because home values fall, as long as you meet the loan terms, and voluntary payments go back into the line.
- Term payments. Equal monthly payments for a number of years you choose.
- Tenure payments. Equal monthly payments for as long as you live in the home as your primary residence.
- Modified term or tenure. Monthly payments plus a line of credit held in reserve.
Fixed Rate vs. Adjustable Rate HECM and the First-Year Limit
| Fixed-rate HECM | Adjustable-rate HECM | |
|---|---|---|
| How money is paid | One lump sum at closing | Line of credit, monthly payments, a lump sum within the first-year limit, or a mix |
| Interest rate | Never changes | Changes monthly or yearly with market rates; a cap limits how high it can go |
| Line of credit | None | Yes, and the unused part grows over time |
| Money after year one | None | The rest of the money available to you |
| Often fits | Someone who needs the money all at once | Most others, especially those who want flexibility or a standby line |
The first-year limit. HUD limits how much you can take in the first 12 months so the money is not used up too fast (the initial disbursement limit, 24 CFR 206.3). In year one you can use the greater of 60% of your principal limit, or the amounts that must be paid at closing plus 10% of the principal limit. On an adjustable-rate HECM the rest becomes available after year one. On a fixed-rate HECM, the first-year amount is all you will ever receive. This is the biggest trade-off between the two.
Two rates you will hear about. The interest rate is charged on your balance; on an adjustable HECM it is a published index plus a fixed margin. The expected rate is a separate, longer-term rate HUD uses only to figure how much money is available: a higher expected rate means less money. The lowest interest rate is not always the best choice, because the rate option changes the amount available, the costs and how fast a line of credit grows.
What Are the Pros and Cons of a Reverse Mortgage?
The biggest advantages are no required monthly mortgage payment, a non-recourse guarantee and a line of credit that can grow. The biggest drawbacks are higher closing costs, a balance that grows and reduces what your heirs receive, and possible effects on needs-based benefits.
| Pros | Cons |
|---|---|
| No required monthly mortgage payment (you still pay taxes, insurance and upkeep) | Closing costs are higher than a regular mortgage, mainly because of upfront MIP |
| Money you receive is a loan advance, generally not counted as taxable income (confirm with your tax advisor) | The balance grows as interest and MIP are added, leaving less equity for heirs |
| Non-recourse: you and your heirs never owe more than the home is worth | Can affect needs-based benefits such as Medicaid or SSI |
| You keep title and can leave the home to heirs | Missing taxes, insurance or upkeep can put the loan in default |
| An unused line of credit grows over time | If you move within a few years, the costs may not pay off |
| Several payout choices | An eligible non-borrowing spouse can stay but cannot draw more money |
Common Reverse Mortgage Myths
- “The bank takes my home.” You keep title for the life of the loan; the lender holds a lien, as with any mortgage.
- “My heirs will inherit the debt.” A HECM is non-recourse, so neither you nor your heirs can owe more than the home is worth.
- “I lose the home if I go to assisted living.” The loan becomes due only after a permanent move, generally 12 consecutive months away because of illness; short stays do not count.
- “Reverse mortgages are taxed as income.” The money is loan advances, not income, though it can affect Medicaid or SSI.
- “Only people in trouble use them.” Some financial planners use a HECM line of credit to draw on in down markets instead of selling investments.
Reverse Mortgage, HELOC or Cash-Out Refinance: Which Fits?
A reverse mortgage needs no monthly payment but grows over time; a HELOC and a cash-out refinance need monthly payments but shrink as you pay. If you are 62 or older, compare all three. Under 62, the choice narrows to a HELOC or a cash-out refinance.
| Reverse mortgage (HECM) | HELOC | Cash-out refinance | |
|---|---|---|---|
| Monthly principal and interest payment | Not required | Required during repayment | Required |
| Age requirement | 62 or older | None | None |
| How you qualify | Financial assessment for taxes, insurance and upkeep; no minimum score | Credit score, income and debt-to-income | Credit score, income and debt-to-income |
| Balance over time | Grows | Goes down as you pay | Goes down as you pay |
| Non-recourse protection | Yes (FHA-insured) | No | No |
| Closing costs | Higher (upfront MIP), usually financed | Lower | Moderate |
| Often fits | 62+ homeowners who want cash without a payment and plan to stay | Steady income, flexible access, shorter horizon | One lump sum at a fixed rate, replacing the first mortgage |
Our Delaware HELOC guide covers home equity lines and loans, and our Delaware FHA loans and Delaware conventional loans pages cover cash-out refinancing. If your goal is a lower payment on the mortgage you have, a mortgage recast may be worth a look.
What Happens to Your Home, Your Heirs and Your Spouse?
When the last borrower passes away or moves out for good, the loan becomes due. Heirs usually have up to 12 months to sell the home and keep the equity, pay off or refinance the loan to keep it, or deed it to the lender. They never owe more than the home is worth.
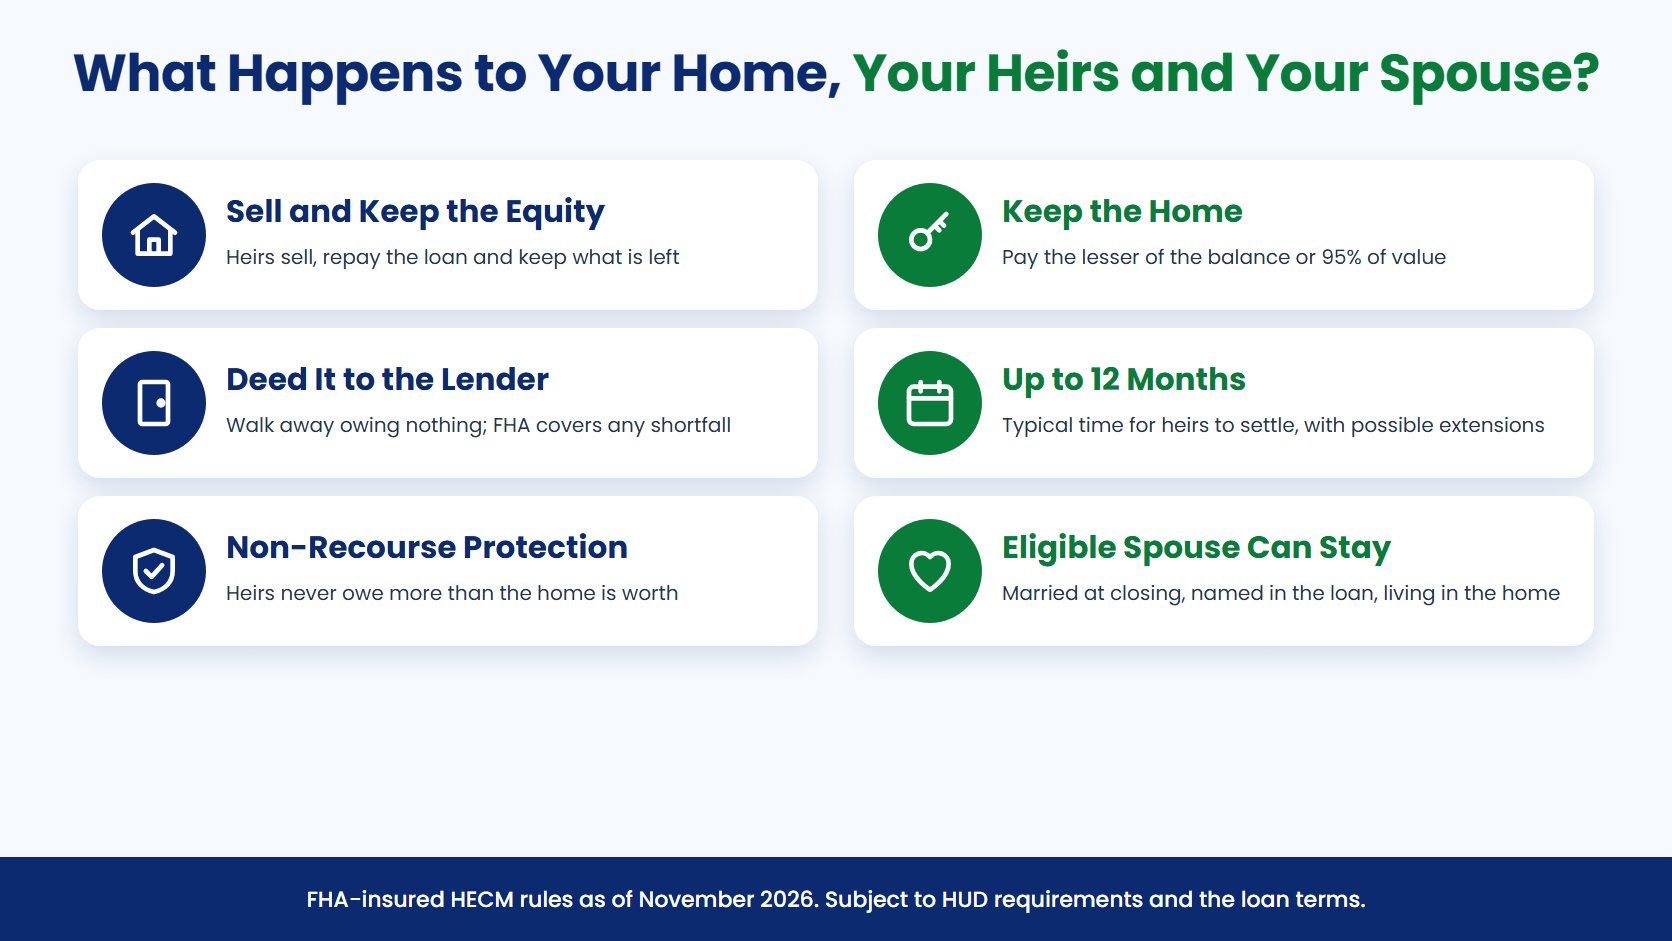
- Sell the home and pay off the loan. Any equity left after the payoff goes to the heirs. This is the most common path.
- Keep the home. Heirs pay off the loan with other money or refinance into a regular mortgage if they qualify.
- Deed the home to the lender. If the balance is more than the home is worth, heirs can sign a deed in lieu of foreclosure and walk away with no further obligation; FHA insurance covers the shortfall.
If the balance is more than the home is worth and your heirs want to keep it, they pay the lesser of the loan balance or 95% of the current appraised value (24 CFR 206.125); FHA insurance covers the rest. The 95% option is available only once the loan is due and payable, usually after the last borrower passes away. While you are living in the home, paying off the loan by refinancing means paying the full balance; if you sell, you still never owe more than the home is worth.
To sell or refinance the home, heirs usually need legal authority, for example as the personal representative of the estate. The rules differ between Delaware and Maryland, so heirs should talk with an estate attorney in the state where the home is, early, and keep the loan servicer informed while the estate is settled.
Warning for families
Heirs who are added to the title before the last borrower passes away may lose the 95% option. HUD looks for a sale or transfer of the home at or after death, for example through a will or trust. Talk with an estate attorney before changing the title.
Non-Borrowing Spouse Protections
If one spouse is under 62 and not on the loan, that spouse may still be able to stay in the home after the borrower passes away or moves out permanently (HUD Mortgagee Letter 2015-15; 24 CFR 206.55). An eligible non-borrowing spouse was married to the borrower at closing, lives in the home as a primary residence, and is named in the loan documents. To keep the deferral, the spouse must:
- Keep the home as their primary residence.
- Keep paying property taxes and homeowners insurance and maintain the home.
- Establish legal ownership or another legal right to stay in the home within the required time after the borrower’s death.
The trade-off: during the deferral the spouse cannot draw more money, and any line of credit or monthly payments stop. A spouse who does not live in the home has no deferral protection, and the loan becomes due when the borrower passes away. The younger spouse’s age is also used to figure the amount, which usually means less money when one spouse is much younger. Many homeowners bring an adult child, family member or advisor to the consultation, in person in Newark or by phone.
How Does a Reverse Mortgage Affect Taxes and Benefits?
The IRS treats reverse mortgage money as loan advances, not income. Social Security and Medicare are not affected. SSI and Medicaid can be, if you keep the money past the month you receive it. Interest is generally deductible only when it is actually paid, usually at payoff.
- Taxes. Loan advances are not income. Interest is generally deductible only when it is paid, and your servicer may send a Form 1098. Ask your tax advisor (CFPB).
- Social Security and Medicare. Not affected.
- SSI and Medicaid. These depend on income and assets. Money you draw and keep past the month you receive it can count as an asset. Draw only what you need and talk with a benefits advisor first.
- No prepayment penalty. You can pay off the loan, refinance or sell at any time.
- Voluntary payments. You can make payments any time. A payment covers mortgage insurance and fees first, then interest, then the amount borrowed.
- Yearly occupancy certification. About once a year you sign and return a form confirming you still live in the home.
- Statements. Your servicer sends regular statements showing the balance and any available line of credit.
Which Types of Reverse Mortgages Can You Get in Delaware and Maryland?
Most Delaware and Maryland homeowners use the standard FHA-insured HECM. The same program covers HECM for Purchase and HECM-to-HECM refinancing. Private (proprietary) jumbo reverse mortgages and single-purpose reverse mortgages exist in some places, but our team does not offer either.
- HECM. The standard FHA-insured reverse mortgage, used by most homeowners 62 and older.
- HECM for Purchase. A HECM used to buy a new primary residence (next section).
- HECM-to-HECM refinance. Replacing a reverse mortgage with a new one, for example after the home has gained value or to add a borrower. HUD requires a disclosure comparing the benefit with the cost, and a refinance must clearly help you; refinancing just to create a new loan (churning) is not allowed.
- Private (proprietary) jumbo reverse mortgages. Not FHA-insured. We do not offer them in Delaware or Maryland; see the comparison below.
- Single-purpose reverse mortgages. Offered in some areas by state or local agencies or nonprofits for one purpose, such as property taxes or repairs. We do not offer them.
Private (Proprietary) Reverse Mortgages vs. the FHA-Insured HECM
You may see private reverse mortgages advertised online, often called jumbo reverse mortgages. We don’t offer them in Delaware or Maryland, and our clients in both states use the FHA-insured HECM. Here is how they differ, so you know what you are reading about:
| HECM (FHA-insured) | Private (proprietary) reverse mortgage | |
|---|---|---|
| Backed by | FHA (federal mortgage insurance) | The private lender; not FHA-insured |
| Minimum age | 62 (youngest borrower) | Often 55 to 62, depending on the lender and the state |
| Home value counted | Up to $1,249,125 (2026) | Can be much higher on some programs |
| Mortgage insurance | 2% upfront plus 0.5% a year | None |
| Origination fee | Capped at $6,000 | Set by the program |
| Counseling | HUD-approved counseling required | Also required |
| Existing first mortgage | Must be paid off at closing | Paid off, or kept in place in a second-lien version |
| Never owe more than the home is worth | Yes | Usually; depends on the program |
If your home is worth more than $1,249,125, a HECM still works; FHA counts the value up to the limit. If you are under 62 or want to keep your current mortgage, we can compare a HELOC or a cash-out refinance instead.
How Does HECM for Purchase Work?
HECM for Purchase lets a buyer 62 or older buy a new primary residence with a large down payment from their own money, often 45% to 65% of the price depending on age and rates, and finance the rest with a HECM that has no required monthly mortgage payment.
It is common for homeowners who want to downsize, move closer to family, or move to a single-story home that fits aging in place. The down payment usually comes from the sale of your current home or from savings. The same counseling, financial assessment and primary-residence rules apply. It works well when:
- You are 62 or older and want to move to a different home.
- You have substantial equity in your current home to put toward the new one.
- You want to avoid a new monthly mortgage payment in retirement.
- You want to keep cash and investments for other needs.
- Move in within 60 days of closing. We plan the timeline around the sale of your current home.
- The down payment must be your own money, such as sale proceeds or savings, not a new loan.
- Tell your real estate agent early that you are buying with a HECM for Purchase.
- There is no 3-day right of rescission on a purchase.
How Do You Avoid Reverse Mortgage Scams?
Never agree to a reverse mortgage on an unsolicited call, never share financial information with someone who contacted you first, and never let anyone tie the loan to buying an annuity, insurance or an investment. Verify the loan officer’s license and get everything in writing.
- Ignore unsolicited offers. Legitimate lenders do not cold-call seniors with reverse mortgage offers.
- Protect your information. If you did not start the contact, do not give out bank account or Social Security numbers.
- Counseling fees go to the HUD-approved agency, not to a lender or salesperson.
- Verify the license. Look up any loan officer on NMLS Consumer Access; John Thomas is NMLS #38783.
- Get everything in writing, with a real office address and phone number.
- Be wary of “no cost” or “never pay again” pitches. Reverse mortgages have closing costs.
- No one can require you to buy another product. A reverse mortgage must never be tied to an annuity, insurance or an investment.
- Watch for pressure from people around you. A relative, caregiver or advisor who does all the talking, pushes for the loan or wants the money is a warning sign. Take your time; that is what HUD counseling is for.
When Is a Reverse Mortgage Not a Good Fit?
A reverse mortgage is usually the wrong choice if you will move within a few years, want to leave the home free and clear, can’t keep up with taxes and insurance, have too little equity for meaningful money, or only need it to delay a crisis. A HELOC, refinance or sale may fit better.
- You plan to move within 3 to 5 years. The upfront costs are unlikely to pay off; a HELOC, cash-out refinance or selling may fit better.
- You want to leave the home free and clear. The balance grows and reduces what your heirs receive. If you don’t need the cash, consider a HELOC as a backup line instead.
- You can’t reliably pay taxes, insurance and upkeep. If a set-aside can’t cover the gap, the loan may not be approved, and default is a real risk.
- The net amount is too small. After the payoff, MIP, fees and closing costs, a lower-value home with a large mortgage may not leave enough to help. We run the numbers before you pay for counseling.
- Your income already covers your needs. Keeping equity untapped, or holding a HELOC in reserve, may be more flexible.
- A regular refinance fits better. With steady income and good credit, a cash-out refinance may cost less over time, though it has monthly payments.
- It only delays a crisis. If the money only pushes a problem back a few months, it does not solve it.
Who a Reverse Mortgage Helps
- Need. House-rich and cash-poor: a tight budget, medical bills, repairs or a hard-to-keep-up mortgage payment.
- Lifestyle. Doing fine but wants more room each month: no mortgage payment, help for family, travel, or a move to a home that fits retirement.
- Planning. Has savings and wants a standby line of credit for bad market years instead of selling investments when prices are down.
What I ask first on a reverse mortgage call
How long do you plan to stay in the home, and what would you like to happen to it after you? Those two answers decide whether a HECM, a HELOC or a sale makes sense. Then we look at your age, the home’s value and any mortgage balance to see how much would actually be available.
How Do You Get a Reverse Mortgage, Step by Step?
Start with a consultation, complete HUD-approved counseling, apply, get the FHA appraisal, go through underwriting and the financial assessment, then close. On a refinance of your home, funds are released after a 3-day right of rescission. Timing depends on counseling, the appraisal and title.
- Consultation. Call 302-703-0727 or book online. We look at your age, home value and goals and run a preliminary estimate. No commitment.
- HUD-approved counseling. Required before you apply, usually by phone. You receive a certificate that goes with your application; in Delaware the lender must have the counselor’s written certification before closing.
- Application. We complete the HECM application together, using the documents listed below.
- FHA appraisal. Sets the home’s value; required repairs are done before closing or set aside from the loan.
- Underwriting and financial assessment. Credit history, income and assets are reviewed for taxes, insurance and upkeep.
- Closing. Timing depends on counseling, the appraisal and any title or property issues.
- Funding. After the 3-day right of rescission on a refinance, money is paid out the way you chose.
Documents to have ready:
- Government-issued photo ID for each borrower and any non-borrowing spouse
- Social Security number verification
- Your HUD counseling certificate
- Homeowners insurance declarations page (and flood insurance, if required)
- Your most recent mortgage statement, if you have a mortgage
- Property tax bill or records, and HOA statement if there is one
- Income and asset statements for the financial assessment
We work with homeowners across New Castle, Kent and Sussex counties in Delaware, including Wilmington, Newark, Bear, Middletown, Dover, Smyrna, Milford, Lewes and Rehoboth Beach, and in Maryland communities such as Baltimore, Columbia, Annapolis and Silver Spring. See the areas we serve in Delaware and Maryland. You can meet at our Newark office on Chestnut Hill Road, by phone or by video.
Reverse Mortgage FAQ for Delaware and Maryland
Do I lose ownership of my home with a reverse mortgage?
No. You keep title and ownership for as long as you live in the home as your primary residence and meet the loan terms. The lender holds a mortgage lien, just as with a regular mortgage, but you remain the legal owner and can sell, refinance or leave the home to your heirs.
How much money can I get from a reverse mortgage?
It depends on the youngest borrower’s age, current rates and your home’s value up to the 2026 limit of $1,249,125. A reverse mortgage usually provides less than half of the home’s value. For example, a 72-year-old with a $500,000 home and a 45% factor would have about $225,000 before any payoff and closing costs. This is an illustration only.
What happens to a reverse mortgage when I pass away?
The loan becomes due and payable. Your heirs typically have up to 12 months, with possible extensions, to sell the home and keep any remaining equity, pay off or refinance the loan to keep the home, or deed it back to the lender. Because a HECM is non-recourse, they never owe more than the home is worth.
Can my spouse stay in the home if I die first?
An eligible non-borrowing spouse can usually stay and defer repayment if they were married to you at closing, named in the loan documents and live in the home as their primary residence. They must keep paying taxes and insurance and maintain the home, and they cannot draw more money from the loan.
How much does a reverse mortgage cost?
Expect an upfront FHA mortgage insurance premium of 2% of the home value or the HECM limit, whichever is lower, an annual premium of 0.5% of the balance, an origination fee capped at $6,000, normal third-party closing costs, a counseling fee, and interest that is added to the balance. Most costs can be financed into the loan.
Can I get a reverse mortgage on a Delaware condo?
Yes, if the condominium project is FHA-approved or qualifies for FHA single-unit approval. We check the project’s approval status before you spend money on counseling or an application, so you know up front whether your condo works for a HECM.
What happens if I move to assisted living?
The loan becomes due when the last borrower permanently moves out, which HUD generally treats as 12 consecutive months away from the home because of illness. Short hospital, rehab or assisted-living stays do not trigger repayment. If the move is permanent, your family can sell the home, refinance or settle the loan.
Is reverse mortgage money taxable?
The IRS treats the money as loan advances, not income, so it is generally not taxed as income. It can affect needs-based benefits such as SSI and Medicaid if you keep the money past the month you receive it. Talk with a tax or benefits advisor before you decide.
Do you offer jumbo or private reverse mortgages in Delaware or Maryland?
No. We don’t offer private (proprietary) reverse mortgages, often called jumbo reverse mortgages, in Delaware or Maryland. Our clients in both states use the FHA-insured HECM. A home worth more than the 2026 HECM limit of $1,249,125 still qualifies for a HECM; FHA counts the value up to the limit.
Can I take all of my reverse mortgage money in the first year?
Usually not. HUD limits the first 12 months to the greater of 60% of your principal limit, or the amounts that must be paid at closing plus 10% of the principal limit. On an adjustable-rate HECM the rest becomes available after the first year. A fixed-rate HECM pays one lump sum at closing, and any amount left over is not available later.
John R. Thomas is Branch Manager and Division Vice President with the John Thomas Team in Newark, Delaware, and has helped more than 3,000 Delaware and Maryland families finance, refinance and use their home equity over 20+ years, including FHA-insured HECM reverse mortgages for homeowners 62 and older. On a reverse mortgage call he starts with how long the homeowner plans to stay and what they want for the home afterward, and he welcomes adult children and advisors to the conversation.
He holds a BS in Physics Education from the University of Delaware and an MS in Curriculum and Instruction from Delaware State University, and is the author of Your Guide to Buying Your First Home in Delaware. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access. Read more on his loan officer bio page.
Industry recognition: Scotsman Guide Top Originators (2017, 2019, 2020, 2023, 2025, and 2026 Top Dollar Volume); Mortgage Executive Top 1% Mortgage Originators in America (2016, 2017, 2018, 2021); National Mortgage News Top Producers (2018, 2020); National Mortgage Professional Best Military Originators (2019).
Years 3,000+
Buyers Helped DE & MD
Service Area CMP
Certified Mortgage Planner
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com
Schedule Appointment (30 min)
See John Thomas Team on Google for reviews, directions, and local office information.
YouTube | Facebook | Instagram | TikTok | X / Twitter | LinkedIn
See your numbers before you decide
One no-pressure conversation shows about how much may be available, what it costs, what it means for your heirs, and how it compares with a HELOC, a refinance or selling.
Last Updated: November 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
John R. Thomas, NMLS #38783 | John Thomas Team with AnnieMac Home Mortgage | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
AnnieMac Home Mortgage is an Equal Housing Lender. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access.
(c) Copyright John R. Thomas, All Rights Reserved.
