Delaware HELOC Loans: Tap Your Home’s Equity Without Refinancing Your First Mortgage
Delaware HELOC overview: A Delaware HELOC lets you borrow against your home’s equity without touching your first mortgage. HELOC programs available in Delaware start at a 600 credit score, lines run from $25,000 to $750,000 (more on some first-lien lines), and combined loan-to-value can reach 95% with a 720 score on a one-unit primary home. Current as of November 2026.
You have real equity in your home and a first mortgage rate you don’t want to give up. You need cash for a project, for high-rate debt, or just as a cushion, and a cash-out refinance would trade that low rate for today’s. I’m John Thomas, NMLS #38783, and for more than 20 years I’ve helped Delaware homeowners from our Newark office on Chestnut Hill Road. My goal on this page is to show you what a HELOC can do, what it costs and when another option fits better. If you’re buying your next home before selling this one, start with the Delaware bridge loan HELOC instead.
How much equity can you use?
Tell me your home’s rough value and your mortgage balance. I’ll show you the line size and the program that fits, with a soft-pull pre-qualification that does not affect your credit score.
Table of Contents
What Is a Delaware HELOC and How Does It Work?
A HELOC is a line of credit secured by your home that sits behind your first mortgage. You draw what you need during a draw period, often 10 years with interest-only payments, then repay principal and interest over the remaining term, often 20 years. Your first mortgage and its rate stay as they are.
Think of it as a credit line with your house as the collateral. You pay interest only on what you have drawn, you can pay it down and draw again during the draw period, and the rate on a standard HELOC is variable, tied to the prime rate. When the draw period ends, the payment includes principal, so it goes up. A lender can also freeze or reduce a line if the home’s value drops significantly or your finances change materially, under Regulation Z, 12 CFR 1026.40. The Consumer Financial Protection Bureau explains HELOCs the same way.
A home equity loan, sometimes called a HELOAN, is the closed-end version: one lump sum at closing, a fixed rate and a fixed payment, like a second mortgage with a set payoff date. A fixed-rate HELOC sits in between, with a short draw period and a fixed rate on what you borrow.
How Much Can You Borrow With a Delaware HELOC?
Most Delaware homeowners can borrow up to 80% to 95% of their home’s value, minus what they still owe on the first mortgage. The limit depends on your credit score, the property and occupancy: 95% needs a 720 score on a one-unit primary home, as of November 2026. Lines run from $25,000 to $750,000 on most programs.
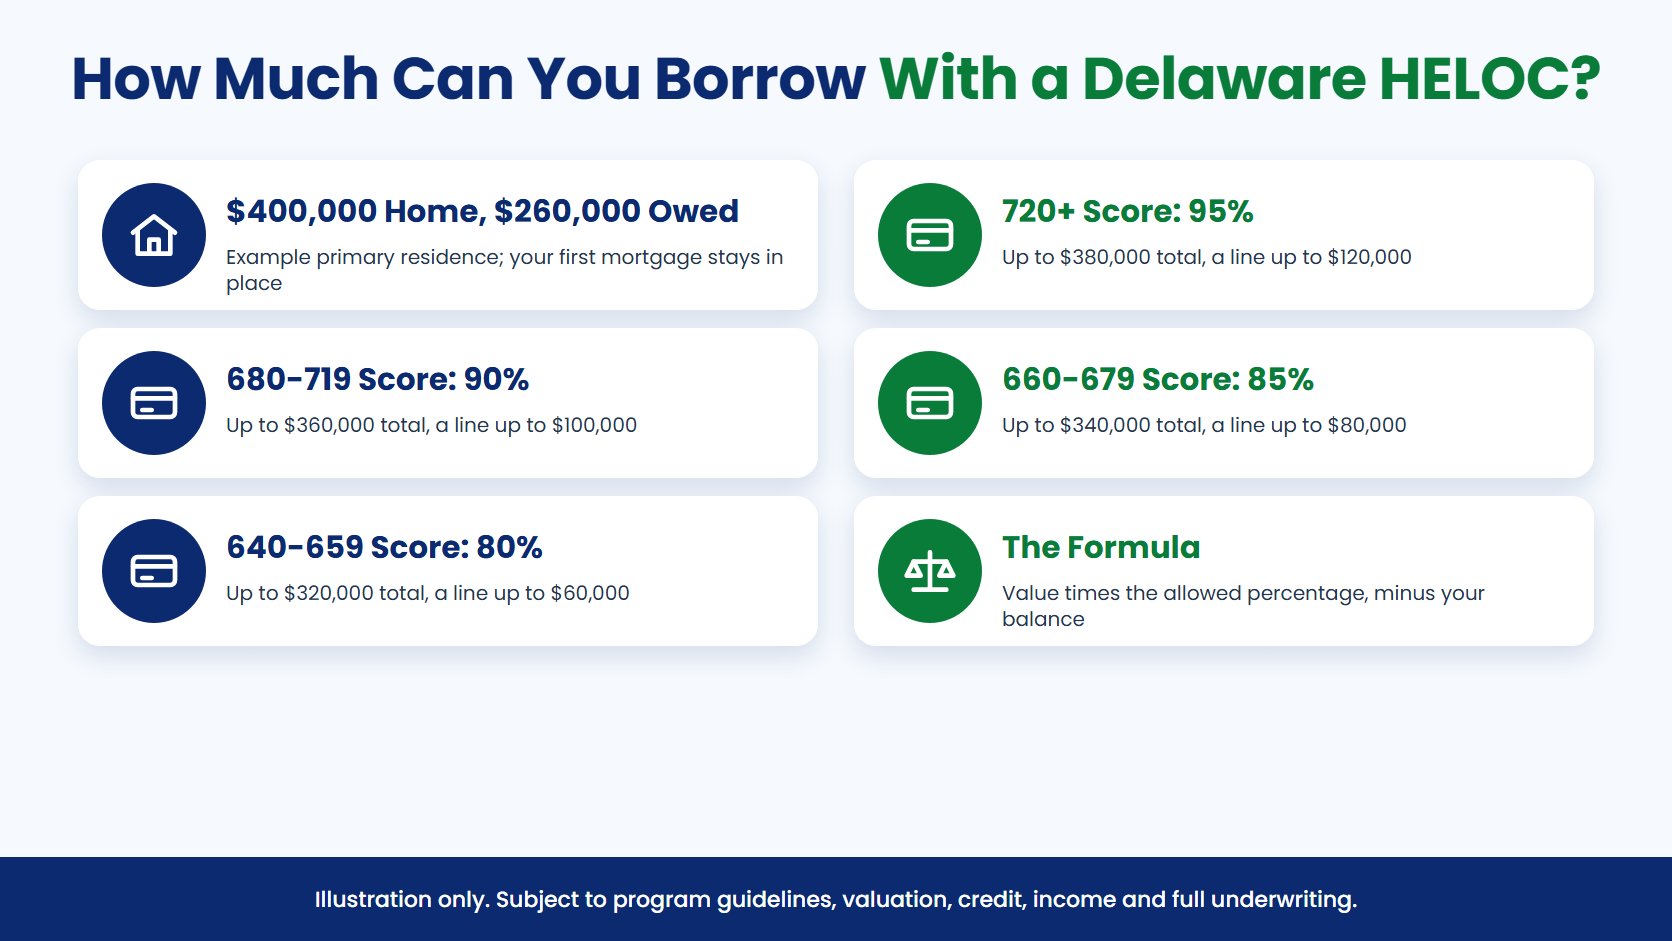
Here is the math on a $400,000 home with a $260,000 first mortgage balance, a primary residence:
| Credit score | Max combined loan-to-value | Total loans allowed | Possible HELOC line |
|---|---|---|---|
| 720 or higher | 95% | $380,000 | Up to $120,000 |
| 680 to 719 | 90% | $360,000 | Up to $100,000 |
| 660 to 679 | 85% | $340,000 | Up to $80,000 |
| 640 to 659 | 80% | $320,000 | Up to $60,000 |
| 620 to 639 | 70% | $280,000 | Up to $20,000 |
| 600 to 619 | 60% | $240,000 | None on this example |
The line is the home value times the allowed percentage, minus the first mortgage balance. This is an illustration only: lower credit tiers also carry smaller maximum lines (for example $400,000 below 640 and $500,000 on most programs below 720), two-unit and three- to four-unit homes have lower limits, and in a declining market the lender can cap the percentage lower. Lines above $750,000, up to $1,000,000, are possible on some piggyback and first-lien HELOCs with a 720 score and 75% or less.
Who Qualifies for a Delaware HELOC?
You need a 600 credit score or higher (640 for higher limits), enough equity to stay within the program’s combined loan-to-value limit, and income that supports the payment, usually a debt-to-income ratio of 43% to 45%. Some programs go to 50%. A primary residence gets the best terms; second homes and rentals need more equity, as of November 2026.
| Property | Credit score | Max combined loan-to-value | Notes |
|---|---|---|---|
| Primary home, 1 unit | 600 / 620 / 640 / 660 / 680 / 720 | 60% / 70% / 80% / 85% / 90% / 95% | Best terms; lines to $750,000 ($400,000 below 640; DTI 45% below 680) |
| Primary home, 2 units | 640 / 680 | 80% / 90% | 3-4 units: 75% with 680 |
| Second home, 1 unit | 640 / 680 | 80% / 90% | Some programs need 700 or more |
| Investment property, 1-4 units | 640 / 700 / 720 | 75% / 85% / 90% | Most flexible program; others 70-80% |
Underwriting also looks at your payment history (no 30-day mortgage lates in the last 12 to 24 months, by program), at least two established credit accounts, and your debt-to-income ratio. A few things rule a property out on the programs we use: manufactured homes and co-ops, and leasehold on most. Condos are fine if the project is warrantable, and some programs allow a non-occupant co-borrower. After a bankruptcy, foreclosure or short sale, most programs follow Fannie Mae waiting periods, and some add a higher score and lower limits.
What I look at first on a HELOC call
Most homeowners who call me about a HELOC right now have a first mortgage rate they don’t want to lose. Before we talk line size, I ask for the current mortgage statement and a rough value, because the combined loan-to-value tier decides the score you need and the line you can get. A homeowner at 81% often qualifies for much more after a few months of payments or a small paydown that puts them in the 80% tier.
Variable HELOC, Fixed-Rate HELOC or Home Equity Loan: Which Fits?
Pick a variable HELOC if you want to draw over time and pay interest only on what you use. Pick a fixed-rate HELOC if you will use most of the money within a few years and want a locked rate. Pick a home equity loan if you know the exact amount today and want one fixed payment.
| Variable HELOC | Fixed-rate HELOC | Home equity loan | |
|---|---|---|---|
| How you get the money | Draw as needed | Initial draw at closing, more during a 3-year draw | One lump sum at closing |
| Rate | Variable, tied to prime | Fixed | Fixed |
| Terms | 10-year draw, 20-year repayment (5/25 or 3/17 on some) | 15, 20 or 30 years | 10, 15, 20, 25 or 30 years; interest-only on some |
| Payment during draw | Interest only on what you use | Principal and interest | Principal and interest |
| Draw at closing | None on some programs; $25,000 to $50,000 or 75% of the line on others | Greater of $25,000 or 75% of the line ($100,000 on $150,000+) | Full amount |
| Minimum | $25,000 line | $25,000 line | $25,000 loan |
| Best for | Projects paid over time, an emergency cushion | A big project with draws over a few years | Debt payoff or a one-time cost |
Terms are from the current matrices of the HELOC lenders we work with, as of November 2026, and can change. The variable rate on a HELOC can rise, so ask how high the cap goes before you sign.
Should You Use a HELOC or a Cash-Out Refinance?
Use a HELOC or home equity loan when your first mortgage rate is lower than today’s rates, because you keep it. A cash-out refinance usually wins only when current rates are near or below your existing rate, or when you want one loan and one payment for the whole balance.

A cash-out refinance replaces your first mortgage with a new, larger one and pays you the difference. Every dollar of the old balance moves to the new rate. A HELOC adds a second, smaller loan on top, so only the new money carries today’s rate. On a home with a 3% first mortgage, that difference is usually larger than the HELOC’s higher rate on a smaller balance.
Watch: John Thomas puts a cash-out refinance, a home equity loan and a HELOC side by side on the same house, using hypothetical rates, and shows when each one can make sense (13:52).
Most Delaware homeowners I work with right now choose the HELOC route for exactly that reason: the existing first-mortgage rate is worth too much to give up. Read more on Delaware conventional loans, including cash-out refinance limits, or the VA cash-out refinance if you are a veteran.
Can Self-Employed Delaware Homeowners Get a HELOC?
Yes. Self-employed homeowners can qualify with tax returns, and some programs accept one year of returns instead of two. Bank statement income works on certain HELOCs at 65% combined loan-to-value, and on closed-end second mortgages up to 90% with a 700 score, as of November 2026.
- One year of tax returns: allowed on some programs when the combined loan-to-value is under 65%, or when the business has been open 5 years or more.
- Bank statements: on a HELOC, 12 or 24 months of statements, a 680 score and 65% combined loan-to-value; on a closed-end second, 12 months of personal or business statements on the full limits (90% at 700, loans to $1,000,000). Self-employed 2 years. More on the Delaware bank statement loan program.
- Asset-based income: qualifying income figured from your assets (assets divided by 84 to 360 months, by program), with a lower combined loan-to-value. Same idea as our asset qualifier loan program.
- 1099 or P&L income: 12 months of 1099s, or a P&L statement at up to 80%, on a closed-end second. The 1099 mortgage loan program explains how lenders count it.
Our Delaware self-employed mortgage guide covers how underwriters read business income on any loan.
Can You Get a HELOC on a Second Home or Rental Property?
Yes, with more equity and a higher score on most programs. A second home can reach 90% combined loan-to-value with a 680 score. A rental of 1 to 4 units can reach 90% with a 720 score, 85% at 700 and 75% from 640 on the most flexible program, as of November 2026.
- Second homes (a beach place in Sussex County, for example): 80% with a 640 score, 90% with 680 on the programs we use; some programs need 700 or more.
- First-lien HELOC on a paid-off rental: up to 80% on a one-unit property with a 640 score, a 1.25 debt service coverage ratio, and an LLC allowed with a personal guarantee.
- Second-lien rental HELOC: lines from $25,000 to $500,000 on 1 to 4 units, no LLC title, up to 15 financed properties; other programs run $50,000 to $250,000 with a 5-year draw.
- Rental-property closed-end second (DSCR): $75,000 to $500,000 qualified on the rent (1.00 debt service coverage), 65% / 75% / 80% at 680 / 700 / 720, LLC allowed with a personal guarantee, with a 1- to 5-year prepayment penalty.
If the rental income has to carry the loan instead of your personal income, a Delaware DSCR loan qualifies on the property’s rent and may fit better.
What Does a Delaware HELOC Cost?
A HELOC costs interest on what you draw plus closing fees, usually an origination or admin fee, title or a property report, and the valuation. Lines up to $400,000 or $500,000 can often use an automated valuation instead of a full appraisal. Some lines also carry a small annual fee, as of November 2026.
- Rate: variable HELOC rates are the prime rate (published by the Federal Reserve H.15 release) plus a margin set by your score, combined loan-to-value and line size. We don’t post rates on this page because they change with prime and your file; call for a quote on your numbers.
- Valuation: automated valuation up to $400,000 on many programs and $500,000 on some (others: $300,000, or an automated or desktop valuation with a property condition report up to $400,000); full appraisal above that.
- Title: a property report on smaller lines, title insurance on larger ones (often above $250,000).
- Ongoing: no prepayment penalty on the programs we use most (a rental DSCR closed-end second can have one); some lines charge an annual maintenance fee.
- Right to cancel: on your primary residence you get 3 business days after signing to cancel (Regulation Z, 12 CFR 1026.23).
Is HELOC Interest Tax-Deductible in 2026?
HELOC interest is deductible only when the money is used to buy, build or substantially improve the home that secures it, and only if you itemize. The One Big Beautiful Bill Act made that rule and the $750,000 mortgage debt limit permanent starting in 2026. Interest on money used for other purposes is not deductible.
The $750,000 limit counts your first mortgage plus any home equity debt used for the home ($375,000 if married filing separately). Keep invoices and contractor agreements that show where the money went. See the IRS summary of the One Big Beautiful Bill provisions and IRS Publication 936, and check with a tax advisor before you file.
Specialty Equity Loans: Renovation, Bridge and Investment HELOCs
A standard HELOC is not the right tool for every equity question. These specialty lines cover the most common exceptions:
Bridge loan HELOC
For buying your next home before you sell this one. It needs a 680 score and up to 80% loan-to-value on the home you are selling, and the home can already be listed. First-lien lines can reach $1,000,000 with a 720 score and under 50% loan-to-value. There is a monthly servicing fee until it is paid off. Full details: Delaware bridge loan HELOC.
Renovation HELOC
For a remodel when today’s equity is not enough. The line is based on up to 95% of the after-renovation value, capped at 125% of the current value and at the renovation cost, from $50,000 to $750,000 with a 640 score and a full appraisal. Contractors are paid from the line. Buying a home that needs work? Compare Delaware renovation loans, including FHA 203k loans.
Closed-end second mortgages with flexible income
For a fixed-rate second mortgage when you qualify with bank statements, 1099s, a P&L or assets instead of tax returns. Loans run from $50,000 to $1,000,000 with 10- to 30-year fixed terms (interest-only on some 20- and 30-year terms at 700 and 70%), from a 660 score. Up to $500,000, the limit is 90% at 700, 85% at 680 and 80% at 660 on a primary home; 85% / 80% / 70% on a second home and 80% / 80% / 70% on a rental. DTI up to 50%, no reserves, non-warrantable condos at 75%, and rural homes up to 10 acres at 70% with a 720 score. Loans over $750,000 are primary, single-family or PUD, full doc or bank statements. It needs 4 years after a bankruptcy, foreclosure or short sale. Full limits by credit score, every income path and the rental version are on our Delaware non-QM second mortgage page.
Building from the ground up instead? See Delaware construction loans.
How Do You Get a Delaware HELOC, Step by Step?
Start with a call and a soft-pull pre-qualification, then apply, have the home valued, clear underwriting and sign. After the 3-day right to cancel on a primary home, the line opens. Timing depends mostly on whether the home needs a full appraisal and how your income is documented.
- Run the numbers. Call 302-703-0727 or book 30 minutes. We look at value, first-mortgage balance, credit and what the money is for, and pick the program.
- Apply and send documents. Your mortgage statement, homeowners insurance, ID and income documents for your path (W-2s and pay stubs, tax returns or bank statements).
- Valuation. Automated valuation on many lines up to $400,000 or $500,000; full appraisal above that.
- Underwriting. The lender reviews credit, income, equity and the property, and we clear any conditions with you.
- Sign and open the line. Sign with a title company or mobile notary; after the 3-business-day right to cancel on a primary home, you can draw (or the home equity loan funds).
When Is a HELOC Not a Good Fit?
A HELOC is usually the wrong choice if you need more than your equity allows, if your income can’t carry a payment that may rise with prime, or if the home is a manufactured home or co-op. In those cases another loan, or waiting, often works better.
- Your current rate is high anyway: a cash-out refinance can put everything at one rate. See Delaware conventional loans.
- You are buying before you sell: use the bridge loan HELOC, which allows a listed home.
- Not enough equity for the project: a renovation HELOC or a renovation loan uses the after-repair value.
- A variable payment would strain your budget: choose the fixed-rate HELOC or home equity loan.
- You only want a lower payment on your first mortgage after a lump sum: a mortgage recast may do it without any new loan.
Before you decide
If your credit score is just below a tier (679 or 719), it can pay to wait a month or two and raise it, because each tier changes both the limit and the rate. See the five factors of credit scoring.
Delaware HELOC FAQ

What credit score do I need for a Delaware HELOC?
Our lowest is 600 on a primary home, capped at 60% combined loan-to-value (70% at 620) and a $400,000 line. From 640 the limit is 80%, and 85% at 660. At 680 the limit rises to 90%, and 720 or higher can reach 95% on a one-unit home. Bank statement income needs 680. Your full file decides the final terms.
Can I use my home equity to pay off credit card debt in Delaware?
Yes. A HELOC or home equity loan can pay off higher-rate cards and loans, and the new payment is often lower. Two cautions: the debt is now secured by your home, and HELOC interest used for debt payoff is not tax-deductible. A fixed-rate home equity loan gives you a set payoff date, which helps if the goal is to have the debt gone by a certain year.
My first mortgage rate is low. Do I have to refinance to get cash out?
No. A HELOC or home equity loan sits behind your first mortgage as a second lien, so your current rate and payment stay exactly as they are. A cash-out refinance replaces the first mortgage, which only makes sense when today’s rate is close to yours or you need to restructure the whole loan.
Is there a minimum draw at closing?
It depends on the program. Some of our variable HELOCs need no draw at closing. Others require one, from $25,000 to $50,000 up to 75% of the line, and fixed-rate HELOCs ask you to draw the greater of $25,000 or 75% of the line at closing ($100,000 on lines of $150,000 or more). Tell us how you plan to use the money and we match the program.
Can I get a HELOC after bankruptcy or foreclosure?
Sometimes. Some programs follow Fannie Mae waiting periods, generally 4 years after a Chapter 7 discharge and 2 years after a Chapter 13 discharge. Others want 4 years after any bankruptcy, foreclosure or short sale, some add limits such as a 700 score and 80% combined loan-to-value, and some never allow a past foreclosure or short sale.
Can I get a HELOC on a manufactured home or a condo?
Condos usually yes, and some programs need no condo questionnaire; a non-warrantable condo can work on a closed-end second at up to 75% combined loan-to-value. Manufactured homes are not eligible on the programs we use, co-ops are excluded, and leasehold is accepted on only a few. If you own a manufactured home, ask about a cash-out refinance instead.
Is there a prepayment penalty or an annual fee?
The HELOC programs we use most have no prepayment penalty and no application or termination fee. The exception is a rental-property (DSCR) closed-end second, which can carry a 1- to 5-year prepayment penalty. Some lines charge a small annual maintenance fee, and every program has closing fees such as origination, title or valuation. We show you the program’s fees in writing before you apply.
How long does a Delaware HELOC take?
It depends mostly on the valuation and your income documents. A line of $400,000 to $500,000 or less valued with an automated valuation often moves faster than one that needs a full appraisal, and full-doc W-2 files are usually quicker than bank statement files. After signing on a primary residence there is a 3-business-day right to cancel before funds are released.
Can I get a HELOC if my home is in an LLC or I own several rentals?
Some first-lien HELOCs and rental-property (DSCR) closed-end seconds allow an LLC with a personal guarantee; many HELOCs do not allow LLC title. Programs allow 10 to 15 financed properties. Rental lines need more equity: 75% from a 640 score, 85% at 700 and 90% at 720 on the most flexible program, on 1 to 4 units.
What happens to my HELOC if I sell or refinance?
The HELOC is paid off from the sale proceeds at closing, like any mortgage on the home. If you refinance the first mortgage and want to keep the line, the HELOC lender has to agree to stay in second position, called a subordination; if not, the line is paid off and closed. We coordinate either one with the title company.
John R. Thomas is Branch Manager and Division Vice President with the John Thomas Team in Newark, Delaware, and has helped more than 3,000 Delaware and Maryland families finance a home over 20+ years, including homeowners who used a HELOC or home equity loan to renovate, pay off debt or buy their next home. On a HELOC, the first number he asks for is the first-mortgage balance, because the combined loan-to-value tier sets both the score needed and the size of the line.
He holds a BS in Physics Education from the University of Delaware and an MS in Curriculum and Instruction from Delaware State University, and is the author of Your Guide to Buying Your First Home in Delaware. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access. Read more on his loan officer bio page.
Years 3,000+
Buyers Helped DE & MD
Service Area CMP
Certified Mortgage Planner
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com
Schedule Appointment (30 min)
See John Thomas Team on Google for reviews, directions, and local office information.
YouTube | Facebook | Instagram | TikTok | X / Twitter | LinkedIn
Keep your first mortgage rate and use your equity
Variable HELOC, fixed-rate HELOC or home equity loan: one call shows you the line size, the program and the fees before you apply.
Last Updated: November 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
John R. Thomas, NMLS #38783 | John Thomas Team with AnnieMac Home Mortgage | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
AnnieMac Home Mortgage is an Equal Housing Lender. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access.
(c) Copyright John R. Thomas, All Rights Reserved.
