Delaware USDA Renovation Loans: Buy a Fixer-Upper and Finance the Repairs (2026)
USDA renovation loan, in one sentence: a USDA guaranteed purchase loan with USDA’s rehabilitation and repair feature, which lets an eligible buyer purchase an existing home in a USDA-eligible area and roll the repair costs into the same zero-down loan, up to 100% of the home’s as-improved appraised value.
Quick overview: Delaware USDA renovation loans let eligible buyers purchase a home in a USDA-eligible area and finance the repairs in one zero-down, 30-year fixed mortgage. Non-structural repairs up to $75,000 use the simpler path; structural work or larger budgets use the full renovation path. Income and location limits apply. Current as of October 2026.
I’m John Thomas. A lot of buyers here in Delaware find a house in a USDA area that is priced right because it needs work – a dated kitchen, a tired roof, a well or septic system near the end of its life – and they assume USDA financing is off the table. It usually is not. USDA’s renovation feature lets you buy that house and finance the repairs in the same loan, with no down payment, as long as you and the property meet the program rules. If USDA financing is new to you, start with our guide to Delaware USDA rural housing loans for income limits and eligibility maps, then come back here for the renovation rules. I’m going to walk you through what USDA allows, what changed in 2025, and how the process actually runs.
Table of Contents
Talk through a USDA renovation scenario with John Thomas:
What Is a USDA Renovation Loan?
A USDA renovation loan is a USDA guaranteed purchase mortgage that includes USDA’s rehabilitation and repair feature. It lets an eligible buyer purchase an existing home in a USDA-eligible area and finance the repairs in the same 30-year fixed loan, with one closing and no down payment, when income and property rules are met.
USDA’s own name for it is Rehabilitation and Repair with Purchase of Existing Dwellings, found in Chapter 12, Section 12.28 of the USDA handbook (HB-1-3555). It runs on USDA’s single-close construction process: the loan closes once, the repair money goes into an escrow account, and it is paid out as the work is completed and inspected.
One point many guides get wrong: this is a purchase feature. If you already own your home, USDA’s rehabilitation and repair feature is not the way to finance repairs. Compare the other renovation loan options instead.
Did the USDA Renovation Repair Limit Change to $75,000?
Yes. As of October 2026, USDA allows up to $75,000 in non-structural repairs, up from $35,000 before USDA’s May 5, 2025 handbook revision. Homes that need structural work, or more than $75,000 of repairs, use the extensive renovation path, which can include up to 10 months of mortgage-payment reserves while the home is unlivable.
This changes real decisions. Under the old rule, a $50,000 kitchen, bath and flooring project was pushed into the more involved structural path just because of its size. Today the same project can stay on the simpler non-structural path, as long as none of the work is structural. Many lender websites still publish the older $35,000 figure and the old six-month reserve limit, so check the date on anything you read.
Source: USDA Rural Development, Rehabilitation and Repair lender training (HB-1-3555, Chapter 12.28), July 2025, and the USDA lender training library.
What Is the Difference Between Non-Structural and Structural USDA Renovation?
The dividing line is the type and size of the work. As of October 2026, non-structural repairs of $75,000 or less need a livable home and no third-party inspector. Structural work, or repairs over $75,000, brings in a qualified inspector, phased inspections, and up to 10 months of payment reserves if you cannot live there.
| Feature | Non-structural repairs | Structural or over $75,000 |
|---|---|---|
| Repair budget | Up to $75,000; no minimum | Over $75,000, or any structural work; total loan limited by the as-improved value |
| Structural work | Not allowed | Allowed – additions, structural alterations, reconstruction |
| Can you live there? | The home must be livable | The home may be unlivable during the work |
| Third-party inspector | Not required by USDA | Required; inspects each phase |
| Mortgage-payment (PITI) reserves | Not applicable | Up to 10 months if the home is not livable |
| Contingency reserve | Up to 10% with utilities on, 15% with utilities off | Allowed; amount confirmed at underwriting |
| Construction period | Typically up to 10 months; the lender may approve an extension | |
USDA program rules as of October 2026 (HB-1-3555, Chapter 12.28). Lender requirements may add to these.
Non-structural means the work does not touch the home’s structure: kitchens and bathrooms, flooring, siding, roofing, windows, paint and similar updates. When the contractor’s estimate is $75,000 or less, USDA requires it to state that the work is non-structural. Moving a load-bearing wall, adding a room or rebuilding a damaged section is structural, whatever the dollar amount.
Who Qualifies for a USDA Renovation Loan in Delaware?
You can qualify if your household income is within USDA’s limit for the county, the home is in a USDA-eligible area, and you will move in as your primary residence within 60 days of closing, as of October 2026. Credit and debt-to-income are reviewed as on any USDA loan, and lenders often look harder at renovation files.
- Household income: at or below USDA’s limit for the county and household size, generally up to 115% of the area median. Current Delaware limits by county are on our USDA rural housing loans page.
- Location: the exact address must be in a USDA-eligible area. Check it on the official USDA eligibility site before you make an offer.
- Occupancy: the home must be your primary residence, and USDA expects you to occupy it within 60 days of closing.
- Citizenship: you must be a U.S. citizen, U.S. non-citizen national, or qualified alien.
- Credit: most lenders look for a 620 minimum credit score, and files at 640 and above generally move through USDA’s automated underwriting system. Renovation loans can carry a higher lender minimum, so we confirm the current requirement for your file before you rely on it.
- You cannot be your own contractor: USDA does not allow the borrower to act as the general contractor.
First-time buyers often ask whether they also need down payment help. Because USDA requires no down payment, most USDA renovation buyers only need funds for closing costs, which can sometimes be covered by seller credits or financed when the as-improved appraisal supports it. Our Delaware first-time home buyer guide covers the rest of the process.
What Kind of Property Qualifies for a USDA Renovation Loan?
The home must be an existing single-family dwelling in a USDA-eligible area that you will live in, and its foundation must stay in place and be reused. The house can even be taken down to that foundation and rebuilt. Investment properties, income-producing changes and repairs to condominium units are not eligible as of October 2026.
A few property points come up often. Manufactured homes follow USDA’s separate manufactured-housing rules, covered on our USDA manufactured home loans page. If there is no house to renovate and you want to build from the ground up, the right tool is a USDA one-time close construction loan. And if unpermitted work is discovered before closing, USDA expects proper certification of that earlier work.
What Repairs and Renovations Can You Finance?
Most work that makes the home safer, more livable or more efficient can be financed: kitchens, bathrooms, flooring, siding, accessibility changes, energy and weatherization upgrades, a new garage, septic systems and wells, and health-and-safety repairs. Structural additions and reconstruction are allowed on the structural path, subject to USDA and lender review.
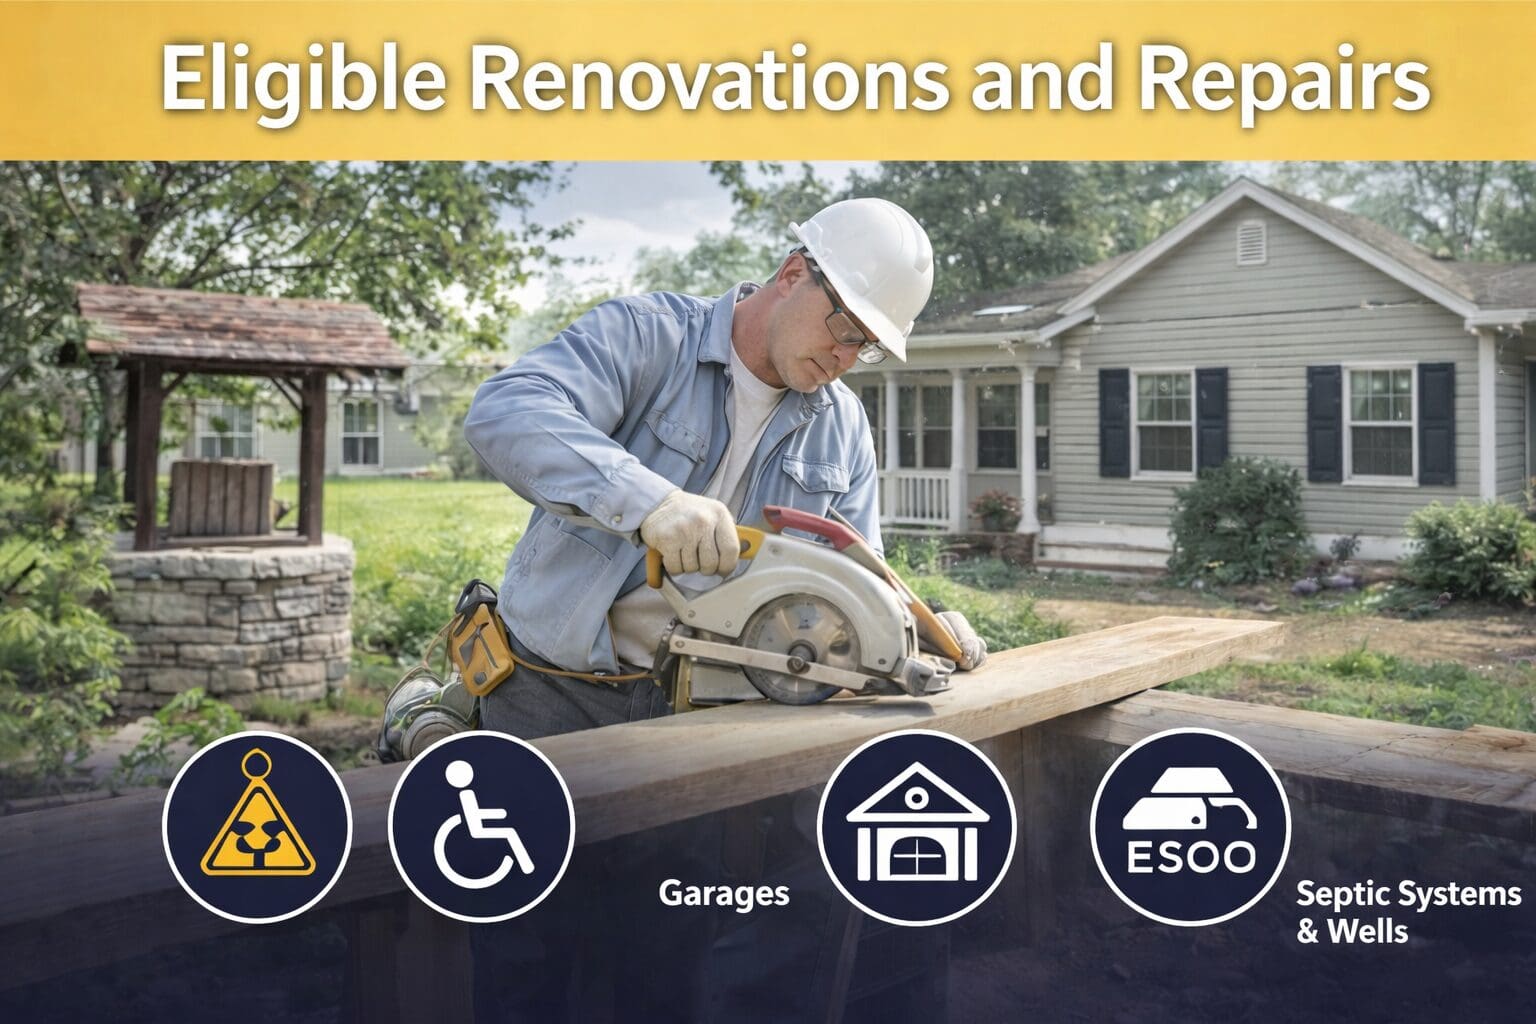
- Kitchen and bathroom remodels, interior flooring and other modernization
- Accessibility changes for a household member with a disability
- Energy conservation and weatherization improvements
- A new garage, attached or detached
- Repair or installation of a septic system or well
- Repairs that remove health or safety hazards
- Repairs to existing amenities
- Additions, structural alterations or reconstruction (structural path)
If the work stays within the approved scope, small changes after closing can be acceptable. USDA’s own training example: unused contingency money may go toward new kitchen appliances, because that does not change the project’s scope or the as-improved value.
What Renovations Are Not Allowed With a USDA Renovation Loan?
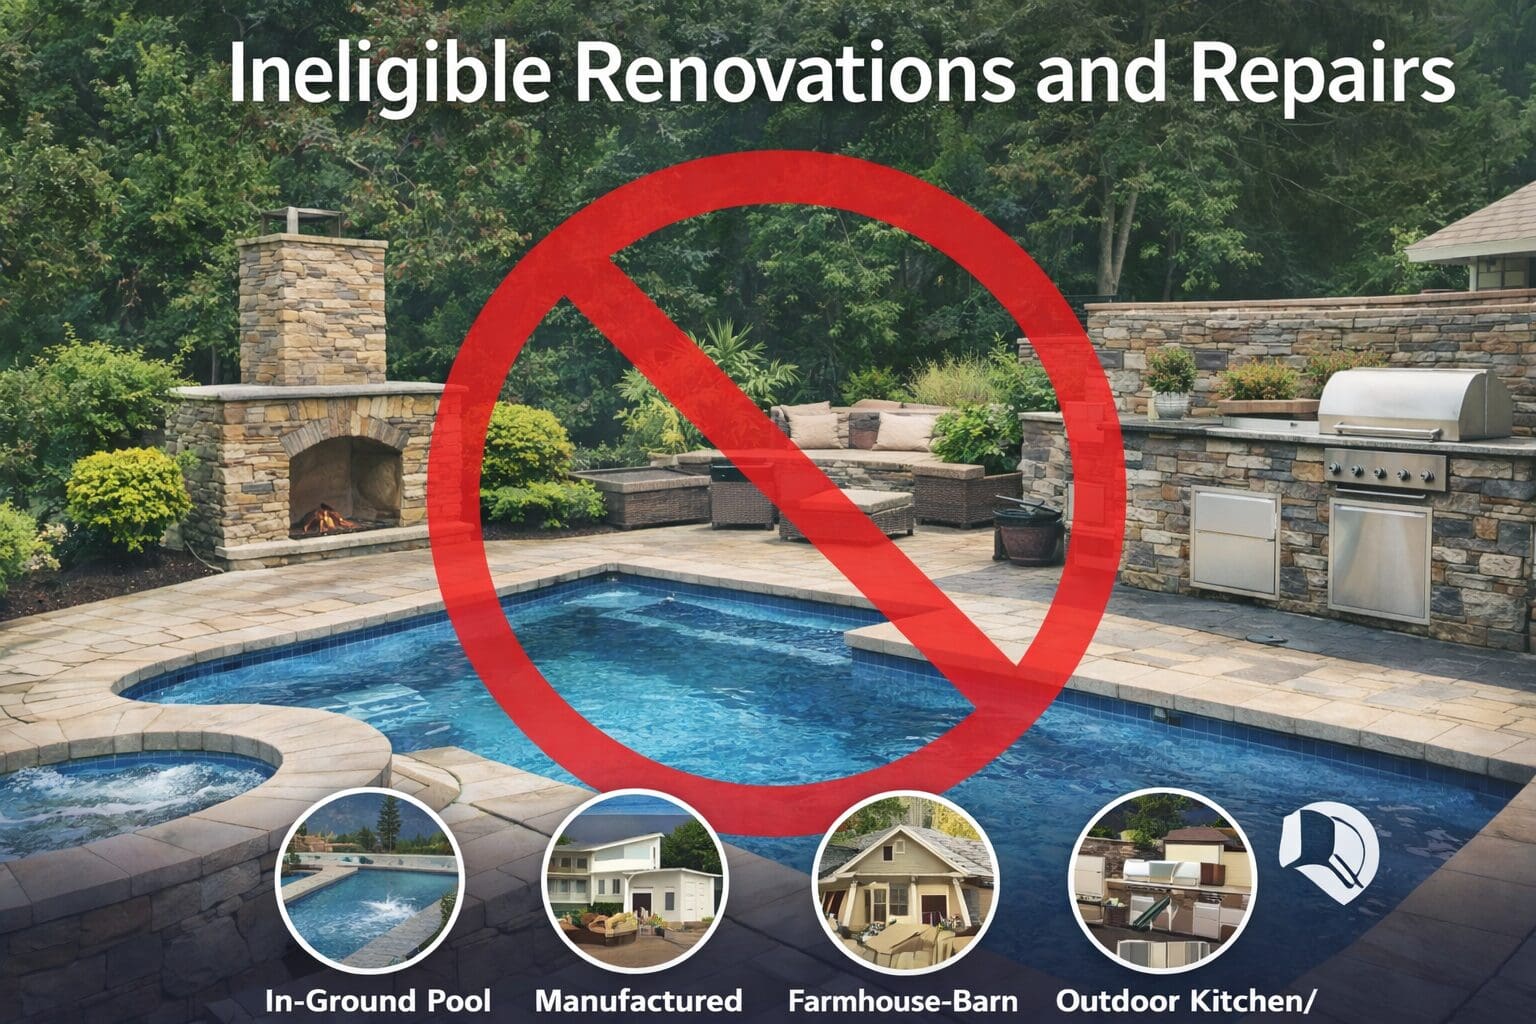
USDA does not finance luxury or income-producing work. As of October 2026 that includes new swimming pools, hot tubs and saunas, outdoor kitchens and exterior fireplaces, turning a barn or outbuilding into a house, repairs to condominium units or common areas, and any change that lets the property produce income.
- Investment properties
- Alterations that allow the property to produce income
- New in-ground pools, hot tubs or saunas
- Converting a barn, outbuilding or other structure into a single-family home
- Luxury items such as exterior fireplaces and outdoor kitchens
- Repairs to condominium units
- Repairs or improvements to common areas such as community rooms or playgrounds
This list also applies after closing. USDA’s training gives the example of a buyer who wants to swap a planned kitchen update for a covered patio with an outdoor kitchen: that change order is not acceptable, because an outdoor kitchen is a luxury item.
How Much Can You Borrow With a USDA Renovation Loan?
As of October 2026, you can borrow up to 100% of the home’s as-improved appraised value – what the appraiser expects it to be worth after the repairs. That covers the purchase price plus repair costs up to that value, with USDA’s upfront guarantee fee financed on top. There is no down payment and no set USDA loan limit.
The as-improved appraisal is what makes this loan work. The appraiser reviews the contractor’s plans and bid, then values the home as if the work were finished. See how a home appraisal works for the basics.
A hypothetical example (not a real client)
Say a buyer finds a three-bedroom ranch in a USDA-eligible part of Kent County for $250,000. The contractor bids $40,000 for a kitchen, two baths and new flooring – all non-structural – and a 10% contingency adds $4,000, for a total of $294,000.
If the appraiser values the finished home at $300,000, the $294,000 fits within the as-improved value, and the upfront guarantee fee can usually be financed on top. If the as-improved value came in at $285,000 instead, the buyer would need to trim the scope, renegotiate the price or bring the difference to closing.
Figures are illustrative only. Your loan amount depends on the appraisal, USDA income limits, your debt-to-income ratio and full underwriting.
How Does the USDA Renovation Loan Process Work?
It runs like a home purchase with a construction phase attached. You get preapproved, confirm the address is USDA-eligible, make an offer, get a detailed fixed-price contractor bid and an as-improved appraisal, then close once. After closing, the repair money sits in escrow and is released as completed work is inspected.
- Get preapproved. We review income, credit and USDA household income limits before you shop.
- Confirm the address. Run each property through the USDA eligibility site; maps change.
- Make an offer. Build in time for the contractor bid and the as-improved appraisal.
- Get a detailed contractor bid. It becomes a fixed-price contract that must match the itemized estimate.
- Inspector review (structural path). A qualified inspector reviews the scope when the work is structural or over $75,000.
- As-improved appraisal. The appraiser values the home as if the repairs were complete.
- Close once. The purchase and the repair funds close together; the repair money goes into escrow.
- Renovate and inspect. Funds are released in stages as completed work is inspected, typically within about 10 months.
- Final inspection. Once the work is complete and signed off, any unused reserves are handled under USDA rules.
The goal is to make the process as simple as possible, and most of the delays I see happen before closing, not after. The bid, the scope and the appraisal have to agree with each other, so we line them up early rather than discovering a gap in the last week of the contract.
How Are Contractors Chosen and Paid on a USDA Renovation Loan?
You pick a qualified contractor who meets lender and USDA requirements, but you cannot act as your own general contractor. The contractor signs a fixed-price contract that matches the detailed bid. Repair funds are held in escrow and paid in stages after each phase is inspected, on a draw schedule the lender sets.
The exact draw mechanics – how many draws, whether any money is advanced for materials, and how much is held back until final sign-off – are set by the lender that manages the renovation, not by USDA. We walk you and your contractor through the current schedule before you sign the contract, so nobody is surprised once the work starts.
If the work runs over budget, the contingency reserve covers it first. Costs beyond the contingency are generally the borrower’s responsibility unless the scope is reduced, and any change order still has to stay within the approved scope and the as-improved value.
How Does a USDA Renovation Loan Compare to FHA 203(k), HomeStyle and VA Renovation?
USDA renovation is the only one of the four that pairs no down payment with no military-service requirement, but it is limited to USDA-eligible areas and household income limits. FHA 203(k) works anywhere with a low down payment, HomeStyle follows conventional rules, and VA renovation is for eligible veterans.
| Loan | Down payment | Where | Income limit | Often the better fit when… |
|---|---|---|---|---|
| USDA renovation | None | USDA-eligible areas only | Yes, by county | The home is in an eligible area and income is within the limit |
| FHA 203(k) | 3.5% minimum for most buyers | Anywhere | No | The home is outside USDA areas or income is over the limit |
| Fannie Mae HomeStyle | Conventional rules | Anywhere | No | You have stronger credit or want upgrades USDA does not allow |
| VA renovation | None for eligible veterans | Anywhere | No | You are a VA-eligible veteran or service member |
Each of these has its own guide: FHA 203(k) rehab loans, the Delaware HomeStyle renovation loan, the Freddie Mac CHOICERenovation loan and the Delaware VA renovation loan.
Using a USDA Renovation Loan in Delaware and Maryland
Most USDA-eligible addresses in Delaware are in Kent County, Sussex County and the rural or suburban edges of New Castle County. Communities in and around Dover, Milford, Harrington, Felton, Camden-Wyoming, Georgetown, Seaford, Laurel, Millsboro and Townsend often include eligible parcels, but eligibility is decided address by address. Buyers in Kent County can start with our Dover Delaware mortgage loans and Milford Delaware mortgage loans pages.
Two changes catch buyers off guard. Middletown lost USDA eligibility on June 4, 2018, and Smyrna lost it for closings on and after October 1, 2023, yet older listings still describe both as USDA towns. If you are shopping in or near Middletown or Smyrna, check the exact address before you count on USDA financing. We also lend in Maryland, where the same address-level check applies.
In my experience, the homes in USDA areas that need work most often need the systems rural houses depend on – a well, a septic system, an aging roof or heating system. Those are all on USDA’s eligible list, and the first question I ask is whether the repairs are cosmetic or structural, because that one answer decides whether an inspector is involved, how long the work can run and whether you can live in the home while it gets done.
When Is a USDA Renovation Loan Not a Good Fit?
It is usually not the right loan if the home is outside a USDA-eligible area, your household income is over the county limit, the property is a condo or an investment home, you want a pool or other luxury upgrade, or you plan to do the work yourself. Each of those points to a different renovation loan.
- The address is not USDA-eligible. An FHA 203(k) loan works anywhere with a low down payment.
- Your household income is over the USDA limit. FHA 203(k) and HomeStyle have no income cap.
- You want a pool, outdoor kitchen or other luxury upgrade. A HomeStyle renovation loan allows a broader range of improvements.
- You already own the home. USDA’s feature is for purchases; ask us about refinance-based renovation options.
- You want to do the work yourself. USDA does not allow the borrower to act as general contractor.
- There is no house, or the foundation is gone. Look at the USDA one-time close construction loan instead.
Be honest with yourself about the scope, too. If the contractor’s bid is likely to grow well beyond the contingency, it is better to find that out before you close than halfway through the project.
USDA Renovation Loan FAQ
Can I get a USDA renovation loan with no down payment?
Yes. USDA renovation loans are 100% financing for eligible buyers: the loan can cover the purchase price plus eligible repair costs up to the home’s as-improved appraised value, and the USDA upfront guarantee fee can be financed on top. You will still have closing costs, which may be covered by seller credits or financed when the appraisal supports it.
Can I use a USDA renovation loan to refinance the home I already own?
No. USDA’s rehabilitation and repair feature is tied to the purchase of an existing home. If you already own your home and want to finance repairs, other renovation programs such as FHA 203(k) or a conventional renovation loan may fit, depending on your equity and credit. We can compare them for your situation.
What credit score do I need for a USDA renovation loan in Delaware?
Most lenders look for a credit score of at least 620 for USDA loans, and files at 640 and above generally move through USDA’s automated underwriting system. Renovation loans can carry a higher lender minimum because of the construction phase, so we confirm the current requirement against your full file before you rely on a number.
Can I do some of the renovation work myself?
Not as the general contractor. USDA does not allow the borrower to act as the general contractor on a renovation loan. The work is done by a qualified contractor under a fixed-price contract that matches the detailed bid. If you plan to do the work yourself, a USDA renovation loan is usually not the right fit.
Can I live in the home while the repairs are being done?
On the non-structural path, the home has to be livable, so most buyers move in and live there during the work. On the structural path the home may be unlivable, and the loan can include up to 10 months of mortgage-payment reserves, or reserves until an inspector confirms the home is livable, as of October 2026.
What happens if the repairs cost more than expected?
The contingency reserve covers overruns first – up to 10% on non-structural projects with the utilities on, or 15% with the utilities off, as of October 2026. Costs beyond the contingency are generally the borrower’s responsibility unless the scope is reduced, and change orders must stay within the approved scope and the as-improved value.
Does a USDA renovation loan work for a condo or a manufactured home?
Repairs to condominium units are not eligible for USDA’s renovation feature. Manufactured homes follow USDA’s separate manufactured-housing rules, so a renovation project on one is reviewed differently. If you are looking at either property type, call us before you make an offer so we can point you to the program that fits.
My household income is slightly over the USDA limit. Do I have other options?
Yes. USDA’s income limit is strict, so a household even slightly over the county limit does not qualify. FHA 203(k) and Fannie Mae HomeStyle renovation loans have no household income cap, so they are the usual next step. Each has its own down payment and credit rules, which we can compare for your scenario.
Can I use a USDA renovation loan in Middletown or Smyrna?
Usually not in town. Middletown lost USDA eligibility on June 4, 2018, and Smyrna lost it for closings on and after October 1, 2023, although some nearby rural addresses may still qualify. Check the exact address on the USDA eligibility site, or send it to us, before you count on USDA financing.
How long do I have to finish the renovation?
USDA’s construction period is typically up to 10 months, and the lender may approve an extension when there is a good reason, as of October 2026. Smaller non-structural projects often finish well inside that window. A realistic contractor schedule, agreed before closing, is the best way to stay on time.
About John Thomas
Branch Manager & Division Vice President of Sales, John Thomas Team with AnnieMac Home Mortgage
I’m John Thomas, Branch Manager and Division Vice President of Sales with the John Thomas Team in Newark, Delaware. For more than 20 years I’ve helped Delaware and Maryland buyers finance homes, including fixer-uppers that other buyers walked away from, and I’ve educated more than 3,000 buyers along the way.
With renovation files, the step I never skip is lining up the contractor’s bid with the appraiser’s as-improved value before the offer goes firm – when those two numbers disagree, the whole deal stalls. I hold a B.S. in Physics Education from the University of Delaware and an M.S. in Curriculum and Instruction from Delaware State University.
State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access.
Mortgage content reviewed by John R. Thomas, NMLS #38783. See more about John Thomas, Delaware Mortgage Loan Officer.
Years
Buyers Educated
Service Area
Certified Mortgage Planner
248 E Chestnut Hill Rd, Newark, DE 19713
Phone: 302-703-0727 | Email: team@johnthomasteam.com
John R. Thomas, NMLS #38783 | Schedule Appointment
See John Thomas Team on Google for reviews, directions, and local office information.
YouTube | Facebook | Instagram | TikTok | X / Twitter | LinkedIn
Ready to look at a USDA fixer-upper?
Send us the address and the repair list. We will confirm USDA eligibility, walk through the non-structural or structural path, and map out the bid and appraisal before you make an offer.
Last Updated: October 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783. This page is educational and is not a commitment to lend; all loans are subject to borrower qualification, property eligibility and full underwriting review.
John R. Thomas, NMLS #38783 | John Thomas Team with AnnieMac Home Mortgage | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
AnnieMac Home Mortgage is an Equal Housing Lender. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access.
(c) Copyright John R. Thomas, All Rights Reserved.
