
DSHA Keys4You Home Loan Delaware: 4% Down Payment Assistance (2026)
Updated for 2026 DSHA Delaware Mortgage Program guidelines · By John Thomas, NMLS #38783 · DSHA Approved Lender
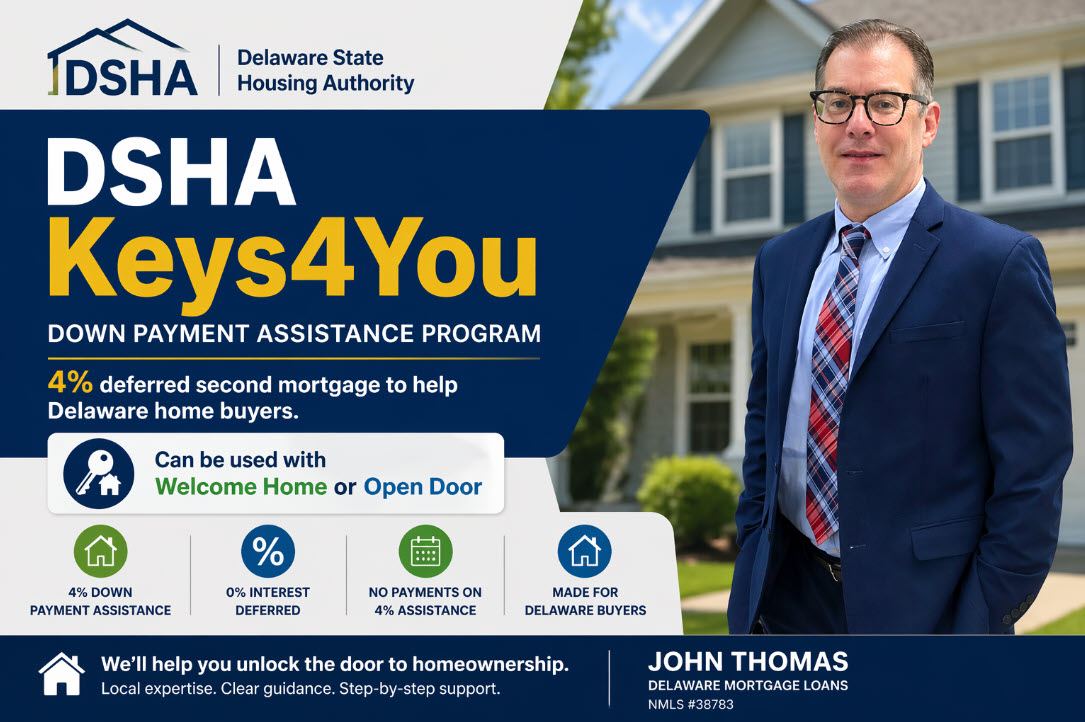
Keys4You gives Delaware buyers 4% down payment assistance with no monthly payment – available statewide to both first-time and repeat home buyers through DSHA-approved lenders.
DSHA Keys4You Quick Answer: The DSHA Keys4You Home Loan is a zero-interest deferred second mortgage equal to 4% of your first mortgage loan amount for down payment and closing cost assistance — with no monthly payment. Keys4You is the only DSHA DPA (alongside the smaller 3% First State) that pairs with both Welcome Home and Open Door, making it the largest DPA available to Delaware repeat buyers. Minimum 620 credit score. Available statewide in New Castle, Kent, and Sussex counties through DSHA-approved lenders like the John Thomas Team with AnnieMac Home Mortgage. Call 302-703-0727.
I’m John Thomas, NMLS #38783, Branch Manager and Division Vice President of Sales with the John Thomas Team with AnnieMac Home Mortgage in Newark, Delaware. I’ve been helping Delaware home buyers use DSHA down payment assistance programs for more than 20 years and have closed over 3,000 mortgages across New Castle, Kent, and Sussex counties. In April 2026, DSHA launched the new Delaware Mortgage Program – a single rebrand event that renamed Home Again to Open Door, branded the existing 4% DPA as Keys4You, opened it to buyers under both Welcome Home AND Open Door, and launched the new Take5 (5%) DPA under Welcome Home. Before that April 2026 rebrand, the 4% DPA was only available with Home Again (now Open Door). That single change is why Keys4You has quickly become the DPA I recommend most often for Delaware buyers who want real help at the closing table without the tighter eligibility rules of the 5% Take5. It lands right between the 3% First State Home Loan and the 5% Take5 – but what makes it genuinely unique is that it’s one of only two DPAs that works for both first-time AND repeat Delaware buyers. If you’ve owned a home before and you need real help at the closing table, this is your maximum DSHA assistance. On this page, I’m going to walk you through exactly how Keys4You works, who qualifies, real dollar examples at $300K, $400K, and $500K purchase prices, and how it compares to every other DSHA DPA option in 2026.
Updated for the April 2026 Delaware Mortgage Program rebrand. This page reflects DSHA’s current product structure: Welcome Home and Open Door as the two first mortgages, with Smart Start (no DPA), First State (3% DPA), Keys4You (4% DPA), Take5 (5% DPA, Welcome Home only), and Diamond in the Rough (5% DPA + FHA 203k, Welcome Home only) as the DPA options. The April 15, 2025 income-counting rule change is also reflected. Older pages that reference “Home Again,” “Preferred Plus,” “Delaware Diamond,” or “Kiss Your Landlord Goodbye” are working from outdated information — the Kiss Your Landlord Goodbye campaign was retired in DSHA’s April 2026 rebrand to the Delaware Mortgage Program at destatehousing.com.
See If You Qualify for the DSHA Keys4You 4% DPA
Get 4% toward your down payment and closing costs with the John Thomas Team – Delaware’s DSHA-approved lender for 20+ years. I’ll review your income, credit, county, and purchase goal, confirm Keys4You eligibility, and show you exactly how much assistance you’ll receive and what you’ll need to bring to closing. No pressure, no obligation.
Table of Contents
DSHA Keys4You at a Glance
| Assistance amount | 4% of your first mortgage loan amount |
| Interest rate | 0% (zero interest for the full term) |
| Monthly payment | None (deferred second mortgage) |
| Repayment due | Sale, refinance, transfer of title, or when the home is no longer your primary residence |
| First mortgage required | DSHA Welcome Home OR DSHA Open Door (FHA, VA, USDA, or Conventional) |
| Buyer type | First-time AND repeat buyers (depending on which first mortgage you use) |
| Minimum credit score | 620 (8-hour HUD counseling required under 660) |
| Income limit (Welcome Home, 1-2 person, non-targeted) | $122,700 New Castle County / $111,400 Kent & Sussex |
| Property location | Delaware primary residence only |
| Keys4You launch / rebrand | April 2026 Delaware Mortgage Program rebrand (named the prior 4% DPA “Keys4You” and opened it to both Welcome Home and Open Door) |
What Is the DSHA Keys4You Home Loan?
The DSHA Keys4You Home Loan is a down payment and closing cost assistance program from the Delaware State Housing Authority. It is structured as a zero-interest deferred second mortgage equal to 4% of your final first mortgage loan amount. That 4% can be applied toward your down payment, your closing costs, or a combination of both – whatever your specific deal requires.
Keys4You has a specific history that’s worth understanding. DSHA originally offered a 4% DPA option, which was retired and then reintroduced in 2025 – but at that point it had no official product name and was exclusive to the Home Again first mortgage track. First-time and repeat buyers used 4% only by going through Home Again. Then in April 2026, DSHA launched the Delaware Mortgage Program – a single rebrand event that did several things at once: retired the longtime “Kiss Your Landlord Goodbye” campaign, consolidated all program information at destatehousing.com, renamed Home Again to Open Door, branded the 4% DPA as Keys4You and opened it to buyers under both Welcome Home AND Open Door, and launched the new Take5 (5%) DPA under Welcome Home. Per DSHA Director Matthew Heckles’ announcement: “The launch of the Delaware Mortgage Program replaces the longtime homeownership campaign and website, ‘Kiss Your Landlord Goodbye.’ All single-family mortgage lending information will now live under the DSHA brand and website, destatehousing.com.” Opening Keys4You to Welcome Home is the change that matters most for buyers: Keys4You is now the largest DPA available to first-time buyers under Welcome Home (other than the 5% Take5) and the largest DPA available to repeat buyers under Open Door, full stop.
Because Keys4You is a deferred second mortgage, you make no monthly payment on the 4%. You only repay the balance if and when one of four things happens: you sell the home, you refinance the first mortgage, you transfer the title, or the home stops being your primary residence. If you stay in the home and never refinance, you never write a check for the Keys4You loan – it simply sits in second position behind your first mortgage until one of those triggering events occurs.
Why Keys4You Matters: The Only High-Tier DPA for Delaware Repeat Buyers
Here’s the single most important thing to understand about Keys4You, and it’s the point most national lender websites completely miss: Keys4You is the only 4% or higher DPA that works if you’re not a first-time home buyer. Under DSHA’s Delaware Mortgage Program, the 5% Take5 and the 5% Diamond in the Rough (FHA 203k) are restricted to the Welcome Home track – meaning you have to be a first-time buyer or a qualified veteran to use them. If you’ve owned a home in the last three years and you’re buying under Open Door, your DPA choices collapse down to just two: the 3% First State or the 4% Keys4You.
For a repeat Delaware buyer who needs real help at the closing table, Keys4You is the maximum assistance DSHA currently offers. That matters because repeat buyers often have built equity in a prior home but have tied up cash in the move, renovations, temporary housing, or moving expenses. An extra 1% of DPA on a $400,000 loan is $4,000 – real money that stays in your pocket at closing.
Keys4You is also a strong option for first-time buyers under Welcome Home who don’t want to be locked into the lower income limits or the FHA 203k requirement of the 5% programs. You get 4% DPA with the more flexible underwriting profile of Welcome Home + a standard FHA, VA, USDA, or Conventional loan. For a lot of first-time buyers, that’s the right balance between “maximum help” and “least complication.”
How Much Does Keys4You Actually Give You? Real Delaware Examples
Keys4You is calculated as 4% of your final first mortgage loan amount – not 4% of the purchase price. That distinction matters because FHA and DSHA roll the upfront mortgage insurance premium into the loan, which actually increases your loan amount slightly (and therefore slightly increases your Keys4You assistance). Here are three real-world scenarios across common Delaware price points.
| Purchase Price | Loan Type | Base Loan Amount | Keys4You 4% DPA | What It Covers |
|---|---|---|---|---|
| $300,000 | DSHA Welcome Home FHA (3.5% down) | ~$294,566 (incl. UFMIP) | ~$11,783 | Full 3.5% down payment ($10,500) + ~$1,283 toward closing |
| $400,000 | DSHA Open Door FHA (3.5% down) | ~$392,755 (incl. UFMIP) | ~$15,710 | Full 3.5% down payment ($14,000) + ~$1,710 toward closing |
| $500,000 | DSHA Open Door Conventional (3% down) | $485,000 | $19,400 | Full 3% down payment ($15,000) + $4,400 toward closing |
Notice what happens at the $500,000 price point with a Conventional 3%-down loan: the 4% Keys4You DPA ($19,400) is larger than the required 3% down payment ($15,000), so the leftover $4,400 goes straight toward closing costs. When you combine Keys4You with seller-paid closing costs – which on a $500K Delaware purchase you can typically negotiate up to 3% ($15,000) – a lot of Delaware buyers can get to the closing table with less than $3,000 out of pocket. That’s the kind of scenario I run for buyers every week, and Keys4You makes it possible.
Who Qualifies for the DSHA Keys4You Home Loan in Delaware?
Keys4You has two layers of qualification. First, you have to qualify for one of the DSHA first mortgage programs – either Welcome Home (for first-time buyers) or Open Door (for first-time and repeat buyers). Second, you have to meet the baseline Keys4You guidelines, which are almost identical to the first mortgage guidelines.
The core eligibility requirements for Keys4You in 2026 are straightforward. You need a minimum 620 credit score for all borrowers on the loan. If your credit score is below 660, you’ll need to complete 8 hours of HUD-approved homebuyer counseling before closing – I can point you to Delaware-approved counselors, and many buyers complete this online. The home must be your primary residence in Delaware (New Castle, Kent, or Sussex County), and you must fall under DSHA’s income limits for either Welcome Home or Open Door depending on which track you use.
One important 2025 rule change to flag: as of April 15, 2025, DSHA changed how it counts income. For the Welcome Home program, DSHA now only counts the income of borrowers actually listed on the Note and Mortgage – not every adult in the household. For the Open Door program, only the qualifying income used on the loan application (Form 1003) counts. Your household size still determines which income-limit tier applies to you, but only certain incomes get added up. This is a big improvement over the old rule, which counted every adult in the home. If you were told you didn’t qualify before April 2025, it’s worth running your numbers again. Note that this April 2025 income rule change took effect a year before the April 2026 Delaware Mortgage Program rebrand – they were two separate program updates.
What Are the 2026 DSHA Income Limits for Keys4You?
Income limits depend on which first mortgage program you’re pairing with Keys4You. Welcome Home has lower income limits but a lower interest rate. Open Door has higher income limits but a slightly higher interest rate. Here are the current non-targeted-area limits for 2026.
| Household Size | Welcome Home (NCC) | Welcome Home (Kent & Sussex) | Open Door (NCC) | Open Door (Kent & Sussex) |
|---|---|---|---|---|
| 1-2 person | $122,700 | $111,400 | $147,240 | $133,680 |
| 3+ person | $141,105 | $128,110 | $184,050 | $167,100 |
A few quick notes on the limits. If you’re buying in a DSHA-designated targeted area, both the income limits and purchase price limits are significantly higher, and the first-time buyer requirement is waived – meaning repeat buyers can use Welcome Home in targeted areas and access the lower Welcome Home interest rate. Qualified veterans are also exempt from the first-time buyer rule statewide. Purchase price limits in non-targeted areas are $659,385 in New Castle County and $566,354 in Kent & Sussex, rising to $805,916 and $692,211 in targeted areas. Call me at 302-703-0727 and I’ll confirm the exact tier for your household size, county, and target-area status.
How Does Keys4You Compare to First State, Take5, and Diamond in the Rough?
DSHA’s Delaware Mortgage Program now offers four different DPA options under Welcome Home and Open Door, each with different pairing rules, different assistance percentages, and different best-fit buyer profiles. Here’s the full side-by-side I walk every client through.
| Program | DPA % | Pairs With | Who It’s For | Min Credit |
|---|---|---|---|---|
| First State | 3% | Welcome Home + Open Door | Buyers who need just enough DPA to cover down payment only | 620 |
| Keys4You | 4% | Welcome Home + Open Door | Repeat buyers under Open Door, or first-time buyers who want max DPA without FHA 203k or 5% restrictions | 620 |
| Take5 | 5% | Welcome Home ONLY | First-time buyers who need maximum down payment + closing cost help | 620 |
| Diamond in the Rough | 5% | Welcome Home FHA 203k ONLY | First-time buyers purchasing a fixer-upper needing repairs | 640 |
Here’s how I usually help buyers pick. If you’re a repeat buyer or your household income runs above the Welcome Home limits, you’re choosing between First State (3%) and Keys4You (4%) – and Keys4You almost always wins unless you have very minimal closing costs and want the tiny DPA balance to keep your second-lien as small as possible. If you’re a first-time buyer with a credit score of 640+ and you’re buying a fixer-upper, Diamond in the Rough (5%) is the best fit because you’re getting 5% DPA plus up to $35,000 in renovation financing rolled into one loan via FHA 203(k) Limited. If you’re a first-time buyer buying a move-in-ready home and you qualify under Welcome Home income limits, Take5 (5%) gives you the most DPA – but Keys4You (4%) is a close second if you want a simpler structure or slightly different underwriting.
Not sure which DSHA program is right for you?
I’ll compare First State, Keys4You, Take5, and Diamond in the Rough based on your income, credit, and cash to close — and tell you exactly which pairing puts the most money in your pocket.
Which Loan Types Can I Use With Keys4You?
Keys4You is a second mortgage – it has to attach to a first mortgage. Under the Delaware Mortgage Program, Keys4You pairs with any of the four government and conventional loan types DSHA approves for Welcome Home and Open Door. That gives you meaningful flexibility depending on your credit profile, down payment situation, and property type.
- FHA Loan + Keys4You – the most common combo. 3.5% minimum down with Keys4You covering it all, plus extra toward closing. Credit scores down to 620.
- VA Loan + Keys4You – for eligible veterans. VA loans are already 0% down, so your entire 4% Keys4You goes toward closing costs and prepaid items.
- USDA Loan + Keys4You – for rural-eligible properties in Delaware. USDA is 0% down, so again the full 4% applies to closing costs and prepaids.
- Conventional 97 Loan + Keys4You – 3% down conventional with PMI. Keys4You covers the full 3% down plus a portion of closing costs.
The right pairing depends on your credit score, down payment funds, whether you’re a veteran, and whether the property you’re buying is in a USDA-eligible area. That’s the first conversation I have with every Keys4You buyer – figuring out which first mortgage delivers the lowest monthly payment and the smallest cash-to-close once Keys4You is layered in.
Why DSHA Rates May Be Slightly Higher – And When It’s Still Worth It
Honest conversation most lenders do not have with DSHA buyers: the assistance is funded through rate pricing, so the more DPA you take, the higher your first-mortgage rate. That is not a flaw, it is how the program is built – and DSHA publishes the numbers, so you can see exactly what the 4% costs you. Here is the sheet dated September 14, 2026. These are program rates for comparison, not a quote, not an APR and not a rate lock; APR will be higher, and DSHA reprices on its own schedule, so call 302-703-0727 for the current sheet before you decide.
| Product | Assistance | Welcome Home government | Welcome Home conventional | Open Door government | Open Door conventional |
|---|---|---|---|---|---|
| Smart Start | None | 5.625% | 6.125% | 7.000% | 7.375% |
| First State | 3% | 5.875% | 6.375% | 7.625% | 8.000% |
| Keys4You | 4% | 6.125% | 6.500% | 7.750% | 8.125% |
| Take5 | 5% | 6.625% | 7.000% | Not offered | Not offered |
Read your own row. Against Smart Start in the same track, Keys4You costs half a percentage point on a Welcome Home government loan (6.125% against 5.625%) and 0.375 of a point on Welcome Home conventional. The number that surprises people is the track gap: Keys4You under Open Door prices at 7.750% government against 6.125% under Welcome Home – 1.625 percentage points apart for the identical 4% of assistance. If you qualify for Welcome Home, use Welcome Home.
So is the 4% worth the rate? Run it honestly. On a $400,000 Welcome Home government loan, the half-point step from Smart Start to Keys4You adds roughly $128 a month in principal and interest, and Keys4You delivers about $15,700 at closing. That is a break-even around 10 years, not 20-plus. On Welcome Home conventional the 0.375 step adds about $98 a month and breaks even closer to 13 years. Most Delaware buyers sell, refinance or pay off in 7 to 12 years, which puts the break-even inside that range rather than comfortably past it. These are illustrations on a round loan amount, not a quote.
That means the answer depends on your situation rather than being automatic. If you do not have the cash to close, Keys4You is what gets you into the house, and a break-even you may never reach is not a cost you ever pay. If you already have the down payment, or you expect to sell or refinance within a few years, the Smart Start unassisted DSHA first mortgage or a non-DSHA loan is likely to cost less over the period you actually hold it.
Common Mistakes with Keys4You – and How to Avoid Them
After originating DSHA down payment assistance loans for 20+ years, these are the mistakes I see Keys4You buyers (and sometimes other lenders) make most often. Every one of them is avoidable with the right upfront guidance.
- Thinking Keys4You is forgivable. It isn’t. Keys4You is deferred, not forgiven. The full 4% balance must be repaid when you sell, refinance, transfer title, or stop using the home as your primary residence. Plan your long-term finances accordingly – especially if you’re thinking about a cash-out refinance down the road.
- Not planning for refinance payoff. If you refinance the first mortgage to get a lower rate, you have to pay off the Keys4You balance in full at that refinance. On a $400K loan, that’s $15,000+ of cash-to-close at refinance time. Factor this into any refinance decision – sometimes keeping the current loan and its DPA balance is smarter than refinancing to save 0.5%.
- Choosing the wrong DPA tier. Some buyers grab Keys4You when First State (3%) would have been a smaller, cleaner lien – or when Take5 (5%) would have given them more at closing. Match the DPA amount to your actual cash-to-close gap, not just “the biggest number available.”
- Not negotiating seller concessions. Keys4You stacks beautifully with seller-paid closing costs. On a $400K FHA purchase, you can negotiate up to 6% seller concessions ($24,000). Combined with Keys4You’s $15,700, you can be at closing with almost nothing out of pocket – but only if your Realtor asks for the concession in the contract.
- Missing the first-time buyer transfer tax reduction. First-time Delaware buyers using Welcome Home qualify for a state transfer tax reduction worth up to $2,000 on homes priced up to $400,000. I’ve seen title companies miss this on DSHA closings. Make sure your closing attorney applies the first-time buyer reduction before signing.
- Assuming all lenders can originate DSHA. DSHA loans can only be originated through DSHA-approved lenders. If you start a loan with a non-approved lender and later try to switch, you’ll have to restart the application. Verify approval status before you commit.
- Shopping the rate without the DPA. National rate-comparison sites don’t show DSHA rates. A slightly higher DSHA rate with 4% DPA almost always beats a lower non-DSHA rate that leaves you needing $15,000 more at closing. Compare apples to apples – total cash-to-close and 5-year total cost, not just the advertised rate.
Can You Combine Keys4You With Other DSHA DPA Programs?
No. DSHA borrowers may use only one DSHA down payment assistance second mortgage per transaction. You cannot stack Keys4You with First State, Take5, or Diamond in the Rough – you have to pick one. The good news is that Keys4You’s 4% is already a strong standalone DPA, and if you need more help at closing you can layer in tools that DSHA does not prohibit: seller-paid closing cost concessions, gift funds from an eligible family member, lender credits from your first-mortgage interest rate, or – in some cases – a non-DSHA second-layer program like a local New Castle County or Wilmington housing authority grant.
The “which single DSHA DPA should I use?” question is what I help every buyer answer on the intake call. For most repeat buyers under Open Door, Keys4You is the answer because it’s the only 4% option available. For first-time buyers under Welcome Home, it’s a choice between 3% (First State), 4% (Keys4You), or 5% (Take5 or Diamond in the Rough), and the right pick depends on credit score, loan type, property condition, and how much you need at the closing table. Call 302-703-0727 and I’ll run the numbers for your exact scenario.
Who Keys4You Is Not Right For
Keys4You is a great program for most Delaware buyers who need DPA – but it’s not the right pick for every scenario. Here’s when I steer buyers toward a different option.
- First-time buyers who qualify for Take5 and need the maximum help. If you’re under Welcome Home income limits and you need every dollar you can get at closing, the 5% Take5 home loan beats Keys4You by 1% – that’s a real $4,000+ on a $400K purchase.
- Buyers who only need a small amount of help. If your closing math already works out and you only need enough to cover a down payment, the 3% First State Home Loan gives you a smaller second lien to repay later when you sell or refinance. A smaller DPA balance means more equity protected at sale.
- Buyers planning to refinance quickly. Keys4You must be paid off in full at refinance. If you expect to refinance within 2-3 years – for example, because rates are high today and you plan to refinance when they drop – the DPA balance becomes a meaningful chunk of your refinance cash-to-close. In that case, a smaller DPA (or no DPA at all paired with the Smart Start unassisted first mortgage) may be smarter.
- Buyers purchasing fixer-uppers. If the home you want to buy needs repairs that exceed FHA minimum property standards, the Diamond in the Rough FHA 203k is the better program – it gives you the same 5% DPA plus FHA 203(k) Limited renovation financing rolled into your first mortgage. Note that Diamond requires a higher 640 minimum credit score because of the renovation overlay.
- Investment property or second home buyers. Keys4You requires the home to be your primary residence. Delaware second-home or investment property buyers need a different financing structure – ask about Delaware conventional investment loans or DSCR loans.
- Buyers who need a non-occupant co-borrower. DSHA programs generally don’t allow non-occupant co-borrowers. If you need a co-signer who will not live in the home, ask about the Empower down payment assistance program instead. Empower is a non-DSHA option that does allow non-occupant co-borrowers and offers either 3.5% or 5% down payment assistance, which makes it one of the few routes open to a Delaware buyer who needs a parent or relative on the loan without having them move in. Eligibility, the assistance amount and the co-borrower rules are confirmed at pre-approval and depend on credit, income and the property, so call 302-703-0727 and we will check whether it fits before you write an offer.
What Do You Actually Pay at Closing With Keys4You?
This is where the Keys4You conversation gets real. Your total cash-to-close is driven by four components: your down payment, your closing costs, your prepaid items (property tax and insurance escrows), and any earnest money deposit you already put down. Keys4You reduces the first two directly. Here’s how it plays out on a $350,000 Welcome Home FHA purchase in New Castle County.
- Purchase price: $350,000
- FHA down payment (3.5%): $12,250
- Estimated closing costs: ~$9,000
- Estimated prepaids (tax + insurance escrow): ~$4,500
- Total needed at closing: ~$25,750
- Keys4You 4% DPA: ~$13,750
- Seller-paid closing costs (negotiated at 3%): $10,500
- Cash to close after Keys4You + seller concessions: ~$1,500
That’s a buyer walking into a $350,000 Delaware purchase with less than $2,000 at closing, using nothing but DSHA programs and a normal seller concession. This is what’s possible when you combine Keys4You with the right first mortgage and a skilled negotiator on your side of the contract. Call my team and we’ll structure the same math for your exact purchase price and county.
Delaware Transfer Tax: What Keys4You Buyers Need to Know
Delaware Transfer Tax Alert: Delaware charges a 4% real estate transfer tax on every home purchase. On a standard Delaware Association of Realtors (DAR) contract, that 4% is split equally — 2% buyer, 2% seller. But if you’re buying a new-construction home directly from a builder, most builder contracts require the buyer to pay the full 4%. Always read the transfer tax clause before signing. On a $400,000 home, that’s the difference between $8,000 and $16,000 at closing.
First-time Delaware home buyers qualify for a state transfer tax reduction worth 0.5% on up to $400,000 of purchase price – a potential savings of up to $2,000 for first-time buyers using Welcome Home. This benefit does NOT apply to Open Door repeat buyers. If you’re using Keys4You under Welcome Home, make sure your title company and attorney apply the first-time buyer transfer tax reduction at closing – I’ve seen it get missed when the title company isn’t used to DSHA transactions, and it’s real money.
How Do You Apply for the DSHA Keys4You Home Loan?
The application process for Keys4You is the same as applying for any DSHA first mortgage – you apply once, and your DSHA-approved lender structures the first mortgage and the Keys4You second mortgage together in a single transaction. Here’s the step-by-step path from “I’m interested” to “I own the home.”
- Call or schedule a consultation – we review your income, credit, down payment savings, and target price range. I tell you upfront whether Welcome Home or Open Door is the right fit, and which DPA (First State, Keys4You, or one of the 5% options) works for your scenario.
- Apply online or in person – I submit a full loan application through our secure online platform. You provide W-2s, pay stubs, bank statements, and ID. Self-employed? You’ll provide two years of tax returns.
- Get pre-approved – I run your credit, verify your income, and issue a Pre-Approval Letter. This is the letter you give your Delaware Realtor when shopping.
- Complete homebuyer counseling if required – if your credit score is below 660, you’ll need 8 hours of HUD-approved counseling. I’ll give you the list of approved Delaware counselors, and most buyers finish in 1-2 sessions (some online).
- Shop and go under contract – your Realtor negotiates the contract (don’t forget seller-paid closing costs if you need them) and we submit the executed contract to underwriting.
- Underwriting and appraisal – DSHA issues a conditional approval, the home gets appraised, and we clear any remaining conditions.
- Clear to close – the title company prepares the Closing Disclosure. You’ll see both the first mortgage and the Keys4You second mortgage listed.
- Closing day – you sign both sets of documents at the attorney’s office, Keys4You funds your down payment and/or closing costs, and you walk out with the keys.
Quick Answers for Delaware Keys4You Buyers
Short, direct answers to the three questions I hear most often on the first call.
How much money do you get with Keys4You?
Keys4You provides 4% of your final first mortgage loan amount. On a $300,000 home you’d receive approximately $11,700–$11,800. On a $400,000 home that’s typically around $15,000–$16,000. On a $500,000 home you’d receive approximately $19,400. The exact dollar amount depends on your loan type (FHA, VA, USDA, or Conventional) and whether upfront mortgage insurance is financed into the loan.
Is Keys4You forgivable?
No. Keys4You is not forgivable. It is a zero-interest deferred second mortgage with no monthly payment. The full 4% balance is repayable upon sale, refinance, transfer of title, or when the home is no longer your primary residence.
Does Keys4You have monthly payments?
No. There is no monthly payment on the Keys4You 4% down payment assistance. Payment is deferred until the first mortgage is refinanced or paid off, the home is sold, title is transferred, or the property stops being your primary residence.
Can repeat buyers use Keys4You?
Yes. Repeat buyers in Delaware can use Keys4You when paired with the DSHA Open Door first mortgage. Keys4You is the only DSHA DPA at 4% or higher that does not require first-time buyer status, which makes it the largest down payment assistance option available to Delaware repeat buyers.
Ready to Use Keys4You to Buy Your Delaware Home?
Keys4You is the DPA I recommend most often in 2026 because it works for more Delaware buyers than any other 4%+ option – first-time or repeat, New Castle or Sussex, FHA or Conventional. If you’ve been holding off on buying because you don’t have the down payment saved, or you’ve been told you don’t qualify because you’ve owned a home before, it’s time to run the numbers again. Call my team, schedule a free 30-minute consultation, or apply online – and let’s find out exactly which DSHA program gets you into a Delaware home this year.
Watch: DSHA Keys4You Explained
A complete walkthrough of the DSHA Keys4You 4% Down Payment Assistance Program – what it is, who qualifies, how it pairs with both Welcome Home and Open Door, real dollar examples, and how it compares to First State, Take5, and Diamond in the Rough.
Quick version – 58-second short
Prefer the short version? Here’s the 58-second explainer covering the headline facts: 4% DPA, zero-interest deferred, pairs with both Welcome Home and Open Door.
The Delaware DSHA Guide in Print
I wrote Your Guide to Buying Your First Home in Delaware (ISBN 0557349826) as a complete how-to reference for Delaware buyers navigating DSHA programs, credit, mortgages, and closing. It covers the full process from pre-approval through post-closing – including chapters on Delaware Down Payment Assistance Programs and real Delaware closing scenarios. If you’re serious about buying a home in Delaware in the next 6-12 months, the book pairs well with this page. Ask me about a copy when we talk.
Related Delaware DPA and Mortgage Guides
- DSHA Loan Programs in Delaware: Full 2026 Guide – the main DSHA hub covering Welcome Home, Open Door, and all DPA options.
- DSHA Welcome Home loan for first-time buyers in Delaware – the first-time-buyer first mortgage that pairs with Keys4You.
- DSHA Open Door loan for repeat home buyers in Delaware – the first-time and repeat buyer first mortgage (renamed from Home Again in DSHA’s April 2026 Delaware Mortgage Program rebrand) that also pairs with Keys4You.
- DSHA First State Home Loan 3% down payment assistance – the 3% DPA alternative to Keys4You.
- DSHA Take5 5% down payment assistance for first-time buyers – the 5% DPA for first-time buyers only.
- DSHA Diamond in the Rough FHA 203k renovation loan with 5% DPA – for first-time buyers purchasing fixer-uppers (640 minimum credit).
- Delaware Down Payment Assistance Programs (2026 complete guide) – all Delaware DPA options beyond DSHA.
- Delaware First Time Home Buyer Programs and Grants 2026 – the complete first-time buyer pillar page.
- Delaware Mortgage Credit Certificate (MCC) – the MCC was a federal tax credit for Delaware first-time buyers that ended August 15, 2025 (separately from the April 2026 Delaware Mortgage Program rebrand). Many national sites and accountants still reference it as active. Our MCC page explains how the program worked, when it ended, and what DSHA replaced it with.
- Delaware FHA Loans – 3.5% down first mortgage for Keys4You – the most common first mortgage used with Keys4You.
Where Delaware Buyers Use Keys4You Most
I originate Keys4You loans statewide in Delaware, but certain neighborhoods and towns generate more Keys4You applications than others – typically where home prices align well with DSHA’s sales price limits and where Open Door’s higher income limits help more buyers qualify. Here’s where I see the most Keys4You activity.
- Newark, DE – home to my branch office at 248 E Chestnut Hill Rd. Newark first-time and repeat buyers use Keys4You heavily for townhomes in White Chapel, Pike Creek, and Brookside, plus single-family homes in Brookside and Cooper Farm.
- Wilmington, DE – strong Open Door Keys4You activity across Trolley Square, Forty Acres, Highlands, and the revitalizing neighborhoods along Riverside. Targeted-area status in parts of Wilmington also lets repeat buyers use Welcome Home at lower interest rates.
- Middletown, DE – one of Delaware’s fastest-growing areas. Keys4You is heavily used on new-construction townhomes and single-family homes in developments like Estates at St. Anne’s, Back Creek, and the Bayberry communities. Remember the builder transfer tax rule on new construction.
- Bear, DE – strong Keys4You market in the $300K-$425K range. Popular communities: Caravel Farms, Glasgow Pines, and Fox Run.
- Dover, DE – Kent County’s government and healthcare workforce qualifies well under both Welcome Home and Open Door. Keys4You applications common across Rodney Village, Woodbrook, and newer developments off Route 13.
- Smyrna, DE – northern Kent County, bridging NCC commuters and local Kent County buyers. New construction in Bon Ayre and Garrison Lake is a common Keys4You target.
- Milford, DE – southern Kent/northern Sussex. Lower Kent/Sussex income limits mean more buyers qualify for Welcome Home pricing, and Keys4You pairs well with typical $250K-$375K purchase prices.
- Georgetown, DE – Sussex County seat. Affordable pricing plus Open Door’s higher income limits make this a strong Keys4You market for working households.
- Lewes & Rehoboth-adjacent Sussex – higher price points push more buyers toward Open Door Keys4You because Welcome Home income limits are tighter. Inland Lewes and Angola areas are common.
- Seaford, DE – western Sussex. Strong USDA + Keys4You pairing opportunities because much of western Sussex qualifies for USDA 0%-down first mortgages.
Buyers in Newark, Wilmington, Middletown, Bear, Dover, Smyrna, Milford, Georgetown, Lewes, Seaford, and throughout Sussex County use Keys4You as their primary DSHA down payment assistance option. Wherever you’re buying in Delaware, my team originates Keys4You loans statewide from the Newark office. We close in all three counties every month – call 302-703-0727 or schedule a 30-minute appointment to find out how Keys4You works at your purchase price in your specific Delaware town.
About the Author – John Thomas, Delaware’s DSHA Keys4You Expert
John R. Thomas
Branch Manager & Division Vice President of Sales
John Thomas Team with AnnieMac Home Mortgage — Newark, Delaware
John Thomas has been originating Delaware mortgages for more than 20 years and has personally helped over 3,000 Delaware home buyers close on their homes across New Castle, Kent, and Sussex counties. As a DSHA-approved lender since the agency’s earliest consumer program years, John has originated loans under every iteration of the Delaware Mortgage Program — from the original Single Mortgage Revenue Bond and SMAL programs, through Preferred Plus and Kiss Your Landlord Goodbye, into the current Welcome Home, Open Door, First State, Keys4You, Take5, and Diamond in the Rough. When DSHA launched the Delaware Mortgage Program in April 2026 — renaming Home Again to Open Door, branding the 4% DPA as Keys4You and opening it to both Welcome Home and Open Door, and launching the new Take5 5% DPA — John’s team was among the first Delaware lenders originating loans under the new product structure.
John holds a Bachelor of Science in Physics Education from the University of Delaware and a Master of Science in Curriculum and Instruction from Delaware State University, and is a Certified Mortgage Planner (CMP). Licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA). NMLS #38783. The license list is a credential, not a service-area claim; day-to-day origination is Delaware and Maryland.
John is the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826), runs the Delaware First Time Home Buyer Seminar series in Newark, Dover, and Wilmington, and publishes Delaware mortgage education videos on the @Delawaremortgage YouTube channel. His team specializes in pairing DSHA DPA programs with FHA, VA, USDA, and Conventional first mortgages — and in structuring seller-concession scenarios that minimize cash-to-close for Delaware buyers. If you have a question about whether Keys4You is the right fit for your purchase, John’s team answers it for free, with no pressure and no obligation.
John R. Thomas, NMLS #38783
248 E Chestnut Hill Rd, Newark, DE 19713
Email: team@johnthomasteam.com
Phone: 302-703-0727 | Schedule Appointment | YouTube Channel | See John Thomas Team on Google
YouTube · Facebook · Instagram · TikTok · X / Twitter · LinkedIn
FAQ – DSHA Keys4You Home Loan Delaware
What is the DSHA Keys4You Home Loan?
The DSHA Keys4You Home Loan is a zero-interest deferred second mortgage equal to 4% of your first mortgage loan amount, offered by the Delaware State Housing Authority under the Delaware Mortgage Program. It is used for down payment and closing cost assistance. There is no monthly payment – the loan is repayable only when you sell, refinance, transfer title, or the home is no longer your primary residence. Keys4You was named and launched in DSHA’s April 2026 Delaware Mortgage Program rebrand. The same single rebrand event branded DSHA’s prior 4% DPA (which had been reintroduced in 2025 as a Home Again-only option with no official product name) as Keys4You and opened it to buyers under both Welcome Home AND Open Door.
How much down payment assistance does Keys4You provide?
Keys4You provides 4% of your final first mortgage loan amount. On a $300,000 FHA loan you would receive approximately $11,783. On a $400,000 FHA loan you would receive approximately $15,710. On a $500,000 Conventional loan you would receive approximately $19,400. The assistance can be used for down payment, closing costs, or a combination of both, depending on your specific transaction.
Is Keys4You only for first-time home buyers?
No. Keys4You pairs with both the DSHA Welcome Home program (first-time buyers only) and the DSHA Open Door program (first-time and repeat buyers). That makes Keys4You the largest DPA available to Delaware repeat buyers – the 5% Take5 and Diamond in the Rough programs are restricted to Welcome Home only. If you have owned a home in the last three years, Keys4You is typically your best DSHA DPA option.
Can I use Keys4You with the DSHA Open Door program?
Yes. Keys4You is one of only two DPA programs (along with the 3% First State Home Loan) that pairs with Open Door. Open Door (renamed from Home Again in DSHA’s April 2026 Delaware Mortgage Program rebrand) has higher income limits than Welcome Home and does not require first-time buyer status, so it is often the right track for Delaware repeat buyers or dual-income households. You get the flexibility of Open Door plus the highest Open-Door-eligible DPA at 4%.
How is Keys4You different from First State, Take5, and Diamond in the Rough?
First State is 3% DPA and pairs with both Welcome Home and Open Door. Keys4You is 4% DPA and also pairs with both tracks. Take5 is 5% DPA but only pairs with Welcome Home (first-time buyers only). Diamond in the Rough is 5% DPA combined with FHA 203(k) Limited renovation financing for first-time buyers buying fixer-uppers, and it requires a higher 640 minimum credit score because of the renovation overlay. Keys4You sits in the sweet spot – more DPA than First State, more flexibility than Take5 or Diamond.
Do I have to pay back the Keys4You loan?
You only repay Keys4You if one of four things happens: you sell the home, you refinance the first mortgage, you transfer the title, or the home stops being your primary residence. The loan is recorded as a second mortgage lien but accrues no interest and requires no monthly payment. If you stay in the home and never refinance, the Keys4You balance simply sits there until one of those triggering events occurs.
What credit score do I need for Keys4You in Delaware?
Keys4You requires a minimum credit score of 620 for all borrowers on the loan. If your credit score is between 620 and 659, you will be required to complete 8 hours of HUD-approved homebuyer counseling before closing. Manually underwritten loans generally require a minimum 660 credit score. If your score is currently below 620, ask about the John Thomas Team’s Get Mortgage Ready program to build your score and qualify.
What are the income limits for Keys4You in Delaware?
Income limits depend on which first mortgage you pair Keys4You with and which Delaware county you are buying in. Under Welcome Home for non-targeted areas, the limits effective for reservations on or after June 8, 2026 are $122,700 (1-2 person) / $141,105 (3+) in New Castle County and $111,400 / $128,110 in Kent and Sussex counties. Under Open Door, the limits are $147,240 / $184,050 in New Castle County and $133,680 / $167,100 in Kent and Sussex. Welcome Home targeted-area limits are higher again, at $147,240 / $171,780 in New Castle County and $133,680 / $155,960 in Kent and Sussex across both programs. Call 302-703-0727 for current limits for your household size and county.
Can I use Keys4You with an FHA, VA, USDA, or Conventional loan?
Yes. Keys4You pairs with all four major loan types under DSHA’s Delaware Mortgage Program. FHA is the most common pairing because the 3.5% down payment requirement matches well with 4% DPA. VA and USDA loans are 0% down, so the entire 4% Keys4You goes toward closing costs and prepaid items. Conventional 97 loans at 3% down also work well, leaving leftover DPA for closing costs.
Do I need to take a homebuyer education class to use Keys4You?
Homebuyer education is required if your credit score is below 660. The requirement is 8 hours of HUD-approved housing counseling, which many Delaware buyers complete online in one or two sessions. If your credit score is 660 or higher, counseling is not required. Your lender will provide the list of approved Delaware housing counselors and confirm whether counseling is needed before closing.
What properties are eligible for Keys4You in Delaware?
Keys4You can be used for single-family homes, townhomes, approved condos, and certain planned unit developments in Delaware. The property must be your primary residence – Keys4You cannot be used for investment properties or second homes. DSHA has purchase price limits that vary by county and program (non-targeted: $659,385 NCC, $566,354 K&S; targeted areas $805,916 NCC, $692,211 K&S). Manufactured homes on permanent foundations may qualify with additional underwriting guidelines (660+ credit, FHA only, double-wide or larger).
How do I apply for the DSHA Keys4You Home Loan Delaware?
Apply through a DSHA-approved lender such as the John Thomas Team with AnnieMac Home Mortgage. Call 302-703-0727, schedule a free 30-minute appointment, or apply online. We review your income, credit, county, and purchase goal in the consultation, then submit a single application that structures the first mortgage (Welcome Home or Open Door) and the Keys4You second mortgage together. You close both loans at the same settlement.
Last Updated: September 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
DSHA income limits and purchase price limits effective for reservations on or after June 8, 2026, verified against the Delaware State Housing Authority on September 13, 2026. Program rates from the DSHA rate sheet dated September 14, 2026 – not a quote, not an APR and not a rate lock; call 302-703-0727 for the current sheet.
John R. Thomas, NMLS #38783 | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
