Delaware FHA Loan Limits 2026: New Castle, Kent & Sussex County Maximums


CURRENT AS OF SEPTEMBER 2026
Delaware FHA Loan Limits 2026 Quick Answer: For a one-unit home, the 2026 FHA loan limit is $630,200 in New Castle County and $541,287 in Kent and Sussex Counties. Multi-unit limits run higher: in New Castle County $806,750 for a duplex, $975,200 for a triplex and $1,211,950 for a fourplex; in Kent and Sussex $693,050, $837,700 and $1,041,125. Kent and Sussex sit at the national FHA floor, which is 65% of the $832,750 conforming loan limit, while New Castle County qualifies for a higher limit because Wilmington-area home prices exceed the threshold. These limits apply to FHA case numbers assigned on or after January 1, 2026. Call John Thomas, NMLS #38783, at 302-703-0727. Current as of September 2026.
The FHA loan limit is a ceiling on the loan, not a ceiling on the price of the house. I’m John Thomas, NMLS #38783, Branch Manager and Division Vice President of Sales with the John Thomas Team with AnnieMac Home Mortgage in Newark, Delaware, and that distinction is the single thing buyers get wrong most often on this page. A buyer in New Castle County can absolutely purchase above $630,200 with an FHA loan – they just have to bring the difference to closing, because the financed amount is what the limit caps. In 20+ years of Delaware FHA files the conversation I have most often is with a buyer who walked away from a house they could have bought, because they read the limit as a price cap. This page gives you the exact 2026 figures for all three Delaware counties and all four unit counts, then explains what to do when your purchase price runs past them.
Find Out What You Can Actually Borrow in Delaware
The county limit is one number. What you qualify for depends on your credit, income, debts and the property. I’ll run both and tell you where you actually stand – no obligation.
Table of Contents
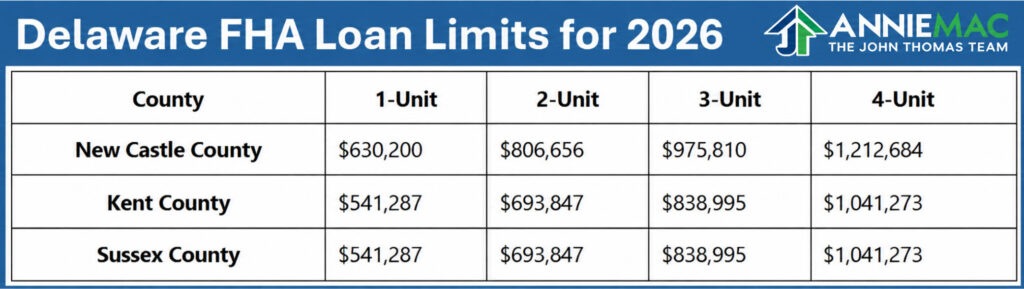
2026 Delaware FHA Loan Limits by County (1 to 4 Units)
FHA sets its limits by county and by the number of units in the property. Delaware has two tiers: New Castle County sits above the national floor because Wilmington-area home prices are high enough to qualify for an increase, while Kent and Sussex Counties sit exactly at the floor. Here is the complete 2026 table.
| County | 1-Unit | 2-Unit | 3-Unit | 4-Unit |
|---|---|---|---|---|
| New Castle County | $630,200 | $806,750 | $975,200 | $1,211,950 |
| Kent County | $541,287 | $693,050 | $837,700 | $1,041,125 |
| Sussex County | $541,287 | $693,050 | $837,700 | $1,041,125 |
One detail that catches Delaware buyers out. The limit applies to your final loan amount, and on an FHA loan the 1.75% upfront mortgage insurance premium is normally financed on top of the base loan. The base loan has to fit under the county limit; the financed upfront premium is permitted above it. So a New Castle County buyer at the $630,200 base limit ends up with a total financed balance closer to $641,229 once the upfront premium is added, and that is allowed.
How FHA Sets the Loan Limits
FHA limits are not set independently – they are calculated as a percentage of the national conforming loan limit set each year by the Federal Housing Finance Agency. For 2026 the one-unit conforming limit is $832,750, and that single number drives everything else:
- The floor is 65% of the conforming limit – $541,287 for 2026. This is the minimum FHA limit anywhere in the country, and it is what Kent and Sussex Counties get.
- Higher-cost counties get more, based on 115% of the area median home price, capped at the national ceiling. New Castle County’s $630,200 comes from that calculation.
- Limits are recalculated annually as home prices move, and they have risen every year recently. A limit that blocked a purchase last year may not block it this year.
If you want to see the same figures at the source, or check a county outside Delaware, the HUD FHA Mortgage Limits lookup is the authoritative tool. It is also worth knowing the Delaware conforming loan limits for 2026, because that is the number that decides whether a conventional loan is an alternative when FHA runs out of room.
What Happens If Your Purchase Price Exceeds the FHA Limit?
This is the question the limits table actually raises, and it is where most buyers stop reading and assume the answer is no. It usually is not. You have three workable paths, and the right one depends on how far over you are.
- Bring a larger down payment. The limit caps the loan, not the price. On a $680,000 New Castle County purchase, financing the $630,200 maximum means bringing roughly $49,800 plus closing costs instead of the 3.5% minimum. If you have the cash, FHA still works and you keep FHA’s flexible credit standards.
- Switch to a conventional loan. With a conforming limit of $832,750, conventional financing has substantially more room than FHA in every Delaware county. If your credit is strong, conventional is often the better answer anyway, because the mortgage insurance is cancellable.
- Use a jumbo loan. Above the conforming limit, Delaware jumbo financing takes over. Credit and reserve requirements are tighter, but the ceiling is far higher.
When FHA is still worth it even though you are over the limit: if your credit score sits below roughly 680, the pricing advantage FHA gives you can outweigh the larger down payment. If your score is well above 740 and you have 5% or more to put down, conventional almost always wins on total cost. That comparison takes about ten minutes to run properly, and it is worth running before you write the offer rather than after.
Delaware FHA Loan Limits by City
FHA publishes limits by county, but buyers search by city. Here is how the 2026 county limits map onto the places Delaware buyers actually shop.
| County | 1-Unit Limit | Cities and towns covered |
|---|---|---|
| New Castle | $630,200 | Wilmington, Newark, New Castle, Bear, Middletown, Hockessin, Claymont, Pike Creek |
| Kent | $541,287 | Dover, Smyrna, Camden, Harrington, Felton |
| Sussex | $541,287 | Milford, Lewes, Rehoboth Beach, Georgetown, Millsboro, Seaford |
Two local notes worth having before you shop. First, the beach markets: an FHA loan in Lewes or Rehoboth Beach must be for a primary residence, so it cannot be used for a vacation or second home no matter how the limit works out – and at Sussex’s $541,287 cap, a fair share of beach-area inventory sits above it. Second, Smyrna straddles the Kent and New Castle county line. The FHA limit follows the county the property is legally in, not the mailing address, and I have seen that surprise a buyer mid-contract.
How Multi-Unit FHA Limits Work in Delaware
FHA finances 2-to-4-unit properties at the same 3.5% minimum down payment as a single-family home, which makes it one of the cheapest entry points into owning rental property in Delaware. The rules are straightforward:
- You must live in one of the units as your primary residence. This is not optional and it is verified.
- The loan must fit under the county limit for that unit count – the figures in the table above.
- The property must meet FHA minimum property standards, and every unit is inspected, not just yours.
- Rental income from the other units may help you qualify, subject to FHA’s documentation rules and, on 3-4 unit properties, a self-sufficiency test.
In practice that means duplexes in Wilmington, triplexes in Newark or Bear, and four-unit buildings in Dover or Milford are all reachable on 3.5% down, provided you occupy a unit. The 3-4 unit self-sufficiency test is the step that catches people: FHA requires the property’s rental income to cover the mortgage payment, and a building that pencils out on paper can fail it. Send me the address and rent roll before you write the offer and I will run it.
FHA Requirements You Still Have to Meet in 2026
The loan limit is a ceiling, not an approval. Meeting it does not qualify you, and the rest of the FHA file still has to stand up:
- Primary residence only. FHA does not finance investment properties or second homes.
- Minimum down payment of 3.5% with a credit score of 580 or higher, or 10% with a score between 500 and 579. Individual lenders may set higher minimums than FHA’s floor.
- Debt-to-income within FHA guidelines. The automated underwriting benchmark is generally around 46.9% housing and 56.9% total debt, and files above that need compensating factors such as reserves or a documented history of paying a similar housing payment.
- FHA mortgage insurance – an upfront premium, usually financed, plus an annual premium paid monthly. On most FHA loans the annual premium stays for the life of the loan.
- An FHA appraisal by an FHA-approved appraiser. This is a valuation plus a minimum-property-standards check, and it is not a home inspection – you should still get one of those.
The full requirement set, including gift funds, seller concessions and credit-event waiting periods, is on the Delaware FHA loans page.
FHA vs Conventional When You Are Near the Limit
| Feature | FHA Loan | Conventional Loan |
|---|---|---|
| 2026 Delaware limit (1 unit) | $630,200 New Castle / $541,287 Kent and Sussex | $832,750 statewide |
| Minimum down payment | 3.5% at 580+ credit; 10% at 500-579 | 3% for eligible first-time buyers; 5% typical |
| Credit flexibility | More forgiving of past credit events | Stricter, and pricing is more score-sensitive |
| Mortgage insurance | Upfront plus annual; usually for the life of the loan | Cancellable once you reach sufficient equity |
| Best fit | Lower credit scores, thinner savings, past credit events | Strong credit, 5%+ down, purchase price above the FHA county limit |
The honest summary: if your purchase price is pressing against the FHA county limit, that is usually a signal to price conventional alongside it rather than assuming FHA is the answer. Buyers shopping near the limit tend to have the income to support the payment, and often the credit to get conventional pricing – in which case cancellable mortgage insurance is worth real money over the life of the loan.
Pairing an FHA Loan With Delaware Down Payment Assistance
FHA is the first mortgage most often used underneath Delaware State Housing Authority down payment assistance, and the two limit systems are separate – which trips people up. Your loan has to fit under the FHA county limit, and your purchase price has to fit under the DSHA purchase price limit, which for reservations on or after June 8, 2026 is $659,385 in New Castle County and $566,354 in Kent and Sussex.
Notice that the DSHA purchase price limit sits above the FHA loan limit in every county. That is not a contradiction – one caps the price, the other caps the borrowing – but it does mean a DSHA-eligible purchase can still exceed what FHA will finance, and the FHA limit becomes the binding constraint first. If you are using assistance, start with DSHA Welcome Home for first-time buyers, or compare the assistance tiers on the Delaware down payment assistance page. Buyers who already have their down payment saved should look at DSHA Smart Start, the unassisted option that carries the lowest DSHA rate.
Ready to Find Out What You Qualify For?
Loan limits are the easy part. What you can actually borrow comes down to credit, income, debts and the property – and if your price is near the county cap, it is worth pricing FHA and conventional side by side before you write an offer. I’ll run both and give you the numbers.
Related Delaware FHA and Loan Limit Guides
- Delaware FHA Loans – the full program guide: credit, down payment, mortgage insurance, gift funds and seller concessions.
- Delaware Conforming Loan Limits 2026 – the $832,750 conventional limit that sets the FHA floor and the jumbo threshold.
- Delaware Conventional Loans – the alternative when your price runs past the FHA county cap.
- Delaware Jumbo Mortgages – financing above the conforming limit.
- Delaware FHA 203k Rehab Loans – purchase plus renovation in one loan, capped by the same county limit.
- FHA One-Time Close Construction Loan – building new on FHA terms.
- Delaware FHA Manufactured Home Loans – how the county limits apply to manufactured housing.
- Delaware First Time Home Buyers Guide – the pillar resource for buying your first home in Delaware.
- Delaware VA Loans and USDA Rural Home Loans – zero-down alternatives for eligible Delaware buyers.
About the Author – John Thomas, Delaware FHA Lender
John Thomas has spent over 20 years originating Delaware FHA loans and has helped more than 3,000 buyers across New Castle, Kent and Sussex Counties. The FHA-limit conversation he has most often is with a buyer who ruled out a house because the price was above the county cap – the limit caps the loan, not the price, and bringing the difference to closing is frequently the cheaper path than switching programs.
John is the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826) and runs a monthly Delaware First Time Home Buyer Seminar. He holds a Bachelor of Science in Physics Education from the University of Delaware and a Master of Science in Curriculum and Instruction from Delaware State University, and is a Certified Mortgage Planner (CMP).
Licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA). NMLS #38783. The license list is a credential, not a service-area claim; day-to-day origination is Delaware and Maryland.
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com | NMLS #38783
Schedule Appointment | About John Thomas | See John Thomas Team on Google for reviews, directions, and local office information.
YouTube · Facebook · Instagram · TikTok · X / Twitter · LinkedIn
Delaware FHA Loan Limits FAQ
How much is the FHA loan limit in New Castle County for 2026?
For a one-unit home in New Castle County, the 2026 FHA loan limit is $630,200. Multi-unit limits are higher: $806,750 for a 2-unit property, $975,200 for a 3-unit, and $1,211,950 for a 4-unit. New Castle County sits above the national FHA floor because Wilmington-area home prices are high enough to qualify for an increase. These limits apply to FHA case numbers assigned on or after January 1, 2026.
What are the FHA loan limits for Kent and Sussex Counties in 2026?
Kent County and Sussex County share the same 2026 FHA loan limits: $541,287 for a one-unit home, $693,050 for a 2-unit, $837,700 for a 3-unit, and $1,041,125 for a 4-unit. Both counties sit at the national FHA floor, which is 65 percent of the $832,750 conforming loan limit. That means Dover, Smyrna, Milford, Lewes, Rehoboth Beach, Georgetown and Seaford all use the same cap.
Can I buy a house that costs more than the FHA loan limit in Delaware?
Yes. The FHA limit caps the loan amount, not the purchase price. If you are buying at $680,000 in New Castle County, you can finance the $630,200 maximum and bring the difference to closing on top of your down payment. Whether that is the right move depends on how far over you are and what your credit looks like: buyers with scores below roughly 680 often still come out ahead on FHA, while buyers with strong credit and 5 percent or more down usually do better on a conventional loan, where the 2026 Delaware limit is $832,750.
Does the FHA loan limit include the upfront mortgage insurance premium?
No. The 1.75 percent upfront mortgage insurance premium may be financed on top of the county limit. Your base loan amount has to fit under the limit, and the financed upfront premium is permitted above it. A New Castle County buyer borrowing the full $630,200 base amount ends up with a total financed balance closer to $641,229 once the upfront premium is added, and that is allowed.
Can I use an FHA loan to buy a duplex or four-unit property in Delaware?
Yes, provided you live in one of the units as your primary residence and the loan fits under the county limit for that unit count. FHA finances 2-to-4-unit properties at the same 3.5 percent minimum down payment as a single-family home, which makes it one of the least expensive ways into Delaware rental property. On 3-unit and 4-unit properties FHA applies a self-sufficiency test requiring the property’s rental income to cover the mortgage payment, and that test is the step that most often disqualifies an otherwise workable building.
Do Sussex County FHA limits cover Lewes and Rehoboth Beach?
Yes. Lewes, Rehoboth Beach, Milford, Georgetown, Millsboro and Seaford all fall under the Sussex County limits of $541,287 for one unit. One caution for the beach markets: an FHA loan must be for a primary residence, so it cannot be used for a vacation home or second home regardless of the limit, and a meaningful share of beach-area inventory prices above the Sussex cap.
When do the 2026 FHA loan limits take effect?
They apply to FHA case numbers assigned on or after January 1, 2026. The case number assignment date is what governs, not your contract date or your closing date, so a purchase that straddles the year end may fall under either year’s limits depending on when the case number was pulled. If you are close to a limit and close to a year boundary, ask your loan officer to confirm the case number date.
What is the difference between the FHA loan limit and the DSHA purchase price limit?
They cap different things. The FHA loan limit caps how much you can borrow: $630,200 in New Castle County and $541,287 in Kent and Sussex for one unit. The DSHA purchase price limit caps what the home can sell for if you are using Delaware State Housing Authority assistance: $659,385 in New Castle County and $566,354 in Kent and Sussex for reservations on or after June 8, 2026. Because the DSHA price limit sits above the FHA loan limit in every county, the FHA limit is usually the constraint you hit first.
Do FHA loan limits affect my credit score or debt-to-income requirements?
No. The limits cap the loan size only. You still need to meet FHA’s credit, income and debt requirements: a 580 minimum credit score for 3.5 percent down or 500 to 579 with 10 percent down, debt-to-income within FHA guidelines, documented income and assets, and an appraisal by an FHA-approved appraiser. Individual lenders may also apply their own minimums above FHA’s floor.
How do I find out what I can actually borrow in Delaware?
Call John Thomas at 302-703-0727 or apply online at applywithjohnthomasteam.com. The county limit is a ceiling, but your actual borrowing capacity depends on your credit, income, debts and the property type. The initial credit check for pre-qualification is a soft pull with no score impact, and there is no application fee. If your target price is near the county cap, ask to see FHA and conventional priced side by side before you write an offer.

Last Updated: September 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
2026 FHA loan limits per HUD, effective for FHA case numbers assigned on or after January 1, 2026; verified against the HUD FHA Mortgage Limits List (FHA Forward, CY2026, DE, last revised 01/01/2026) on September 14, 2026. The 2026 one-unit conforming loan limit of $832,750 is per FHFA. DSHA purchase price limits are effective for reservations on or after June 8, 2026. Figures are program maximums, not a quote, not an APR and not a rate lock – call 302-703-0727 to confirm current limits before you write an offer.
John R. Thomas, NMLS #38783 | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
Copyright (c) 2026 John R. Thomas, All Rights Reserved. Equal Housing Lender.