NextKey Down Payment Assistance Program in Delaware
NEXTKEY DOWN PAYMENT ASSISTANCE – QUICK ANSWER
The NextKey Down Payment Assistance Program is FHA down payment help for Delaware home buyers through the John Thomas Team: a second mortgage of 3.5% or 5% of the price, with forgivable and repayable options, no income limits, no first-time buyer rule and a 600 minimum credit score, subject to underwriting. Current as of October 2026.
You can afford the monthly payment, but saving the 3.5% FHA down payment on top of rent feels like it will take years. That is the exact problem NextKey is built for. I am John Thomas, NMLS #38783, and my goal on this page is to show you how much NextKey can cover, how the forgivable and repayable options work, who qualifies, and when another program is the better deal. If you want to see every Delaware option side by side first, start with our guide to Delaware down payment assistance programs, then come back here to see where NextKey fits.
See How Much NextKey Could Cover for You
A short conversation tells you whether you qualify, which option fits, and what your cash to close would look like. No application fee, and a soft-pull pre-qualification to start.
Table of Contents
What Is the NextKey Down Payment Assistance Program?
NextKey is a down payment assistance second mortgage paired with an FHA fixed-rate first mortgage for Delaware buyers. It provides 3.5% or 5% of the lower of the price or appraised value, has no income limits, and is open to repeat buyers, as of October 2026. Eligibility depends on credit, income and full underwriting.
Put simply, NextKey is two loans that close together. The first mortgage is a regular FHA loan. The second mortgage is the assistance, and it covers the 3.5% minimum down payment that FHA requires (the HUD Handbook 4000.1 sets that minimum). With the 5% option, the extra amount can go toward your closing costs.
NextKey has more than one option behind it. When you apply, we match your file to the option that fits your credit, your property and your goals, so you only have to learn one program. Before you sign, we walk you through your second mortgage note line by line so you know exactly how your assistance works.
| NextKey at a glance | What it means for you |
|---|---|
| Assistance amount | 3.5% or 5% of the lower of the purchase price or appraised value |
| How it is paid | A second mortgage: forgivable (0%, no monthly payment) or repayable (10-year fixed, monthly payment) |
| First mortgage | FHA fixed-rate purchase loan |
| Minimum credit score | 600 (some options and property types need a higher score) |
| Income limits | None on any NextKey option |
| First-time buyer required? | No |
| Your own money required | No minimum contribution on many options; closing costs still apply |
| Occupancy | Your primary residence only |
| Where | Anywhere in Delaware: New Castle, Kent and Sussex Counties, from Wilmington and Newark to Dover and Georgetown |
Program terms as of October 2026. Terms can change, and every loan is subject to credit approval, property eligibility and full underwriting.
How Much Down Payment Assistance Can You Get with NextKey?
NextKey provides 3.5% or 5% of the lower of the purchase price or the appraised value, as of October 2026. On a $300,000 home, that is $10,500 or $15,000. The 3.5% amount covers the FHA minimum down payment; the 5% amount can also help with closing costs. Final amounts follow the appraisal and underwriting.
Let’s say you are buying a $300,000 home and it appraises at the price. Here is a hypothetical look at what each option covers at three price points. These are simplified illustrations, not quotes: FHA upfront mortgage insurance, prepaid items and your other closing costs are not shown.
| Purchase price (hypothetical) | FHA minimum down payment (3.5%) | NextKey 3.5% | NextKey 5% | Left over for closing costs with 5% |
|---|---|---|---|---|
| $250,000 | $8,750 | $8,750 | $12,500 | $3,750 |
| $300,000 | $10,500 | $10,500 | $15,000 | $4,500 |
| $350,000 | $12,250 | $12,250 | $17,500 | $5,250 |
What does that mean for your cash to close? Cash to close = down payment + closing costs + prepaid items – credits. NextKey takes care of the down payment line and, with the 5% option, part of the closing costs. Seller-paid closing costs and gift funds can cover more of what is left. Our guide to seller-paid closing costs shows how that part works, and FHA’s own limits on seller contributions are in the HUD Handbook 4000.1.
One more thing to plan for: you cannot take cash home from the assistance. If the amount is more than the down payment and closing costs need, the extra stays with the loan. The only money a buyer typically gets back at closing is a refund of a documented earnest money deposit or costs already paid out of pocket.
Is NextKey Assistance Forgivable or Repayable?
NextKey offers both. The forgivable option is a 0% second mortgage with no monthly payment that can be forgiven after 36 on-time payments on the first mortgage, under conditions set in the note. The repayable option is a 10-year fixed-rate second with a monthly payment. Selling or refinancing first means repaying the balance, as of October 2026.
| Feature | Forgivable option | Repayable option |
|---|---|---|
| Amount | 3.5%, and 5% on some options | 3.5% or 5% |
| Interest rate | 0% | Fixed rate, set at lock and higher than the first mortgage rate |
| Monthly payment | None | Yes, for 10 years, and it counts in your debt-to-income ratio |
| How it ends | Forgiven after 36 on-time payments on the first mortgage; the exact conditions are in your second mortgage note (see below) | Paid off over 10 years |
| If you sell or refinance early | Due in full if the forgiveness conditions are not yet met | The remaining balance is due |
| Usually fits | Buyers who plan to stay at least three years and want the lowest monthly payment | Buyers who want the 5% amount, or whose file fits a repayable option better |
So what’s the difference in real life? Here is a hypothetical: two buyers each get $10,500. The first takes the forgivable option, makes every first mortgage payment on time for three years, and the second mortgage can be forgiven. The second buyer takes the repayable option and has a small extra monthly payment for ten years, but keeps the option of the 5% amount when cash for closing costs is tight.
I need you to understand the forgiveness conditions before you choose. On some forgivable options, one late payment on the first mortgage restarts the 36-payment count. On some, you request the forgiveness once you qualify and pay a small fee to record the lien release. And on every forgivable option, the balance is due if you sell, refinance or transfer the home before the conditions are met. Your second mortgage note spells out the exact terms, and we go over them with you line by line.
Who Qualifies for NextKey in Delaware?
Delaware buyers generally qualify for NextKey with a 600 or higher credit score, an FHA-approvable income and debt profile, and a primary-residence purchase, as of October 2026. There is no income limit and no first-time buyer rule. Some options and property types need a higher score, and underwriting makes the final decision.
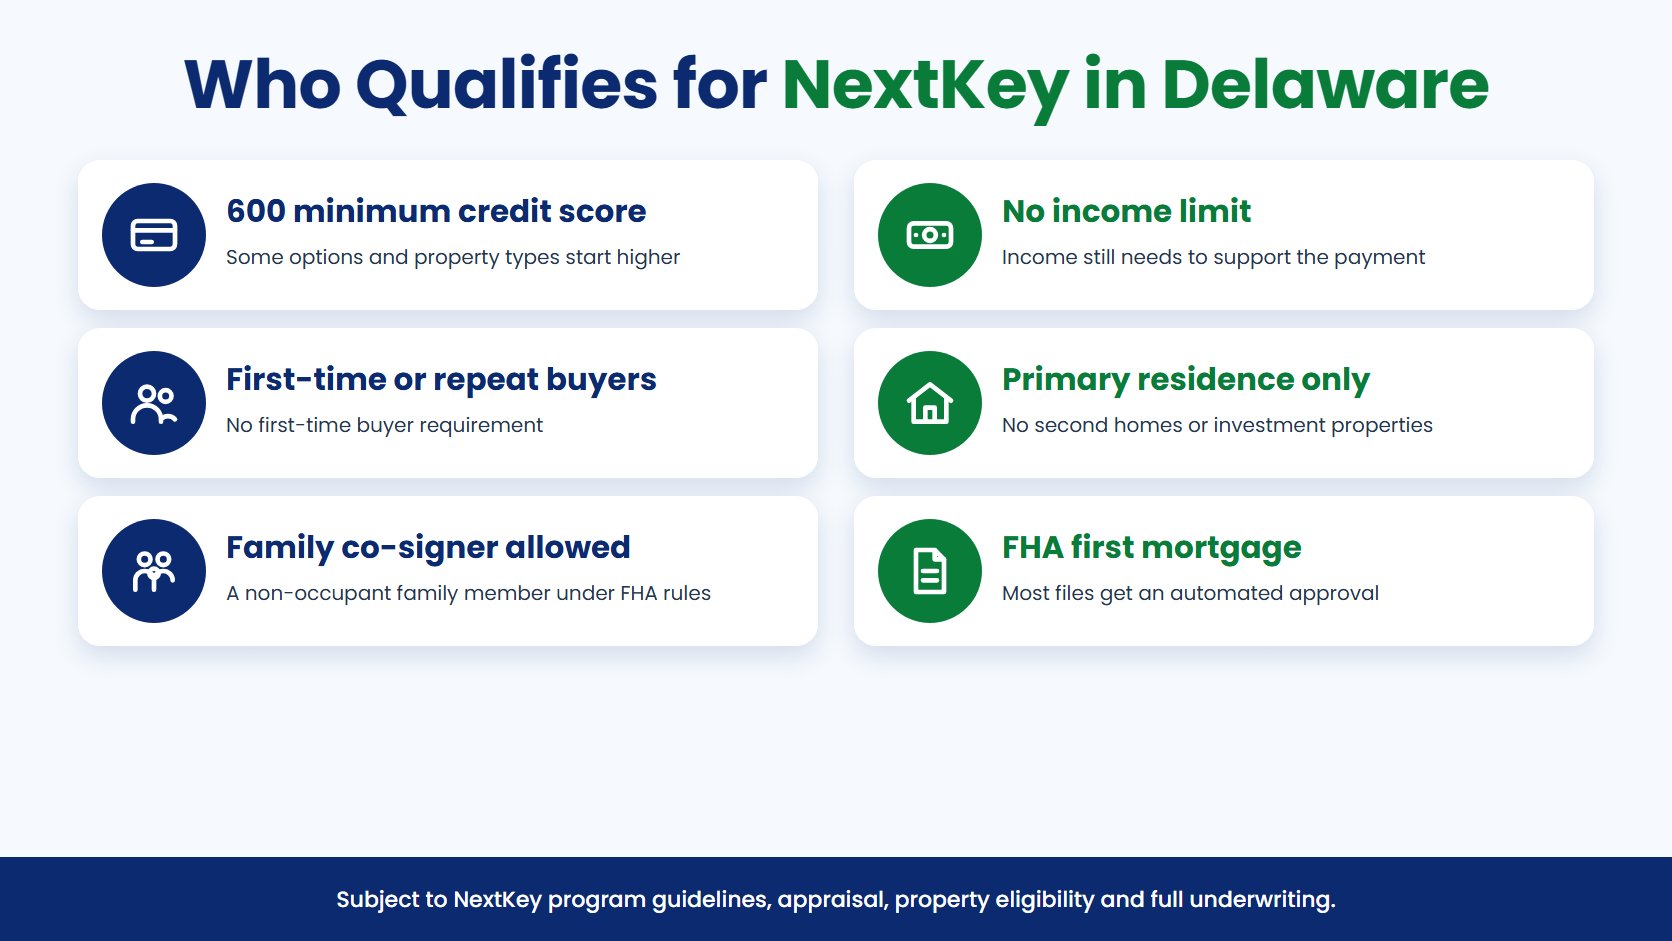
- Credit score: 600 minimum. Buyers with scores below 640 may need to complete a homebuyer education course before closing, and some options and property types start higher.
- Income: no income limit on any NextKey option. You still need stable income that supports the payment, measured by your debt-to-income ratio. On most options, the debt-to-income limit is whatever FHA’s automated underwriting approves, with no extra cap added on top.
- Buyer history: first-time and repeat buyers both qualify. Owning another home is allowed in some cases with a written explanation of the move.
- Occupancy: the home must be your primary residence. Second homes and investment properties are not eligible.
- Co-borrowers: a family member who will not live in the home can co-sign under FHA rules.
- Residency: U.S. citizens and lawful permanent residents. Other residency situations follow current FHA rules.
- Underwriting: most files get an automated approval. Some options also allow a manually underwritten file.
A 600 score only means you meet the minimum. It doesn’t mean you’re approved. Credit score is one factor; your income, your debts, your payment history and the property all count too. If your score sits just under the line, our explanation of the five factors of credit scoring shows which parts of your report move fastest. One small step you can take this week: pull your credit reports and check them for errors.
What Homes Can You Buy with NextKey?
NextKey can be used to buy a single-family home, townhouse, FHA-eligible condo, home in a planned unit development, a two-unit home you live in, or a multi-section manufactured home on a permanent foundation, as of October 2026. Single-wide manufactured homes, investment properties and second homes are not eligible.
- Single-family homes, attached or detached, and townhouses.
- Condos in an FHA-eligible project. Our Delaware condo loan guide explains how project approval works.
- Homes in a planned unit development (PUD).
- Two-unit homes, when you live in one of the units.
- Multi-section (double-wide or larger) manufactured homes on a permanent foundation and titled as real estate. See our FHA manufactured home loan guide for the foundation and title rules.
The home also has to meet FHA’s property standards at appraisal. If the appraiser calls for repairs, they are usually completed before closing, so build that into your timeline when you look at older homes.
NextKey vs. DSHA Down Payment Assistance
Many Delaware buyers qualify for both NextKey and the Delaware State Housing Authority (DSHA) programs, and the right one depends on your income, your credit and whether you have owned a home before. DSHA assistance comes from the state housing agency and has income caps; NextKey has none. The table below compares the two. DSHA figures are from the DSHA Delaware Mortgage Program; DSHA rules and limits change, so we confirm them on your file.
| Feature | NextKey | DSHA down payment assistance |
|---|---|---|
| Assistance | 3.5% or 5% of the price or appraised value | 3%, 4% or 5% depending on the program (First State, Keys4You, Take5) |
| First mortgage | FHA fixed-rate | A DSHA first mortgage (Welcome Home or Open Door) through a DSHA-approved lender |
| Minimum credit score | 600 | 620 (housing counseling required at 659 or below) |
| Income limits | None | Yes, by county and household size (table below) |
| Purchase price limits | No program price limit; the FHA loan limit applies | Yes, DSHA price limits by county |
| First-time buyer rule | No | Welcome Home: yes (waived in targeted areas). Open Door: no |
| How the assistance is repaid | Forgivable after 36 on-time payments, or repayable over 10 years | 0% with no monthly payment, repaid when you sell, refinance, transfer title or move out |
| Loan types | FHA | FHA, VA, USDA and conventional through DSHA |
Here are the DSHA income limits that matter for that comparison. They took effect for loan reservations on or after June 8, 2026, and count the income of the borrowers on the loan, not every member of the household. A buyer over these limits can still look at NextKey, because NextKey has no income limit.
| DSHA program and area (effective June 8, 2026) | 1-2 person household | 3+ person household |
|---|---|---|
| Welcome Home – New Castle County, non-targeted | $122,700 | $141,105 |
| Welcome Home – New Castle County, targeted | $147,240 | $171,780 |
| Welcome Home – Kent and Sussex, non-targeted | $111,400 | $128,110 |
| Welcome Home – Kent and Sussex, targeted | $133,680 | $155,960 |
| Open Door – New Castle County | $147,240 | $184,050 |
| Open Door – Kent and Sussex | $133,680 | $167,100 |
Source: Delaware State Housing Authority, limits in effect since June 8, 2026, re-checked October 25, 2026. Current as of October 2026. For the full DSHA picture, see our guides to the DSHA Welcome Home loan and the DSHA Open Door loan.
Can you use both? No. DSHA assistance has to sit behind a DSHA first mortgage, and NextKey sits behind its own FHA first mortgage, so a buyer picks one path. When a buyer fits both, I lay the two side by side: the assistance amount, the first mortgage rate, how each second mortgage is paid back, and the cash to close. Then you choose with the numbers in front of you.
Delaware transfer tax: plan for it either way
Delaware’s realty transfer tax is one of the largest closing costs in the state, and under a standard Delaware resale contract the buyer and seller split it. Builders often write their own contracts and may ask the buyer to pay more of it, so read that line before you sign. First-time buyers may qualify for a state rate reduction (see the Delaware Division of Revenue first-time home buyer page and our transfer tax exemption guide). The 5% NextKey option can help cover part of this cost.
Does NextKey Raise Your Interest Rate or Payment?
Using NextKey usually means a somewhat higher interest rate on the FHA first mortgage than the same loan without assistance, as of October 2026. The forgivable option adds no monthly payment; the repayable option adds a 10-year second mortgage payment. Rates change daily, so the trade-off is priced on your own file.
Down payment assistance is not a gift, and I’m just being honest with you about that. The assistance is priced into the first mortgage, so the rate is often a bit higher than a plain FHA loan for the same buyer. What does that mean? You trade a small amount of monthly payment for getting into the home now instead of saving for another two or three years.
When a buyer asks me about NextKey, the first thing I show them is not the assistance amount. It is two payment quotes side by side: FHA with NextKey, and FHA with their own 3.5% down. Most buyers who are short on savings see that the difference is small next to the years of rent it would take to save the down payment. Some buyers who already have the cash decide to keep the lower rate. Either answer can be right, and you should see both numbers before you pick.
Monthly FHA mortgage insurance applies with or without NextKey. Our explainer on how mortgage insurance works covers what it costs and how long it lasts. You can also read more about the first mortgage itself in our Delaware FHA loan guide.
When NextKey Is Not the Right Fit
NextKey solves one problem very well: not having the down payment. It may not be your best choice if:
- You are an eligible veteran or service member. A VA loan can mean no down payment at all and no monthly mortgage insurance.
- You are buying in an eligible rural area. A USDA loan can also mean no down payment, subject to USDA income and property limits.
- You fit DSHA’s income limits and want DSHA’s assistance structure. Compare the two before you choose, because the assistance terms and the first mortgage rate differ.
- You already have the 3.5% down payment saved and plan to keep it. A plain FHA loan may give you a lower rate.
- You have a strong credit score and can put 3% to 5% down. A conventional loan may cost less over time because its mortgage insurance can come off.
- You expect to sell or refinance within about three years. A forgivable second would not be forgiven yet and would have to be repaid.
- You are buying a second home, an investment property, a single-wide manufactured home, or a home with three or more units. NextKey does not cover those.
How Do You Apply for NextKey in Delaware?
Apply for NextKey with the John Thomas Team by phone, by appointment or online. The team checks credit, income and debts, chooses the NextKey option that fits, issues a pre-approval, then registers the assistance once you have a signed contract, as of October 2026. Approval depends on full underwriting.
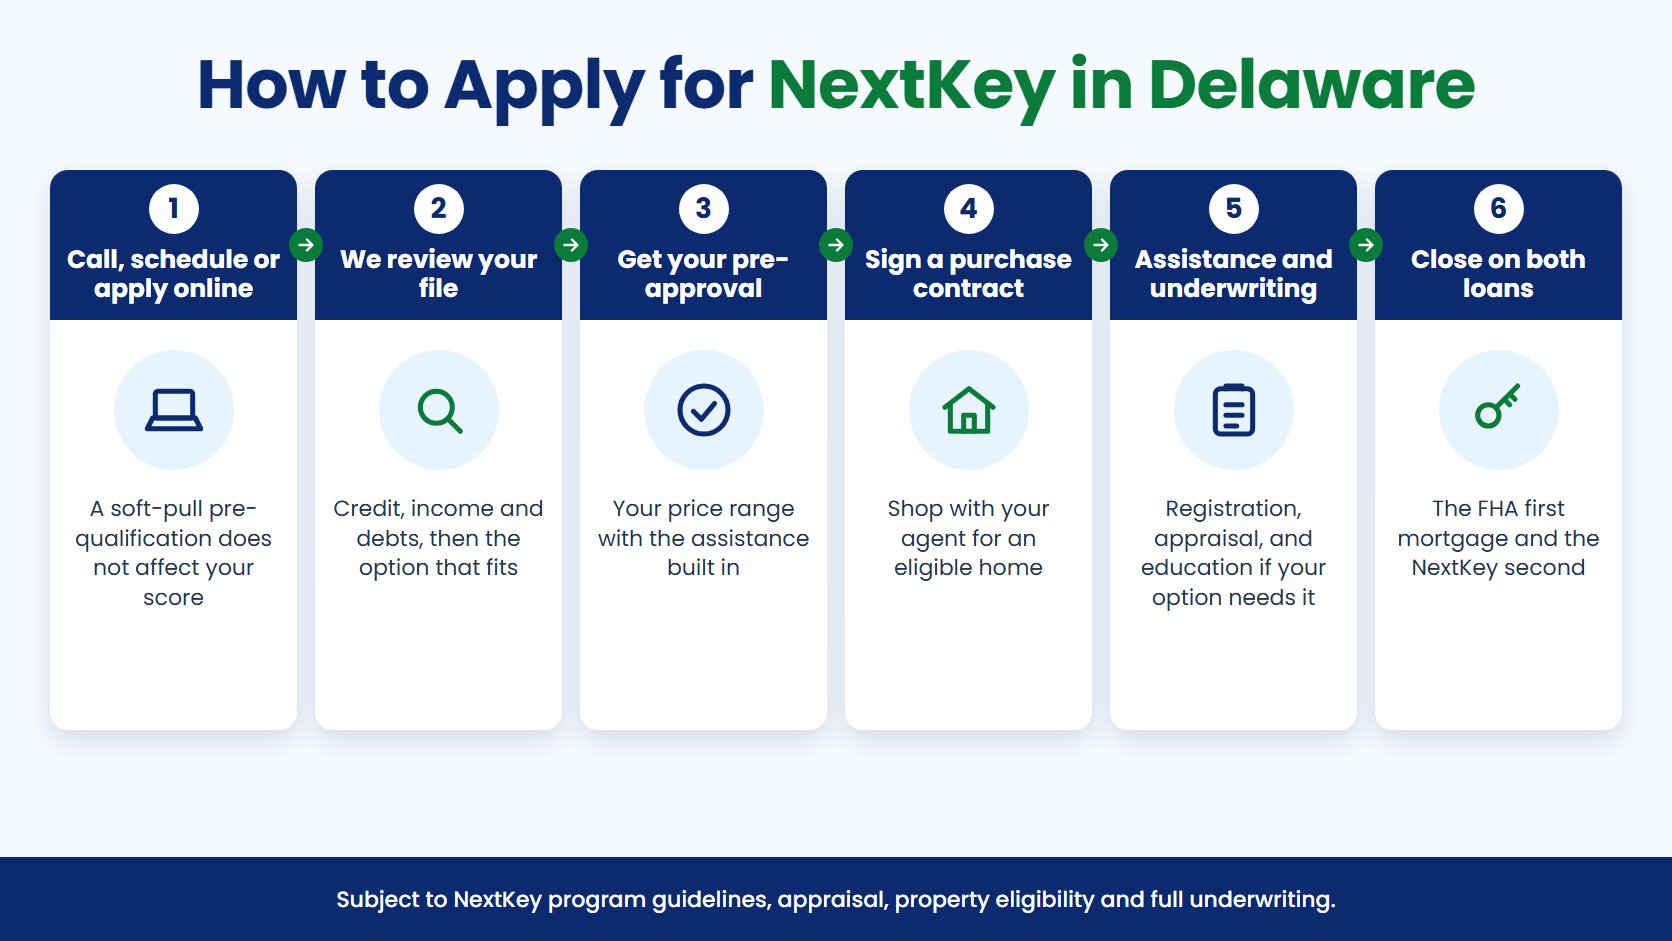
- Call 302-703-0727, schedule a 30-minute call, or apply online. A soft-pull pre-qualification does not affect your score.
- We review your credit, income and debts, and pick the NextKey option that fits your file.
- You get a pre-approval that shows your price range with the assistance built in.
- You shop with your agent and sign a purchase contract on an eligible home.
- We register your assistance, order the appraisal and finish underwriting. If your option needs a homebuyer education course, you complete it before closing.
- You review and sign both loans at closing: the FHA first mortgage and the NextKey second mortgage.
What to have ready: a photo ID, your last 30 days of pay stubs, two years of W-2s (or tax returns if you are self-employed), two months of bank statements, and your landlord’s contact information if you rent. If a family member is giving you money, we will also need a gift letter; our gift funds guidelines explain how to document it. Many clean files close in 21 days or less, depending on appraisal timing.
New to buying? Our Delaware first-time home buyer guide walks through the whole process, from pre-approval to the keys.
NextKey Down Payment Assistance FAQ
Is NextKey a grant or a loan?
NextKey is a second mortgage, not a grant. With the forgivable option you make no payments on it and pay no interest, and it can be forgiven after 36 on-time payments on your first mortgage, as long as you have not sold, refinanced or transferred the home first. With the repayable option you pay it back over 10 years with a fixed monthly payment. Either way it is recorded as a lien on your home, and your closing documents show its exact terms.
What credit score do I need for NextKey in Delaware?
The minimum credit score for NextKey is 600, as of October 2026. Buyers with scores between 600 and 639 may need to complete a homebuyer education course before closing, and some NextKey options and property types, such as some manufactured homes, start at a higher score. A 600 score means you meet the minimum; your income, debts and full underwriting decide the approval.
Do I have to be a first-time home buyer to use NextKey?
No. NextKey is open to first-time and repeat buyers. You can even own another home in some cases, as long as the home you are buying will be your primary residence and you explain the reason for the move in writing. The home you buy with NextKey must be the one you live in.
Are there income limits for NextKey?
No. NextKey has no income limits, which is the biggest difference from DSHA’s programs. DSHA’s Welcome Home and Open Door programs cap household income by county and household size. You still need enough stable income to qualify for the FHA first mortgage and, on the repayable option, the second mortgage payment, based on your debt-to-income ratio.
Can I use NextKey for a manufactured home in Delaware?
Yes, if it is a multi-section (double-wide or larger) manufactured home on a permanent foundation and titled as real estate, and it meets FHA’s manufactured housing rules. Single-wide homes and homes in a park where you do not own the land are not eligible. Some NextKey options need a higher credit score for manufactured homes, so tell us up front that you are looking at one.
Can my parents co-sign on a NextKey loan?
Yes, in most cases. FHA allows a family member who will not live in the home to be a co-borrower, and NextKey follows that rule. Their income can help you qualify for the FHA loan. At least one borrower must live in the home as a primary residence, and every borrower on the loan needs a credit score.
Can I combine NextKey with DSHA assistance or a seller credit?
You cannot combine NextKey with DSHA down payment assistance, because DSHA assistance requires a DSHA first mortgage and NextKey uses its own FHA first mortgage. You can use seller-paid closing costs within FHA’s limits, and gift funds from family are allowed. If a local grant is available that does not add another lien, ask us whether it can be layered on your file.
What happens if I sell or refinance before the assistance is forgiven?
The second mortgage has to be paid back. On the forgivable option, if you sell, refinance or transfer the home before you have made 36 qualifying payments on the first mortgage, the full assistance amount is due at that closing. On the repayable option, the remaining balance is paid off from the sale or refinance. If you think you may move within about three years, tell us so we can weigh that before you choose.
Will using NextKey raise my interest rate?
Usually a little. The cost of the assistance is built into the pricing of the FHA first mortgage, so the rate is often somewhat higher than the same FHA loan without assistance. Rates change daily, so call for current pricing. We quote your loan both ways, with NextKey and with your own down payment, so you can see the monthly difference before you decide.
John R. Thomas is Branch Manager and Division Vice President with the John Thomas Team in Newark, Delaware, and has helped Delaware families finance homes for more than 20 years. Many of the buyers he works with can afford a monthly payment but not the down payment, and he prices their loan with and without assistance so they can see the real trade-off before choosing between NextKey and DSHA.
John holds a BS in Physics Education from the University of Delaware and an MS in Curriculum and Instruction from Delaware State University. He is the author of Your Guide to Buying Your First Home in Delaware and a frequent host of Delaware home buyer seminars. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access. Read more on his loan officer bio page.
Years 3,000+
Buyers Helped 1,000+
Govt Loans DE & MD
Service Area CMP
Certified Mortgage Planner
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com
Schedule Appointment (30 min)
See John Thomas Team on Google for reviews, directions, and local office information.
YouTube | Facebook | Instagram | TikTok | X / Twitter | LinkedIn
Start Your NextKey Application in Delaware
The down payment doesn’t have to be what keeps you renting. Find out today how much NextKey could cover, and see your payment with and without it.
Last Updated: October 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
John R. Thomas, NMLS #38783 | John Thomas Team with AnnieMac Home Mortgage | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
AnnieMac Home Mortgage is an Equal Housing Lender. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access.
(c) Copyright John R. Thomas, All Rights Reserved.
