Delaware Mortgage Service Areas: Where John Thomas Lends
Delaware Mortgage Service Areas: the John Thomas Team lends on homes anywhere in Delaware and Maryland from its Newark, Delaware office. In Delaware the county sets the loan limits (a $630,200 FHA one-unit limit in New Castle County, $541,287 in Kent and Sussex, per HUD), and the town sets the local transfer tax and its first-time buyer break. Current as of November 2026.
You found a house you love, but you’re not sure whether the lender you’re talking to knows that town, or whether a program you read about even reaches that street. When someone tells me they’re buying in Delaware, one of my first questions is the address, because in a state this small the county line, a town boundary or a USDA map border can move your cash to close by thousands of dollars. I’m John Thomas, NMLS #38783, and this page shows every place we lend, what changes from one town to the next, and where each town’s own guide lives. New to buying? Start with our Delaware first-time home buyer programs overview.
Send Us the Address – We’ll Tell You Which Rules Apply
It starts with a soft credit pull that doesn’t touch your score. We’ll find the county and town for the home, check USDA’s map and the DSHA limits, list the local down payment help it qualifies for, and total your cash to close before you write an offer.
Table of Contents
Where Does the John Thomas Team Lend in Delaware and Maryland?
Anywhere in Delaware and Maryland. That covers all three Delaware counties, New Castle, Kent and Sussex, every town in them, and Maryland homes, with purchase and refinance loans for owner-occupied homes and other property types. Program rules still depend on the address: county limits, town taxes and USDA’s map vary from place to place.
Our office is at 248 E Chestnut Hill Rd, Newark, DE 19713, but most buyers never need to visit it. We work by phone, video and the online application, and settlement happens at a title company or attorney’s office near the home. Nine Delaware towns have their own detailed guide (below); every other town gets the same address check on a call. Maryland programs and taxes differ from Delaware’s, so the figures on this page are Delaware’s.
Which Delaware Towns Have Their Own Mortgage Guide?
Nine, as of November 2026: Wilmington, Newark, Middletown, Bear, Hockessin and Pike Creek in New Castle County, Dover and Smyrna in Kent County, and Milford, which sits in both Kent and Sussex County. Each guide covers that town’s limits, taxes, local programs and prices. Buyers anywhere else in Delaware or Maryland get the same address check.
New Castle County
All six of New Castle County’s DSHA targeted tracts are inside the City, where Welcome Home’s income limits rise to $147,240 and $171,780 and repeat buyers can use it. Inside City limits the City of Wilmington’s First Start program can help with down payment and closing costs; outside them, the County’s DPS program takes over. The City takes the 1.5% local share of the transfer tax. Median sale price: $257,877.
Wilmington DE mortgage loansThe City of Newark takes the 1.5% local transfer tax share, and Newark buyers sign the City’s deed-transfer affidavit at recording. The City also limits roomers and rentals, which matters if you plan to rent rooms near the University of Delaware. Prices split by ZIP: a $440,870 median in 19711 and $350,408 in 19713. New Castle County’s DPS program and DSHA’s New Castle limits apply; USDA doesn’t.
Newark Delaware mortgage loansMiddletown is an incorporated Town that takes the 1.5% local share of the transfer tax, so the County’s first-time buyer exemption doesn’t apply inside Town limits. USDA’s map shows the Town as ineligible, while the Odessa and Townsend addresses we tested were eligible. The Town’s median sale price was $417,301, and much of the area is new construction, so builder contracts get a close read.
Middletown Delaware mortgage loansBear is unincorporated New Castle County, so the County takes the 1.5% local transfer tax share and first-time buyers can use its partial exemption: 0.75% on up to $400,000, capped at $3,000. ZIP 19701’s median was $446,469. Bear-area schools split between the Christina, Colonial and Appoquinimink districts, and USDA’s boundary runs along Route 72 at Bear’s southern edge.
Bear Delaware mortgage loansHockessin is where New Castle County prices run highest. ZIP 19707’s $679,800 median sits above the $630,200 FHA one-unit limit, DSHA’s $659,385 price limit and the County DPS program’s $594,550 cap, but under the $832,750 conforming limit, so conventional financing is the usual fit. It’s unincorporated, so the County’s first-time buyer exemption applies, and USDA doesn’t reach it.
Hockessin Delaware mortgage loansPike Creek and Pike Creek Valley have no town government, so there’s no town transfer tax: the County takes the 1.5% local share and offers its first-time buyer exemption. ZIP 19808’s $394,884 median is within reach of FHA, DSHA and the County’s DPS program. Townhome and condo association checks come up often here, and USDA doesn’t reach Pike Creek.
Pike Creek Delaware mortgage loansKent and Sussex County
Inside Dover city limits, the City of Dover First Start program can put up to $20,000 toward settlement costs for eligible buyers, and the City offers a first-time home owner incentive on its share of the transfer tax; neither applies outside the City. No Dover address is in a DSHA targeted tract, Kent County limits apply, and Dover Air Force Base households often compare VA with FHA and DSHA.
Dover Delaware mortgage loansSmyrna straddles the Kent and New Castle County line at Duck Creek, and ZIP 19977 crosses it, so the parcel sets the limits: $541,287 for FHA on the Kent side, $630,200 on the New Castle side. The Town levies its own 1.5% transfer tax with no first-time buyer exemption. USDA has treated the Town as ineligible since October 1, 2023; nearby Clayton tested eligible. Town median: $344,786.
Smyrna Delaware mortgage loansThe Mispillion River splits Milford between Kent and Sussex County, though both sides share the same FHA and DSHA limits. First-time buyers pay no City transfer tax inside City limits, downtown north of the river is Kent County’s only DSHA targeted tract (0425.00), and every Milford address we tested sits outside USDA’s ineligible areas. Sussex-side homes can also use the County’s $20,000 Housing Trust Fund. City median: $329,843.
Milford Delaware mortgage loansMedian sale prices are Redfin’s for the three months ending September 2026, read on each town’s build in October 2026: City or Town figures for Wilmington, Middletown, Smyrna and Milford; ZIP figures for Newark (19711, 19713), Bear (19701), Hockessin (19707) and Pike Creek (19808). Loan limits: HUD 2026, FHFA 2026 and DSHA’s Program Notice effective June 8, 2026. Current as of November 2026.
How Do Loan Limits Change Between New Castle, Kent and Sussex County?
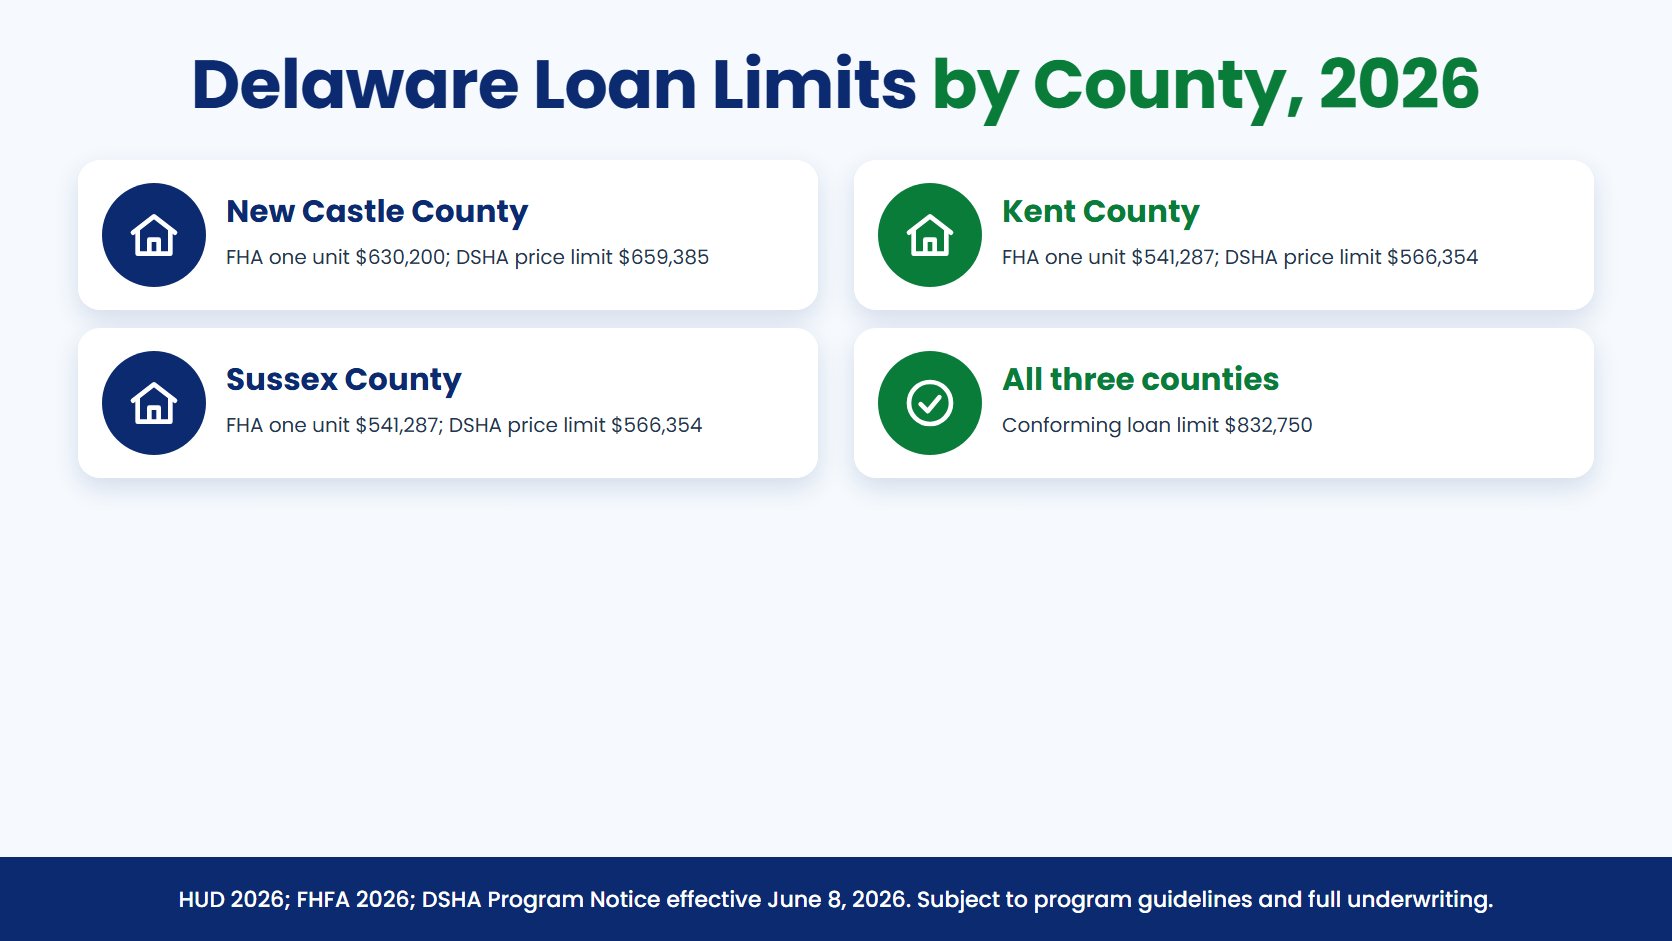
New Castle County’s limits are higher: as of November 2026 its FHA one-unit limit is $630,200 and DSHA’s price limit is $659,385, against $541,287 and $566,354 in Kent and Sussex County, which share one set of limits. The conforming limit is $832,750 statewide. DSHA’s targeted tracts carry higher limits in every county.
| 2026 limit | New Castle County | Kent County | Sussex County |
|---|---|---|---|
| FHA loan limit, one unit | $630,200 | $541,287 | $541,287 |
| Conforming loan limit, one unit | $832,750 | $832,750 | $832,750 |
| DSHA price limit, standard | $659,385 | $566,354 | $566,354 |
| DSHA price limit, targeted tracts | $805,916 (six tracts, all in Wilmington) | $692,211 (tract 0425.00, Milford) | $692,211 (tracts 0505.03 and 0507.11) |
| DSHA Welcome Home income limit, 1-2 / 3+ people | $122,700 / $141,105 | $111,400 / $128,110 | $111,400 / $128,110 |
| DSHA Open Door income limit, 1-2 / 3+ people | $147,240 / $184,050 | $133,680 / $167,100 | $133,680 / $167,100 |
A ZIP code can cross a county line. ZIP 19977 around Smyrna has homes in both New Castle and Kent County, and Milford’s 19963 spans Kent and Sussex, so we look up the parcel before quoting a limit. The full FHA table by unit count is on our Delaware FHA loan limits 2026 page, and DSHA’s programs are compared in the DSHA loan programs guide.
Who Collects the Local Transfer Tax in Your Delaware Town?
The town does inside an incorporated town or city, and the county does everywhere else. Delaware’s realty transfer tax is usually 4%: 2.5% to the State and 1.5% to the town or county, as of November 2026. Who collects the 1.5% decides which first-time buyer break you get, so the same price can cost different amounts a few miles apart.
| Where the home is | Who takes the 1.5% local share | First-time buyer break on the local share |
|---|---|---|
| City of Wilmington | City of Wilmington | Same as New Castle County: 0.75% on up to $400,000, capped at $3,000 |
| City of Newark | City of Newark | None; the City doesn’t waive its share |
| Town of Middletown | Town of Middletown | None in the Town code |
| Bear, Hockessin, Pike Creek, Glasgow and other unincorporated New Castle County | New Castle County | 0.75% on up to $400,000, capped at $3,000 |
| Town of Smyrna | Town of Smyrna | None in the Town code |
| City of Dover | City of Dover | City first-time home owner incentive |
| City of Milford | City of Milford | Not charged when every buyer is a first-time buyer |
| Unincorporated Kent County | Kent County | First-time buyers exempt |
| Unincorporated Sussex County | Sussex County | First-time buyers exempt from the buyer’s half |
| Other towns (Lewes, Rehoboth Beach, Seaford, Camden, Clayton and more) | Varies by town | We check the town’s rule for your parcel |
On top of the local break, first-time buyers anywhere in Delaware get the State’s own reduction on its 2.5%, which our Delaware first-time home buyer transfer tax exemption page explains with the Division of Revenue rules. Who pays which half is negotiable in the contract, and many sellers split it evenly, so we read your contract before totaling your cash to close.
Which Local Down Payment Help Reaches Your Address?
It depends on the city and county line. As of November 2026, Wilmington and Dover each run a First Start program for homes inside their city limits, New Castle County’s DPS program covers the rest of the county, and Sussex County’s Housing Trust Fund covers Sussex homes. DSHA’s down payment help works statewide on top of most of them.
| Program | Where the home must be | Help, as of November 2026 |
|---|---|---|
| City of Wilmington First Start | Inside Wilmington city limits | The lesser of $15,000 or 6%, forgiven over 10 years, for income-eligible buyers |
| New Castle County DPS program | New Castle County outside Wilmington | Up to $15,000 at 0%; price up to $594,550; household income at or below 80% of area median |
| City of Dover First Start | Inside Dover city limits | Up to $20,000 toward settlement costs for eligible buyers |
| Sussex County Housing Trust Fund | Sussex County | $20,000 toward closing costs; income under 120% of area median, liquid assets under $15,000 |
| DSHA down payment help | Anywhere in Delaware | A 0% deferred second loan of 3% to 5%, with a DSHA first mortgage and DSHA’s income and price limits |
| NextKey down payment program | Anywhere in Delaware | Down payment help with an FHA loan and no income ceiling |
The full side-by-side, with stacking rules, is in our Delaware down payment assistance programs guide. The short version: the city and county programs have their own income limits and counseling steps, and starting them right after pre-approval keeps them from delaying the closing.
Where Can You Use a USDA Loan in Delaware?
Mostly south of the Route 72 line and outside the larger towns. As of November 2026, USDA’s map excludes Wilmington, Newark, Pike Creek, Hockessin and most of Bear, the Town of Middletown, the Town of Smyrna and the Dover area, while Odessa, Townsend, Clayton, Milford and all of Sussex County tested eligible. USDA also caps household income.
| Area | USDA’s map, as we checked it |
|---|---|
| Wilmington, Newark, Pike Creek, Hockessin | Not eligible (north and west of the Porter Road – Route 72 line) |
| Bear | Core not eligible; the boundary runs along Route 72 at Bear’s southern edge |
| Town of Middletown | Not eligible (October 30, 2026) |
| Odessa and Townsend | Eligible (October 30, 2026) |
| Town of Smyrna | Not eligible since October 1, 2023 |
| Clayton and Cheswold | Eligible (October 31, 2026) |
| Dover area, Camden included | Not eligible (October 31, 2026) |
| Milford and Lincoln | Eligible (October 31, 2026) |
| Sussex County | No ineligible area in USDA’s data (October 31, 2026) |
USDA asks for no down payment on an eligible home for a household under its income limit that will live there (USDA Single Family Housing Guaranteed Loan Program). Map borders do change, which is how Smyrna lost eligibility in 2023, so we check the exact address every time. Income limits and the rest of the program are on our USDA rural home loans page.
What If Your Delaware Town Doesn’t Have Its Own Guide Yet?
We still lend there. Lewes, Rehoboth Beach, Seaford, Georgetown, Camden, Clayton, Glasgow, New Castle, Claymont, Odessa, Townsend and every other Delaware town use the county limits in the table above, the local transfer tax rules of that town or county, and USDA’s map. A call with the address settles which rules apply.
- Sussex County beach towns such as Lewes and Rehoboth Beach: Sussex limits apply, and the County’s Housing Trust Fund can help eligible buyers. A second home or a rental needs a loan built for it, because government and DSHA loans require you to live in the home.
- Seaford and western Sussex County: Sussex limits apply, and USDA’s data showed no ineligible area in the County when we checked on October 31, 2026.
- Odessa and Townsend: covered on our Middletown guide, since they share its area and school district.
- Clayton: covered on our Smyrna guide.
- Maryland: we lend there too. Maryland’s loan limits, transfer taxes and down payment programs are its own, so we price a Maryland home from Maryland’s rules, not this page’s.
What Do We Check on Every Delaware Address?
Six things, before you make an offer: the county, whether the home is inside a town’s limits, the census tract for DSHA’s targeted areas, USDA’s map, the local down payment programs that reach the address, and the transfer tax split in the contract. Together they set your loan limits, your program options and your cash to close.
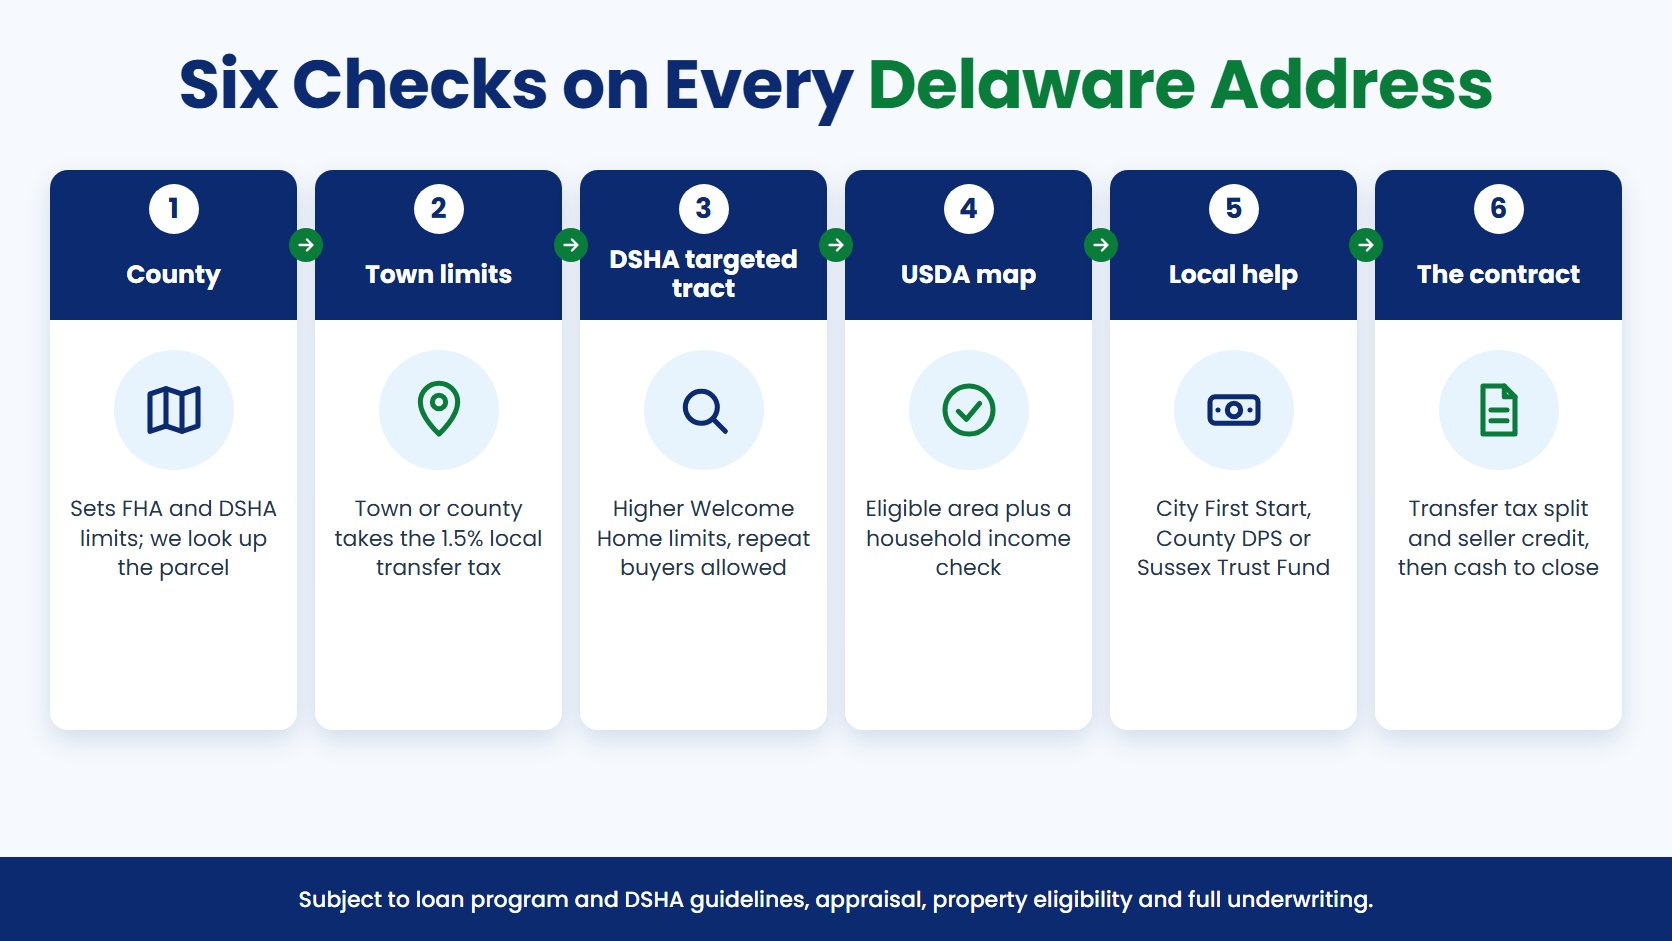
- County. It sets the FHA and DSHA limits. We look up the parcel, because ZIP codes like 19977 and 19963 cross county lines.
- Town limits. Inside a town or city, the town takes the 1.5% local transfer tax share and sets its own first-time buyer rule; outside, the county does.
- Census tract. DSHA’s targeted tracts raise Welcome Home’s limits and open it to repeat buyers.
- USDA’s map. A home in an eligible area may need no down payment, if the household’s income fits.
- Local programs. City First Start, County DPS or the Sussex Trust Fund, depending on the line the home sits on.
- The contract. Who pays which half of the transfer tax, and any seller credit, before we total your cash to close.
New to the process? John teaches a first-time homebuyer seminar; see the Delaware first-time home buyer seminars schedule. For the step-by-step version in writing, read the Delaware first-time home buyer guide.
FAQ: Delaware Mortgage Service Areas
Do you lend in Delaware towns that don’t have their own guide on this site?
Yes. We lend anywhere in Delaware, including Lewes, Rehoboth Beach, Seaford, Georgetown, Camden, Clayton, Glasgow, New Castle and Claymont. Every Delaware town uses its county’s loan limits, its own or the county’s transfer tax rules, and USDA’s map, so a call with the address tells us which programs reach the home, as of November 2026.
Do you lend in Maryland?
Yes. The John Thomas Team lends on Maryland homes as well as Delaware homes. Maryland’s loan limits, transfer and recordation taxes and down payment programs are Maryland’s own, so the Delaware figures on this page don’t carry over; we price a Maryland purchase from Maryland’s rules. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access.
Do I have to come to the Newark office?
No. Most buyers work with us by phone, video and the online application, wherever in Delaware or Maryland they’re buying, and documents can be uploaded securely. Settlement takes place at a title company or settlement attorney’s office, usually near the home. You’re welcome at 248 E Chestnut Hill Rd, Newark, DE 19713 if you’d rather meet in person.
My ZIP code is in two counties. Which loan limits apply?
The county the parcel sits in, not the ZIP code. Around Smyrna, ZIP 19977 crosses the New Castle and Kent County line, where the 2026 FHA one-unit limit is $630,200 on one side and $541,287 on the other. Milford’s 19963 spans Kent and Sussex, which share limits. We look up the parcel in the county’s property records before quoting a limit.
Is the transfer tax the same everywhere in Delaware?
The total is usually 4%, 2.5% to the State and 1.5% to the town or county, but the first-time buyer break on the local 1.5% depends on who collects it. As of November 2026, Milford charges first-time buyers no City share, Wilmington and unincorporated New Castle County take 0.75% off up to $400,000, and Newark, Middletown and Smyrna have no exemption. The State’s own reduction applies everywhere.
I’ve owned a home before. Can DSHA still help me?
Yes, in two ways, as of November 2026. Open Door is open to repeat buyers anywhere in Delaware, within DSHA’s income and price limits. Welcome Home is limited to first-time buyers except in DSHA’s targeted census tracts, such as the six in Wilmington and tract 0425.00 in Milford, where repeat buyers can use it at higher limits. We check the tract from the address.
Does USDA reach Sussex County beach towns like Lewes and Rehoboth Beach?
USDA’s eligibility data showed no ineligible area anywhere in Sussex County when we checked on October 31, 2026, so beach-area addresses can qualify on location. The household’s income must still fit USDA’s limit, the buyer must live in the home, and USDA confirms each address, so a second home or rental doesn’t qualify.
Can I combine county or city down payment help with DSHA?
Often, subject to each program’s rules. New Castle County’s DPS program can be combined with DSHA down payment help, and the Sussex County Housing Trust Fund can sit beside a DSHA second on a Sussex home. Each program has its own income limit, counseling and approval steps, so we line them up right after pre-approval. See our Delaware down payment assistance programs guide.
How quickly can you close on a home anywhere in Delaware?
A complete file typically clears underwriting in 24 to 48 hours, and many clean files close in 21 days or less when the appraisal comes back on time, in any Delaware county. City and county down payment programs add their own counseling and approval time, so start those steps as soon as you’re pre-approved.
What does it cost to find out which programs fit my address?
Nothing up front. There’s no application fee and no upfront fee, and pre-qualification uses a soft credit pull that doesn’t affect your score. Send us the address, or the town if you’re still looking, and we’ll tell you the county limits, the local transfer tax rule, the USDA result and the down payment help that reaches it.
About Your Delaware Mortgage Lender, John Thomas
John R. Thomas has helped Delaware families buy homes for more than 20 years and is Branch Manager and Division Vice President of the John Thomas Team in Newark. A Glasgow High School graduate who still lives in Newark, he taught physics and physical science at Delcastle High School for more than ten years before lending full time, and he owned and ran a local SERVPRO franchise. With any Delaware buyer, John starts with the address: which county, whether it’s inside a town’s limits, and what USDA’s map says. Then he looks at which of the traditional loan programs, FHA, VA, USDA or conventional, makes the most sense for the buyer and which ones the buyer qualifies for.
He holds a BS in Physics Education from the University of Delaware and an MS in Curriculum and Instruction from Delaware State University in Dover, and has been a Certified Mortgage Planner since 2008. John wrote Your Guide to Buying Your First Home in Delaware, the basis of our Delaware first-time home buyer guide, and teaches the seminars himself. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access. Read his loan officer bio page or meet the John Thomas Team.
Years 3,000+
Buyers Helped 1,000+
First-Time Buyers DE & MD
Service Area CMP
Certified Mortgage Planner
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com
Schedule Appointment (30 min)
See John Thomas Team on Google for reviews, directions, and local office information.
YouTube | Facebook | Instagram | TikTok | X / Twitter | LinkedIn
- Within 4 business hours you’ll hear from us by phone, text and email, and we keep following up for 14 days (the 4-14-24 standard).
- Once your documents arrive, a licensed loan officer reviews them for pre-approval within 24 hours.
- With a Platinum Pre-Approval, an underwriter reviews the full file before you make an offer; the appraisal and final approval remain.
- A single Loan Concierge handles your file from contract to closing and sends a Tuesday status email to everyone involved.
- New calls are answered Saturday and Sunday from 9 AM to 4 PM, for buyers writing offers on the weekend.
We start with a soft credit pull that doesn’t touch your score. Then we check the county, the town line, USDA’s map and DSHA’s targeted tracts, list the local help that reaches the home, and total your cash to close before you write an offer.
Last Updated: November 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
John R. Thomas, NMLS #38783 | John Thomas Team with AnnieMac Home Mortgage | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
AnnieMac Home Mortgage is an Equal Housing Lender. State licensing: Look up John R. Thomas, NMLS #38783, on NMLS Consumer Access.
(c) Copyright John R. Thomas, All Rights Reserved.
