
Delaware Down Payment Assistance Programs (2026 Guide)

Delaware down payment assistance programs help eligible homebuyers cover the cash needed for down payment and closing costs when purchasing a home. Most programs are offered through the Delaware State Housing Authority (DSHA) and typically provide 3% to 5% of the loan amount as a deferred, 0% interest second mortgage with no monthly payments. The four active DSHA DPA programs are First State Home Loan (3%), Keys4You (4%), Take5 (5% Welcome Home only), and Diamond in the Rough (5% + FHA 203k, Welcome Home only). These programs can be paired with FHA, VA, USDA, and conventional loans and are available to buyers in New Castle, Kent, and Sussex Counties. As a DSHA-approved lender, John Thomas Team helps buyers identify and combine programs for maximum savings – call 302-703-0727 to check eligibility.
Current as of September 2026. Income and purchase price limits are the DSHA set effective for reservations on or after June 8, 2026; interest rates are the DSHA sheet dated September 12, 2026. DSHA program rules, income limits, rates, and funding status are reviewed against the official Delaware Mortgage Program at destatehousing.com.
I’ve spent over 20 years helping Delaware buyers use Delaware down payment assistance programs to get into homes they thought were out of reach. The most common thing I hear from first-time buyers is: “I didn’t think I would qualify.” Most of the time, they do – and that’s exactly what this guide is for.
Whether you’re buying in Wilmington, Dover, Georgetown, or anywhere else in the First State, there are programs designed to cover your down payment, your closing costs, or both. I’m going to walk you through everything – every active program by county, income limits, how to combine programs, and common mistakes to avoid. If you have questions along the way, call us at 302-703-0727 or apply online.
*First lien interest rates may be higher when using a DPA second mortgage.
Find Out Which Delaware DPA Program You Qualify For
DSHA-approved lender | Serving all 3 Delaware counties | Free consultation
Table of Contents
Who Delaware DPA Is Best For
- First-time buyers with limited savings
- Buyers using FHA, VA, USDA, or conventional loans
- Essential workers, educators, and first responders
- Buyers purchasing a primary residence in Delaware
- Buyers who need help stacking programs for max benefit
Who DPA Programs Are Not Designed For
- Real estate investors or second-home buyers
- Buyers using internet-only or out-of-state lenders
- Buyers closing on a home they already purchased
- Non-owner-occupant purchases
What Are Delaware Down Payment Assistance Programs?
Most Delaware buyers use DSHA’s First State Home Loan DPA because it provides 3% of the loan amount as a deferred 0% interest second mortgage – no monthly payments required, and it works with FHA, VA, USDA, and conventional loans statewide. Buyers needing more can move up to Keys4You (4%) under both Welcome Home and Open Door, or Take5 (5%) under Welcome Home only.
Delaware down payment assistance programs are financial tools that help homebuyers cover the largest obstacle to homeownership: the upfront cash requirement. Instead of needing to save thousands of dollars on your own before you can buy, these Delaware down payment assistance programs step in to cover part – or in some cases all – of your required down payment and closing costs.
Most programs in Delaware are administered through the Delaware State Housing Authority (DSHA), a state agency whose entire mission is to help Delaware residents become homeowners. DSHA-approved lenders like the John Thomas Team access these programs on your behalf and build them directly into your mortgage financing. Official program information is available on the Delaware Mortgage Program (DSHA) website at destatehousing.com. Note: DSHA retired the “Kiss Your Landlord Goodbye” branding entirely in the April 2026 rebrand and consolidated everything under the Delaware Mortgage Program at destatehousing.com. Older sites still linking to kissyourlandlordgoodbye.com are working from outdated information.
Down payment assistance in Delaware typically comes in one of three forms: a deferred second mortgage (no payments until you sell or refinance), a forgivable loan (reduced or eliminated after a set period of occupancy), or a grant (no repayment at all). The right structure depends on the program and your situation – and I’ll walk you through each one below.
How Much Down Payment Assistance Can I Get in Delaware?
Most Delaware buyers receive between 3% and 5% of their loan amount in down payment assistance – enough to cover most or all of a 3.5% FHA down payment. County and city programs in New Castle, Kent, and Sussex can add a further $10,000 to $20,000 for buyers who meet their separate income and property rules.
The amount you can receive depends on which program(s) you qualify for. Here’s a realistic look at what’s available across the most common programs:
| Program | Type | Amount | Repayment | Who Qualifies |
|---|---|---|---|---|
| DSHA First State Home Loan DPA | Deferred 2nd mortgage | 3% of loan amount | Deferred until sale/refi | Welcome Home or Open Door borrowers |
| DSHA Keys4You Home Loan | Deferred 2nd mortgage | 4% of loan amount | Deferred until sale/refi | Welcome Home AND Open Door borrowers |
| DSHA Take5 Home Loan | Deferred 2nd mortgage | 5% of loan amount | Deferred until sale/refi | Welcome Home borrowers only |
| DSHA Diamond in the Rough DPA | Deferred 2nd mortgage | 5% of loan amount | Deferred until sale/refi | FHA 203k renovation buyers (Welcome Home only) |
| NCC Down Payment Settlement (DPS) | Deferred loan | Up to $10,000 | 15-year term (2-yr deferral) | New Castle County first-time buyers |
| DSHA Home Sweet Home | Forgivable loan | $12,000 | Forgiven after 10 yrs | Homes ≤$285,000 (currently out of funds) |
| City of Wilmington First Start | Deferred loan | Varies | Deferred | Wilmington city homebuyers |
Here’s a real-world example: a buyer purchasing a $325,000 home in Delaware using an FHA loan with the DSHA First State Home Loan DPA (3%) would receive approximately $9,409 in assistance – enough to cover the entire FHA down payment of 3.5% ($11,375), with seller-paid closing costs covering the remainder. That’s a $325,000 home purchase with potentially under $2,000 out of pocket.
Best Delaware DPA Program by Buyer Type
| First-time buyer, under DSHA income limits | Welcome Home + First State Home Loan DPA (3%) |
| First-time buyer needing max DPA (no renovation) | Welcome Home + Take5 (5% DPA) |
| Repeat buyer or higher income | Open Door + Keys4You (4% DPA) – Open Door’s maximum DPA |
| Buying a fixer-upper or home needing repairs | DSHA Diamond in the Rough (5% DPA + FHA 203k) |
| Above DSHA income limits | Open Door (higher limits than Welcome Home), or a county/city program with its own separate income rules — call and we will check which you clear |
| Buying in New Castle County with limited income | NCC DPS Program (up to $10,000) + DSHA DPA |
What Are the Current DSHA Down Payment Assistance Programs in Delaware?
All DSHA DPA programs must be paired with a DSHA first mortgage – either the DSHA Welcome Home Program (first-time buyers) or the DSHA Open Door Program (all buyers, higher income limits) – and must be obtained through a DSHA-approved lender. You cannot use DSHA DPA with an internet lender or an out-of-state lender. Note: Open Door replaced the legacy “Home Again” program in the April 2026 DSHA rebrand.
DSHA Interest Rates as of September 12, 2026 (verify at destatehousing.com — rates set daily)
| Product | Welcome Home | Open Door |
|---|---|---|
| FHA, VA, RD — Smart Start (no DPA)* | 5.375% | 6.875% |
| FHA, VA, RD — First State Home Loan 3%** | 5.625% | 7.625% |
| FHA, VA, RD — Keys4You Home Loan 4%*** | 5.875% | 7.750% |
| FHA, VA, RD — Take5 Home Loan 5%**** | 6.375% | Not available |
| FHA — Diamond in the Rough 5%***** | 6.375% | Not available |
| Conventional — Smart Start (no DPA)* | 5.875% | 7.250% |
| Conventional — First State Home Loan 3%** | 6.125% | 8.000% |
| Conventional — Keys4You Home Loan 4%*** | 6.250% | 8.125% |
| Conventional — Take5 Home Loan 5%**** | 6.750% | Not available |
Rates shown are the DSHA rate sheet dated September 12, 2026 and are subject to change daily. They are not a quote, not an APR, and not a rate lock. Always check the DSHA website for current rates, or call 302-703-0727 for today’s rate, before committing: destatehousing.com/homeownership-loans. Note the pattern the table shows: within either track, the unassisted Smart Start rate prices lowest, and each step up in assistance prices the rate higher. *No DPA. **3% DPA deferred. ***4% DPA deferred, both WH and OD. ****5% DPA deferred, Welcome Home only. *****Diamond in the Rough 5% DPA paired with FHA 203k, Welcome Home only.
DSHA First State Home Loan DPA (3%) – Most Popular Program
The DSHA First State Home Loan DPA Program – formerly known as the Preferred Plus Program – provides 3% of your first mortgage loan amount toward down payment and closing costs as a soft second mortgage at 0% interest with no required monthly payments. The principal is deferred until you sell, refinance, transfer title, or the home is no longer your primary residence. This is the most widely used DSHA DPA and can be paired with either Welcome Home or Open Door. For more detail, see our complete DSHA loan programs guide.
DSHA Keys4You Home Loan (4% DPA) – Both Welcome Home and Open Door
The DSHA Keys4You Home Loan provides 4% of your first mortgage loan amount as a deferred 0% interest second mortgage with no required monthly payments. Keys4You is available under both Welcome Home and Open Door, making it the strongest middle-tier DPA option for Delaware buyers. For repeat buyers using Open Door, Keys4You is the maximum DPA available – 4% of the loan amount.
Important context: Before April 2026, Delaware’s 4% DPA was Home Again-only and had no official program name. In April 2026, DSHA consolidated everything under the new Delaware Mortgage Program – Home Again was renamed to Open Door, the 4% DPA was branded as Keys4You and opened to buyers under both Welcome Home AND Open Door, and Take5 (5% Welcome Home only) launched as a new program. Any site still listing the 4% DPA as “Home Again only” is working from outdated information.
DSHA Take5 Home Loan (5% DPA) – Welcome Home Only
The DSHA Take5 Home Loan provides 5% of your first mortgage loan amount as a deferred 0% interest second mortgage – the highest DPA percentage available without a renovation component. Take5 is available under the Welcome Home program only, not Open Door. For first-time buyers who qualify under Welcome Home’s income limits, Take5 is the maximum DPA on a standard purchase.
DSHA Diamond in the Rough DPA (5%) – For FHA 203k Renovation Buyers
The DSHA Diamond in the Rough Program provides 5% of the final loan amount in DPA for buyers using an FHA 203(k) Limited renovation loan. This is the highest DSHA DPA percentage available when paired with a renovation loan and is ideal for buyers purchasing a home that needs minor repairs or updates (up to $75,000 in renovation costs per HUD Mortgagee Letter 2024-13). The assistance is a deferred 0% second mortgage with the same repayment terms as the First State Home Loan. Diamond in the Rough is Welcome Home only.
DSHA Delaware Diamond DPA – $10,000 for Essential Workers (Currently Out of Funds)
The DSHA Delaware Diamond DPA Program provides $10,000 toward down payment and closing costs for Delaware essential workers – educators, healthcare workers, first responders, veterans, grocery workers, and state employees. Forgivable after 10 years. Currently out of funds with no announced refunding plans. We keep this page live because national mortgage sites still list the program as active and buyers searching for it deserve accurate status information.
DSHA Home Sweet Home DPA – $12,000 Forgivable (Currently Out of Funds)
The DSHA Home Sweet Home DPA Program provides a $12,000 forgivable second mortgage for buyers purchasing homes priced at $285,000 or less. Forgives 10% per year; fully eliminated after 10 years. Currently out of funds with no announced refunding plans.
DSHA Homes for Grads – 0.50% Rate Reduction for College Graduates (Currently Suspended)
The DSHA Homes for Grads Program offered college graduates a 0.50% reduction on their DSHA first mortgage interest rate in addition to down payment assistance. The borrower or co-borrower must have earned a four-year degree within three years of the rate lock. Currently suspended – contact us for reinstatement updates.
DSHA Manufactured Home Rules
If you are considering a manufactured home in Delaware with DSHA financing, four published program guidelines apply:
- The home must be double-wide or larger – single-wides do not qualify
- Minimum 660 credit score for all borrowers (higher than the standard 620 DSHA minimum)
- FHA 203(k) is not allowed on manufactured homes – which means Diamond in the Rough is not available for these properties
- DSHA manufactured home financing is FHA-only
What Are the DSHA Income Limits for Delaware Down Payment Assistance?
DSHA income limits vary by county, household size, and whether you’re in a targeted or non-targeted area. Effective April 15, 2025: Welcome Home counts only income of borrowers on the Note and/or Mortgage; Open Door counts only qualifying income on the 1003 – not all household members’ income. The limits below took effect for loan reservations on or after June 8, 2026:
DSHA Welcome Home Income Limits (First-Time Buyers) — Effective June 8, 2026
| County | Area | 1-2 Person Household | 3+ Person Household |
|---|---|---|---|
| New Castle County | Non-Targeted Areas | $122,700 | $141,105 |
| New Castle County | Targeted Areas | $147,240 | $171,780 |
| Kent & Sussex Counties | Non-Targeted Areas | $111,400 | $128,110 |
| Kent & Sussex Counties | Targeted Areas | $133,680 | $155,960 |
DSHA Open Door Income Limits (All Buyers – Formerly Home Again) – Effective June 8, 2026
| County | 1-2 Person Household | 3+ Person Household |
|---|---|---|
| New Castle County | $147,240 | $184,050 |
| Kent & Sussex Counties | $133,680 | $167,100 |
Purchase price limits (non-targeted, single family, effective June 8, 2026): New Castle County: $659,385 | Kent & Sussex Counties: $566,354. In targeted areas the purchase price limits rise to $805,916 in New Castle County and $692,211 in Kent and Sussex. If your income exceeds Welcome Home limits, you may still qualify under Open Door. If you exceed both, a county or city program may still fit, since those carry their own separate income rules — call 302-703-0727 and we will check. Source: Delaware State Housing Authority (verified September 2026).
What Is a DSHA Targeted Area?
DSHA designates specific census tracts across Delaware as Targeted Areas — typically lower-income communities where the state wants to encourage homeownership investment. Purchasing in a targeted area has two significant advantages: income limits are substantially higher (see the Targeted Areas rows in the Welcome Home table above), and the first-time homebuyer requirement is waived entirely. This means a buyer who currently owns a home — or who owned one recently — can still qualify for Welcome Home if the property is in a targeted area. If you are purchasing in Wilmington, parts of Dover, or other designated census tracts, ask us whether your specific address sits in a designated tract – the targeted-area income and purchase price limits are shown above.
Delaware Transfer Tax — What Every Buyer Must Know
Delaware charges a 4% total transfer tax at settlement. Under a standard Delaware Association of Realtors (DAR) contract, this splits equally: 2% paid by the buyer and 2% paid by the seller. However, home builders write their own contracts and may require the buyer to pay the full 4%. On a $400,000 new construction home, that is a $16,000 transfer tax burden instead of $8,000 — an $8,000 difference that directly affects how much cash you need at closing and how much DPA you should request. Always confirm transfer tax responsibility before signing any builder contract. Separately, Delaware first-time homebuyer transfer tax exemptions may also apply — ask us about eligibility.
What Delaware Down Payment Assistance Programs Are Available by County?
Delaware has more down payment assistance options than most states – statewide DSHA programs, county-specific programs in all three counties, city programs in Wilmington and Dover, and lender-sponsored grants with no income limits. Below is the complete list, including active, out-of-funds, suspended, and historical programs.
Delaware has a layered ecosystem of state, county, city, and lender-sponsored Delaware down payment assistance programs. Below is the complete list organized by county – including active programs, programs currently out of funds that may be refilled, and inactive programs preserved here for historical reference (many buyers still search for them by name).
New Castle County Delaware Down Payment Assistance Programs
Currently Active:
- New Castle County Workforce Housing Program
- New Castle County Down Payment Settlement (DPS) Program – Up to $10,000; 15-year repayment term with 2-year payment deferral
- City of Wilmington First Start Homebuyer Program
- City of Wilmington Employee Home Buyer Assistance Program (Live Near Your Work)
- DSHA First State Home Loan DPA Program – 3%, deferred, 0% interest, both Welcome Home and Open Door
- DSHA Keys4You Home Loan – 4% DPA, deferred, 0% interest, both Welcome Home and Open Door
- DSHA Take5 Home Loan – 5% DPA, deferred, 0% interest, Welcome Home only
- DSHA Diamond in the Rough (5% + FHA 203k) – For renovation buyers, Welcome Home only
Currently Out of Funds / Suspended – Check for Updates:
- DSHA Delaware Diamond DPA Program – $10,000 forgivable for essential workers (Currently Out of Funds, no refund plans)
- DSHA Home Sweet Home DPA Program – $12,000 forgivable, homes at or below $285,000 (Currently Out of Funds, no refund plans)
- DSHA Homes for Grads Program – Rate reduction for college graduates (Currently Suspended)
No Longer Available – Historical Reference:
- DSHA Home Again Program (Rebranded to Open Door in April 2026)
- New Castle County IDEA Program (No Longer Available)
- New Castle County ReVaMP Program (No Longer Available)
- New Castle County Vacant Home Buyer Program (VHAP) (No Longer Available)
- City of Newark DPA (No Longer Available)
- City of Newark POOH Program (No Longer Available)
- DSHA SMAL Loan Program (No Longer Available)
- DSHA Advantage 4 Grant Program (No Longer Available)
- DSHA Preferred Plus Program (Replaced by First State Home Loan DPA)
Kent County Delaware Down Payment Assistance Programs
Currently Active:
- City of Dover First Start Program – Up to $20,000 as a 0% interest forgivable second mortgage, fully forgiven after 10 years of primary residency. Requires the borrower not to have owned a home in the past 3 years and household income within the City of Dover’s published limits, which follow the HUD Kent County income tiers by household size (see the Dover First Start page for the current table, the asset cap, and the funding balance). Works with FHA, VA, and conventional loans. Can stack with DSHA DPA or go into 3rd lien position.
- DSHA First State Home Loan DPA Program – 3%, deferred, 0% interest, both Welcome Home and Open Door
- DSHA Keys4You Home Loan – 4% DPA, both Welcome Home and Open Door
- DSHA Take5 Home Loan – 5% DPA, Welcome Home only
- DSHA Diamond in the Rough (5% + FHA 203k) – Welcome Home only
Currently Out of Funds / Suspended:
- DSHA Delaware Diamond DPA Program (Currently Out of Funds)
- DSHA Home Sweet Home DPA Program (Currently Out of Funds)
- DSHA Homes for Grads Program (Currently Suspended)
No Longer Available – Historical Reference:
- DSHA Home Again Program (Rebranded to Open Door in April 2026)
- DSHA SMAL Loan Program (No Longer Available)
- DSHA Advantage 4 Grant Program (No Longer Available)
- DSHA Preferred Plus Program (Replaced by First State Home Loan DPA)
Sussex County Delaware Down Payment Assistance Programs
Currently Active:
- Sussex County Housing Trust Fund DPA – A flat $20,000, one tier, not a sliding scale. The money is for closing and settlement costs only – it cannot be taken as cash back and cannot reimburse a down payment or prepaids; any excess is applied as a principal curtailment. Structured as a 0% interest silent second mortgage with no monthly payments, fully forgiven after 10 years of primary residency. Open to both first-time and repeat buyers purchasing in Sussex County. Works with FHA, VA, USDA, and conventional loans, and does not affect the interest rate on the first mortgage. Note the income rule differs from DSHA: Sussex counts every adult wage earner in the household, even those not on the mortgage or the deed. Funds replenish annually on July 1 and are first-come, first-served.
- DSHA First State Home Loan DPA Program – 3%, deferred, 0% interest, both Welcome Home and Open Door
- DSHA Keys4You Home Loan – 4% DPA, both Welcome Home and Open Door
- DSHA Take5 Home Loan – 5% DPA, Welcome Home only
- DSHA Diamond in the Rough (5% + FHA 203k) – Welcome Home only
Currently Out of Funds / Suspended:
- DSHA Delaware Diamond DPA Program (Currently Out of Funds)
- DSHA Home Sweet Home DPA Program (Currently Out of Funds)
- DSHA Homes for Grads Program (Currently Suspended)
No Longer Available – Historical Reference:
- DSHA Home Again Program (Rebranded to Open Door in April 2026)
- DSHA SMAL Loan Program (No Longer Available)
- DSHA Advantage 4 Grant Program (No Longer Available)
- DSHA Preferred Plus Program (Replaced by First State Home Loan DPA)
Most DSHA buyers with a credit score below 660 are required to complete 8 hours of HUD-approved homebuyer counseling through a HUD-approved agency, and several county and city programs require it regardless of score. This requirement is satisfied by attending a Delaware First-Time Homebuyer Seminar. Our team hosts free monthly seminars in Newark, Dover, and Wilmington – and it’s a required step for most DSHA programs if your credit score is below 660.
How Do You Qualify for Delaware Down Payment Assistance?
To qualify for most Delaware down payment assistance programs, you need a minimum 620 credit score, household income at or below DSHA county limits, and you must purchase a primary residence in Delaware through a DSHA-approved lender. Internet lenders and out-of-state lenders are not eligible.
Qualification requirements vary by program, but most Delaware down payment assistance programs share a consistent baseline. Here’s what lenders review when you apply:
| Requirement | Typical Threshold | Notes |
|---|---|---|
| Credit Score | 620 minimum (all borrowers) | Scores 620-659 require HUD-approved housing counseling |
| Household Income | At or below DSHA limits by county | Effective April 15, 2025: WH counts only income on Note/Mortgage; OD counts only qualifying income on 1003 |
| First-Time Buyer Requirement | Required for Welcome Home; waived for Open Door | “First-time” = no home ownership in prior 3 years |
| Property | Primary residence only in Delaware | No investment properties or second homes |
| Purchase Price | NCC ≤$659,385 | Kent/Sussex ≤$566,354 (eff. June 8, 2026) | Targeted area limits are higher |
| Approved Lender | Must use DSHA-approved lender | Internet lenders and out-of-state lenders are NOT eligible |
| Homebuyer Counseling | Required if credit score below 660 | 8 hours HUD-approved; satisfied by our free monthly seminars |
Critical note: You must enroll in a DSHA DPA program before you close on your home – not after. DPA cannot be applied retroactively once you’ve already purchased. This is why getting pre-approved early matters so much.
What Loan Types Can Be Combined With Delaware Down Payment Assistance?
DSHA down payment assistance can be layered on top of FHA, VA, USDA, and conventional loans – making it one of the most flexible state DPA programs in the country. The DPA second mortgage does not affect your monthly payment, which is calculated on the first mortgage only.
One of the biggest advantages of Delaware down payment assistance programs is their flexibility with underlying loan products. The DSHA first mortgage can be structured as conventional, FHA, VA, or USDA – and the DPA second mortgage stacks on top:
- Delaware FHA Loans – 3.5% minimum down payment, credit scores from 580 with DPA, seller can pay up to 6% in closing costs. The most common first-time buyer combination with DSHA DPA.
- Delaware VA Loans – $0 down for eligible veterans and active-duty service members. DPA can cover closing costs when paired with a DSHA VA first mortgage.
- Delaware USDA Rural Loans – $0 down in eligible rural areas across Delaware. DPA can be layered for closing cost coverage.
- Delaware Conventional Loans – 3% down with HomeReady or Home Possible, paired with DSHA DPA for buyers who want to avoid FHA mortgage insurance premiums.
Does Delaware Have a First-Time Homebuyer Tax Credit?
The Delaware Mortgage Credit Certificate (MCC) program ended on August 15, 2025 and is no longer accepting applications. Many national mortgage sites, accountants, and CPAs still reference the MCC as if it were active – which is why so many Delaware buyers still ask about it. Our MCC page explains how the program worked, when it ended, and what DSHA replaced it with.
The MCC was a DSHA-sponsored federal tax credit that allowed eligible first-time buyers to claim up to 35% of their annual mortgage interest as a direct credit against their federal income taxes, capped at $2,000 per year. It ended on August 15, 2025. No new applications are being accepted.
If you found this page while searching for the Delaware MCC, your next step is the full MCC program page for the complete history and current status. Or call us at 302-703-0727 if you have specific questions about how the MCC ending affects your buying plans.
What Does a Real Delaware DPA Scenario Look Like?
A first-time buyer purchasing a $325,000 home in Delaware with FHA + DSHA Welcome Home + First State Home Loan DPA can receive approximately $9,409 in assistance – enough to buy the home with under $2,000 out of pocket when combined with seller-paid closing costs.
Here is a real-world example based on a buyer profile I work with regularly across all three Delaware counties:
Sussex County First-Time Buyer — $325,000 Purchase Price
Loan Type: FHA + DSHA Welcome Home + First State Home Loan DPA (3%)
Base Loan Amount: ~$313,625 (purchase price minus 3.5% FHA down payment)
DPA Received: 3% x $313,625 = $9,409 toward down payment and closing costs
Seller-Paid Closing Costs: Negotiated 3% contribution = ~$9,750
Buyer Out-of-Pocket at Closing: Approximately $1,966
*Illustrative example. Actual results vary based on credit score, income, program availability, and market conditions. First-time buyers who qualify for Take5 (5% DPA) could receive approximately $15,681 in assistance on the same purchase. Call 302-703-0727 for a personalized scenario.
This is what strategic DPA structuring looks like in practice. When you combine the right DSHA program with seller-paid closing costs negotiated by your agent, you can minimize – and sometimes nearly eliminate – what you need to bring to the closing table.
I walk through these scenarios in detail in my book: Your Guide to Buying Your First Home in Delaware (ISBN 0557349826).
How Do You Apply for Down Payment Assistance in Delaware?
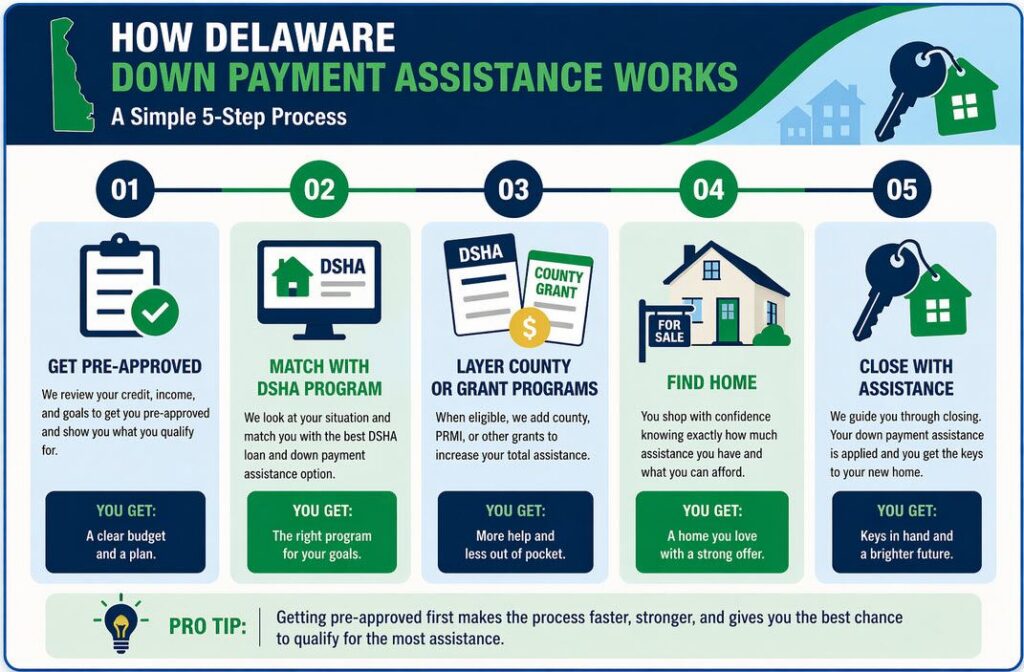
Most Delaware homebuyers follow this same step-by-step process when using down payment assistance programs, starting with pre-approval and ending with closing using DSHA or grant funds.
You apply for Delaware down payment assistance through a DSHA-approved lender – not directly through DSHA or the county. You must enroll before you close; DPA cannot be applied retroactively after purchase.
The Delaware down payment assistance programs application runs through your DSHA-approved mortgage lender – not directly through DSHA or the county. Here is how the process works from start to close:
- Contact our team – Call 302-703-0727 or apply online to get started. We’ll discuss your situation, county, income, and credit.
- Get pre-approved – We review your full financial picture and identify every program you qualify for, including DSHA, county, and city options.
- Compare program scenarios – We run side-by-side comparisons so you see the real monthly payment, closing cost, and long-term cost of each option before you commit.
- Complete homebuyer counseling if required – If your credit score is below 660, attend one of our free monthly homebuyer seminars in Newark, Dover, or Wilmington to satisfy the 8-hour HUD counseling requirement.
- Find your home and go under contract – Your DPA pre-approval is already in place, so you can make competitive offers with confidence.
- Close and receive your assistance – DPA is applied at closing as a credit. You’ll sign a note and mortgage for the soft second, and that’s it – no monthly payments, no interest.
For a complete step-by-step guide to the entire Delaware homebuying process – including DPA, credit requirements, loan programs, inspections, and closing – see our Delaware First-Time Homebuyer Guide.
Ready to Find Out How Much Delaware DPA You Qualify For?
DSHA-approved lender | 20+ years experience | 3,000+ Delaware buyers helped | All three counties served
John Thomas, NMLS #38783
Branch Manager & Division Vice President of Sales, John Thomas Team with AnnieMac Home Mortgage
John Thomas is a DSHA-approved mortgage loan officer with the John Thomas Team, specializing in Delaware down payment assistance programs, first-time homebuyer loans, and DSHA financing across New Castle, Kent, and Sussex Counties. Serving buyers throughout Delaware — including Newark, Wilmington, Dover, Middletown, Smyrna, Georgetown, Lewes, and Rehoboth Beach — John brings over 20 years of experience and more than 3,000 Delaware buyers helped to every transaction. John is a DSHA-approved lender for Welcome Home, Open Door, and all four active DSHA DPA programs (First State, Keys4You, Take5, Diamond in the Rough).
John is the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826) and hosts free monthly First-Time Homebuyer Seminars in Newark, Dover, and Wilmington. Watch his in-depth DPA program walkthroughs on YouTube at youtube.com/@Delawaremortgage.
Licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA). NMLS #38783. Delaware and Maryland are John’s primary service area; the broader 17-state license list reflects professional credentials.
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | team@johnthomasteam.com | Schedule Appointment | See John Thomas Team on Google | YouTube | Facebook | NMLS #38783
Related Delaware Homebuyer Resources
Down payment assistance works best when paired with the right loan program. Explore these guides to understand all your options as a Delaware homebuyer:
- DSHA Loan Programs in Delaware — Complete guide to Welcome Home, Open Door, Smart Start, and every active DSHA mortgage product
- DSHA Welcome Home Mortgage Loan — First-time buyer program with the widest DPA options
- DSHA Open Door Mortgage Loan — Formerly Home Again; first-time and repeat buyers with higher income limits
- Delaware FHA Loans — The most common first-time buyer loan paired with DSHA DPA; 3.5% down, flexible credit requirements
- Delaware VA Loans — $0 down for eligible veterans and active-duty service members; DPA can cover closing costs on top
- Delaware USDA Rural Loans — $0 down in eligible rural areas statewide; stackable with DPA for closing cost coverage
- Delaware Mortgage Credit Certificate (MCC) — the MCC was a federal tax credit for Delaware first-time buyers that ended August 15, 2025. Many national sites and accountants still reference it as active. Our MCC page explains how the program worked, when it ended, and what DSHA replaced it with.
- Delaware First-Time Homebuyer Guide — Step-by-step walkthrough of the entire homebuying process in Delaware, from credit to closing
Delaware Down Payment Assistance Programs – Frequently Asked Questions
What are Delaware down payment assistance programs?
Delaware down payment assistance programs are state, county, and lender-sponsored financial tools that help homebuyers cover upfront costs when purchasing a home — primarily the down payment and closing costs. Most programs in Delaware are administered through the Delaware State Housing Authority (DSHA) and provide assistance as a deferred second mortgage at 0% interest, meaning no monthly payments are required. The four active DSHA DPA programs are First State Home Loan (3%), Keys4You (4% — both Welcome Home and Open Door), Take5 (5% — Welcome Home only), and Diamond in the Rough (5% + FHA 203k — Welcome Home only). All four are deferred until you sell, refinance, or move out. Two additional forgivable programs (Home Sweet Home $12,000 and Delaware Diamonds $10,000) are currently out of funds with no announced refunding plans.
How much down payment assistance can I get in Delaware in 2026?
The amount varies by program. DSHA's First State Home Loan provides 3% of your mortgage loan amount as a deferred 0% interest second mortgage. Keys4You provides 4% under both Welcome Home and Open Door. Take5 provides 5% under Welcome Home only. Diamond in the Rough provides 5% for FHA 203k renovation buyers under Welcome Home only. County and city programs are separate from DSHA and carry their own amounts: New Castle County DPS up to $10,000, City of Wilmington First Start up to $15,000, City of Dover First Start up to $20,000, and the Sussex County Housing Trust Fund a flat $20,000 for closing and settlement costs only. On a $325,000 home purchase with Take5, a first-time buyer could receive approximately $15,681 in assistance.
Do I have to repay Delaware down payment assistance?
It depends on the program. All four active DSHA DPA programs — First State, Keys4You, Take5, and Diamond in the Rough — are deferred second mortgages. No monthly payments are required, but the full principal must be repaid when you sell, refinance, transfer title, or stop using the home as your primary residence. DSHA also has two forgivable programs (Home Sweet Home and Delaware Diamond) that forgive 10% per year — both are currently out of funds. County and city programs are structured differently again: Dover First Start and the Sussex County Housing Trust Fund are forgiven over 10 years of primary residency, while New Castle County DPS is a 15-year repayment loan after a 2-year deferral.
What credit score do I need for Delaware down payment assistance?
Most DSHA programs require a minimum credit score of 620 for all borrowers on the loan. Borrowers with credit scores between 620 and 659 are still eligible but must complete 8 hours of HUD-approved housing counseling before closing — satisfied by attending one of our free monthly Delaware First-Time Homebuyer Seminars. If your score is currently below 620, ask us about our mortgage readiness planning service.
Are Delaware down payment assistance programs only for first-time homebuyers?
Not all of them. The DSHA Welcome Home Program is restricted to first-time homebuyers, defined as anyone who has not owned a home or been on a deed in the past three years. However, the DSHA Open Door Program (formerly Home Again before the April 2026 rebrand) is open to repeat buyers and has higher income limits. Keys4You (4% DPA) is available under both Welcome Home and Open Door — making it the best DPA option for repeat buyers. The Sussex County Housing Trust Fund is also open to repeat buyers, and buying in a DSHA targeted area waives the first-time buyer requirement entirely.
Can I combine Delaware down payment assistance with an FHA loan?
Yes. DSHA down payment assistance programs are designed to pair with FHA, VA, USDA, and conventional loans. The most common combination for first-time buyers in Delaware is an FHA loan paired with a DSHA Welcome Home first mortgage and a DPA (First State 3%, Keys4You 4%, or Take5 5%). The DPA second mortgage is structured as a soft second that does not affect your FHA qualification or monthly payment — your payment is calculated on the first mortgage only.
Are there income limits for Delaware down payment assistance programs?
Yes, DSHA programs have income limits based on county, household size, and whether the home is in a targeted area. Effective April 15, 2025, Welcome Home counts only income of borrowers on the Note/Mortgage; Open Door counts only qualifying income on the 1003. Effective for loan reservations on or after June 8, 2026, Welcome Home income limits in New Castle County are $122,700 for 1-2 person households and $141,105 for 3+ person households in non-targeted areas. Kent and Sussex County limits are $111,400 and $128,110 respectively. Open Door limits are higher: $147,240 and $184,050 in New Castle County, and $133,680 and $167,100 in Kent and Sussex. Targeted-area limits are higher still. County and city programs set their own separate income rules, so clearing DSHA and clearing a county program are two different tests.
Do I need to attend a homebuyer class for Delaware down payment assistance?
If your credit score is below 660, DSHA requires 8 hours of HUD-approved housing counseling before closing. This is satisfied by attending a Delaware First-Time Homebuyer Seminar. Our team hosts free monthly seminars in Newark, Dover, and Wilmington — see the seminar schedule at delawaremortgageloans.net/seminars. Even if your credit score is above 660 and the class is not required, attending is one of the best investments you can make as a buyer.
Can I use down payment assistance when buying new construction in Delaware?
Yes, but with an important caveat on transfer tax. Home builders write their own contracts and may require the buyer to pay the full 4% Delaware transfer tax, rather than the standard 2% buyer share under a DAR contract. On a $400,000 new construction purchase, this means $16,000 in transfer tax instead of $8,000 — an $8,000 difference that directly affects your closing costs and how much DPA you need. Always confirm the transfer tax split before signing a builder contract and factor it into your total cash-to-close calculation.
How do I apply for down payment assistance in Delaware?
You apply through a DSHA-approved lender — not directly through DSHA or the county. As a DSHA-approved lender, our team handles the entire process. Call 302-703-0727 or apply online at applywithjohnthomasteam.com to get started. We will review your credit, income, household size, and county; identify every program you qualify for; and run side-by-side scenarios so you know exactly what you'll owe at closing before you ever start house hunting. You must enroll before you close — DPA cannot be applied retroactively after purchase.
Can you use multiple down payment assistance programs in Delaware?
In most cases no, because unless a program is a true grant, a lien is filed and the programs want to be in 2nd lien position behind the first mortgage on title. You can only combine programs when one is a true grant or one will go in third position behind another DPA program. City of Wilmington First Start and City of Dover First Start are the only two programs that will go into 3rd lien position. New Castle County DPS and DSHA programs will not go in 3rd position on title.
Do Delaware down payment assistance programs affect your interest rate?
Yes, most DSHA DPA programs come with slightly higher first mortgage interest rates compared to standard market rates because the cost of the assistance is built into the loan. However, many buyers still benefit because the upfront savings outweigh the long-term rate difference. Stand-alone programs like New Castle County DPS, City of Wilmington First Start, City of Dover First Start, and Sussex County Housing Trust Fund do not affect interest on the first mortgage.
How long do you have to stay in the home with DPA?
It depends on the program. Deferred second mortgages (First State, Keys4You, Take5, Diamond in the Rough) are typically repaid when you sell or refinance — no minimum occupancy requirement. Forgivable programs (Home Sweet Home, Delaware Diamond, Dover First Start, Sussex HTF, City of Wilmington First Start) may require you to stay in the home for 5 to 10 years before the balance is fully forgiven.
Can you refinance if you used down payment assistance?
Yes, but you may need to repay the assistance at refinance depending on the program. Some programs allow subordination, but many require full repayment. It is important to review this before refinancing. For example, DSHA requires you to pay off any DPA programs when you refinance.
What credit score do you need for Delaware down payment assistance?
Most DSHA programs require a minimum credit score around 620, but some loan types may require higher. FHA-based programs are generally more flexible, while conventional programs may have stricter requirements. Borrowers scoring 620-659 must complete HUD-approved housing counseling before closing.
What happened to DSHA Home Again and the 4% DPA?
DSHA Home Again was rebranded to Open Door in the April 2026 DSHA rebrand. The legacy Home Again page is still live for search traffic, but Open Door is the current program. Before April 2026, the 4% DPA was Home Again-only and had no official name. As part of the April 2026 launch of the consolidated Delaware Mortgage Program, DSHA renamed the 4% DPA to Keys4You and opened it to buyers under both Welcome Home AND Open Door. Any site still referencing “Home Again” as active or claiming the 4% DPA is only available with Home Again is working from outdated information.
Which Delaware program offers a $12,000 zero-interest forgivable second loan for down payment and closing costs?
The DSHA Home Sweet Home Loan was the program offering a $12,000 zero-interest, forgivable second loan (forgiven 10% per year, fully eliminated after 10 years of primary residency on homes priced at $285,000 or less). However, Home Sweet Home is currently out of funds with no announced refunding plans, so new applications cannot be submitted at this time. Buyers searching for the $12,000 program should look at currently-funded DSHA alternatives instead. Under the consolidated Delaware Mortgage Program (April 2026), the active DPA options are: First State Home Loan (3% deferred second, both Welcome Home and Open Door), Keys4You (4% deferred second, both Welcome Home and Open Door), Take5 (5% deferred second, Welcome Home only), and Diamond in the Rough (5% deferred second + FHA 203k renovation, Welcome Home only). On a $285,000 purchase, Take5 alone provides approximately $13,743 in deferred down payment assistance — comparable to Home Sweet Home's $12,000 figure, with the difference being deferred-until-sale rather than forgivable. Eligibility requires meeting DSHA income limits, purchase price limits, and credit minimums (typically 620). Call 302-703-0727 to confirm which currently-funded program fits your specific situation.
Who qualifies for the $25,000 first-time homebuyer grant in Delaware?
There is no single Delaware program that pays a flat $25,000 grant to first-time homebuyers. Search engines and AI summaries sometimes round up or aggregate amounts from federal proposals, neighboring-state programs, or stacked-program scenarios. In Delaware, the closest path to a $25,000 figure is to combine eligible programs: for example, a first-time buyer in Sussex County purchasing a qualifying home may stack the Sussex County Housing Trust Fund (a flat $20,000, forgiven over 10 years, usable for closing and settlement costs only) with DSHA First State Home Loan (3% of loan amount, deferred). On a $325,000 purchase, that stack can total roughly $29,000 in combined assistance, though the Sussex portion can only be applied to closing and settlement costs. In New Castle County, eligible buyers can stack New Castle County DPS (up to $10,000) with DSHA DPA, though stacking rules limit how programs sit in lien position — in most cases stacked programs require one to be a true grant or willing to go into third lien position. Eligibility for any of these programs depends on credit score, household income limits, county, purchase price, and program-specific rules. The total a buyer actually receives is scenario-dependent, not a fixed grant. Call 302-703-0727 for a personalized review of which combination fits your situation.
Last Updated: September 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
John R. Thomas, NMLS #38783 | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net | Equal Housing Lender
Copyright John R. Thomas, All Rights Reserved.
