
Delaware FHA 203k Loans 2026: Buy and Renovate With One Mortgage
What is a Delaware FHA 203k loan? A Delaware FHA 203k loan is a government-backed renovation mortgage, insured by the Federal Housing Administration, that lets a Delaware buyer or homeowner finance the purchase or refinance of a primary residence plus eligible repair costs into one loan with just 3.5% down. The Limited 203k covers up to $75,000 in non-structural repairs (raised from $35,000 in November 2024). The Standard 203k handles major structural rehab up to your county FHA loan limit – $630,200 in New Castle County and $541,287 in Kent and Sussex counties for 2026. The Standard 203k requires a minimum of $5,000 in eligible rehabilitation costs; the Limited 203k has no minimum repair amount.
If you’ve ever found a Delaware home that’s “almost perfect” except for the kitchen, the roof, or the HVAC system that’s clearly on its last leg – and walked away because you didn’t have the cash to fix it after closing – the FHA 203k is the loan you didn’t know existed. I’m John Thomas, NMLS #38783, and over the last 20+ years I’ve closed FHA 203k loans for Delaware buyers in every situation you can imagine: bank-owned properties in Wilmington, fixer-uppers in Dover, older homes in Sussex County that needed a fresh kitchen and bath. The 203k folds the purchase price and the renovation budget into one FHA mortgage at one rate with one closing – and the work happens after you own the home, paid out to your contractor through an escrow account as the project progresses.
This guide covers everything you need to know about the FHA 203k in Delaware in 2026: how Limited and Standard 203k differ, what repairs qualify, the 2026 FHA county loan limits, the step-by-step process, and how to apply for a Delaware FHA 203k loan with John Thomas, NMLS #38783. We’ll also cover what documents you’ll need, when to involve a contractor, and how to combine your 203k with DSHA’s Diamond in the Rough down payment assistance program. If you’d rather just talk it through, call me directly at 302-703-0727.
Is an FHA 203k the Right Loan for You? Quick Self-Check
If you can answer “yes” to most of these, the FHA 203k is probably worth a 15-minute consultation:
- Are you buying a home that’s at least one year old?
- Will the home be your primary residence (1-to-4 units, you live in one)?
- Do you have a 620+ FICO credit score (or close to it)?
- Are your planned repairs cosmetic/non-structural (Limited 203k, up to $75,000) or structural/major (Standard 203k)?
- Is your repair budget at least $5,000? (Required for Standard 203k – the Limited 203k has no minimum.)
- Could you benefit from DSHA down payment assistance as a Delaware first-time buyer?
Not sure on any of these? That’s exactly what a 15-minute consultation is for. Use the buttons below.
Ready to Buy and Renovate With One FHA 203k Loan?
Get your FHA 203k pre-approval started today – Limited 203k or Standard 203k, we structure both.
Call 302-703-0727 Schedule Appointment Apply Online Now
Equal Housing Lender FHA Approved DSHA Approved NMLS #38783
Table of Contents
What Is a Delaware FHA 203k Rehab Loan?
The FHA 203k is a government-insured renovation mortgage that combines two things into one loan: the money to buy the home and the money to fix it up. Instead of getting a regular mortgage to close, then trying to find a separate construction loan or running up credit cards to pay for repairs, you do it all in one transaction. The loan is based on the after-repair value of the property – meaning the appraiser values the home as if the repairs were already done, which is what gives you the borrowing capacity to fund both the purchase and the rehab.
You can use a Delaware FHA 203k loan to purchase a home that needs work, or to refinance your current home and roll the renovation costs into the new mortgage. The property has to be your primary residence – 1-to-4 unit owner-occupied – and you have to live in one of the units for at least one year. It works in all three Delaware counties: New Castle, Kent, and Sussex.
Limited 203k vs Standard 203k: Which Version Do You Need?
There are two versions of the FHA 203k loan, and most Delaware buyers will fit one or the other clearly. The Limited 203k (formerly called the Streamline 203k – that name was retired years ago) is for cosmetic and non-structural repairs up to $75,000. The Standard 203k is for major rehab – structural changes, additions, foundation work – and it doesn’t have a per-project cap on repair costs other than the FHA county loan limit.
The big change to know about: in November 2024, HUD raised the Limited 203k cap from $35,000 to $75,000 (HUD Mortgagee Letter 2024-13) and extended the rehab completion window. That single change made the Limited 203k usable for projects that would previously have forced you into the more complex Standard version. Here’s how the two compare side-by-side:
The floor matters as much as the ceiling, and almost nobody explains it. The Standard 203k requires a minimum of $5,000 in eligible rehabilitation costs – that is HUD’s threshold, not a lender overlay. The Limited 203k has no minimum at all. I see the practical version of this a few times a year: a Delaware buyer arrives with a $3,500 repair list convinced they need a Standard 203k, and the Standard simply is not available to them at that scope. The Limited is – and in most of those files it was the better fit anyway, because a repair list that small is rarely structural.
| Feature | Limited 203k | Standard 203k |
|---|---|---|
| Minimum repair amount | None – no minimum repair amount | $5,000 in eligible rehabilitation costs |
| Maximum repair amount | $75,000 (raised from $35,000 in Nov 2024) | No cap – limited only by FHA county loan limit |
| Structural repairs allowed? | No – non-structural / cosmetic only | Yes – structural, additions, major rehab |
| HUD Consultant required? | Optional – and consultant fee can now be financed into the loan (HUD ML 2024-13) | Yes – required on every Standard 203k |
| Time to complete repairs | Up to 9 months (extended from 6 in 2024) | Up to 12 months (extended from 6 in 2024) |
| Number of contractor draws | Up to 2 draws (50% upfront / 50% on completion) | Up to 5 draws based on inspection schedule |
| Down payment | 3.5% (FHA standard) | 3.5% (FHA standard) |
| Minimum credit score | 620 FICO | 620 FICO |
| Best for | Kitchen/bath remodels, roof, HVAC, flooring, paint, windows | Additions, structural changes, foundation work, gut rehabs |
How Much Can I Borrow on a Delaware FHA 203k Loan?
The maximum FHA 203k loan amount is calculated by taking the purchase price plus the rehab budget, and then taking 96.5% of that combined total. Here’s a real example:
Example FHA 203k Maximum Loan Calculation
Purchase Price: $200,000
Total Rehab Loan Amount: $50,000
Combined Total: $250,000
Maximum Loan Amount: $250,000 x 96.5% = $241,250
Down payment required: $8,750 (3.5%)
You’re capped two ways. First, by the maximum Delaware FHA loan limit for the county where the property sits. Second, by the after-repair value (ARV) of the home as determined by the FHA 203k appraisal – you can borrow up to 110% of ARV. Whichever cap you hit first is your ceiling.
2026 Delaware FHA 203k Loan Limits by County
The 2026 FHA loan limits dictate how much total mortgage you can carry – purchase plus rehab combined – on an FHA 203k in Delaware:
| Delaware County | 2026 FHA Loan Limit (1-Unit) | 2026 FHA Loan Limit (2-Unit) |
|---|---|---|
| New Castle County | $630,200 | $806,750 |
| Kent County | $541,287 | $693,050 |
| Sussex County | $541,287 | $693,050 |
2026 FHA loan limits effective January 1, 2026. Source: HUD FHA Mortgage Limits lookup.
What Repairs Are Eligible Under an FHA 203k Loan?
This is the part that surprises most Delaware buyers – the FHA 203k covers a much wider range of work than you’d think, especially for the Limited version, which is what 90% of my borrowers end up using.
Limited 203k Eligible Repairs (up to $75,000)
- Roofs, gutters, and downspouts
- Plumbing and electrical systems
- HVAC systems (heating, ventilation, and air conditioning)
- Kitchen and bath remodels (non-structural)
- New windows and doors
- Interior and exterior painting
- Flooring (carpet, hardwood, tile, vinyl)
- Weather stripping and insulation
- Energy-efficient improvements
- Stabilizing or removing lead-based paint
- Decks, patios, and porches
- Finishing basements (non-structural)
- Septic or well systems
- New kitchen appliances and washer/dryer
- Accessibility improvements for persons with disabilities
Standard 203k Eligible Repairs (no cap, structural OK)
- Structural alterations and reconstruction
- Room additions and second-story additions
- Foundation repair and replacement
- Modernization that improves the home’s function
- Elimination of health and safety hazards
- Major plumbing reconditioning or replacement
- Installing a new well and/or septic system
- Adding or fully replacing roofing and structural roof systems
- Major landscape work and site improvements
- Conversion of a property to a 1-to-4 unit structure
- Repairs to swimming pools that present health/safety hazards
- Energy conservation improvements
Can You Use an FHA 203k to Make Upgrades on an Older Home?
Yes – and this is the most common misconception about renovation loans. The 203k isn’t only for run-down, dilapidated, or distressed properties. Plenty of my Delaware buyers use the Limited 203k to update an older home that’s perfectly livable but needs cosmetic work – a kitchen that hasn’t been touched since 1985, hardwood floors hidden under three layers of carpet, an HVAC system that’s working but ten years past its rated life. The 203k lets you finance those upgrades into the mortgage instead of cobbling them together with home improvement store credit cards at 18% interest.
Real Delaware Borrower Scenario: With and Without an FHA 203k
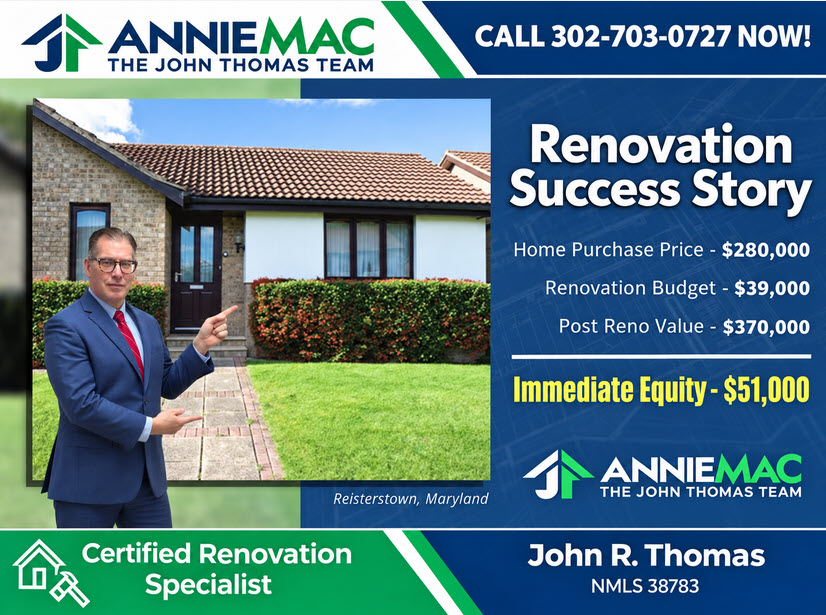
Here’s why running the math matters. Take a real example of a Delaware buyer looking at a $200,000 home that needs about $30,000 in repairs (kitchen, bath, paint, flooring) to be livable the way they want it.
? Option A – Standard FHA Loan (NO renovation financing)
Purchase only – FHA 203(b) at 96.5% LTV
Loan amount: $193,000
Cash to close: $7,000
+ $30,000 repair work paid out-of-pocket after closing
Total cash needed: $37,000
? Option B – FHA 203k Renovation Loan
Purchase + repairs combined ($230,000) at 96.5% LTV
Loan amount: $221,950
Cash to close: $8,150
$30,000 repair work financed into the mortgage
Total cash needed: $8,150
How Does the FHA 203k Process Work Step by Step?
The 203k process has more moving parts than a standard FHA loan, but it’s predictable when you work with a lender who closes them regularly. Here’s how I walk Delaware buyers through it:
- Pre-approval. We review your credit, income, and goals to estimate your borrowing capacity based on the home’s projected after-repair value, and confirm whether you fit Limited or Standard 203k.
- Find a property. The home must be 1-to-4 units, at least one year old, and your primary residence. Bank-owned properties, short sales, and older homes that need work are all great fits.
- Write the offer. Your purchase contract should include a contingency that the deal is subject to FHA 203k approval and the buyer’s acceptance of any required improvements determined by HUD or the lender.
- Get contractor bids. You hire a licensed contractor (or contractors) to provide itemized written bids for the work. For a Standard 203k, a HUD-approved 203k Consultant prepares the work write-up and cost estimate. For a Limited 203k, the consultant is now optional and the consultant fee can be financed into the loan.
- FHA 203k appraisal. The appraiser values the home as-is and after the proposed repairs. The after-repair value is what supports your loan amount.
- Underwriting and closing. Lender processes the file, underwrites the loan, and closes the transaction. The repair funds go into a rehabilitation escrow account at the lender – they aren’t paid to the contractor at closing.
- Construction begins. The contractor pulls permits and starts work. Limited 203k projects must complete within 9 months; Standard 203k projects within 12 months.
- Draws and inspections. The contractor is paid in stages from the escrow account as work is verified by inspections. Limited 203k allows up to 2 draws; Standard 203k allows up to 5.
- Final inspection and completion. Once all work is done according to the approved scope, a final inspection releases the last draw (minus a 10% holdback). Any unused contingency funds are applied to your loan principal.
Pair Your FHA 203k Limited With DSHA Diamond in the Rough Down Payment Assistance
This is the Delaware-specific angle that most renovation lenders never mention. The Delaware State Housing Authority’s Diamond in the Rough program pairs an FHA 203k Limited renovation loan with 5% down payment and closing cost assistance – a no-interest second mortgage you don’t repay until you sell, refinance, or move out. So if you’re a first-time buyer looking at a fixer-upper in Delaware and you qualify for DSHA, you can finance the purchase, finance up to $75,000 in renovations, and finance the down payment – all in one structured deal. Minimum credit score is 640.
Diamond in the Rough is offered exclusively under the DSHA Welcome Home first-time buyer track. If you do not need the down payment assistance, DSHA Smart Start is the unassisted Welcome Home first mortgage and carries the lowest DSHA rate in the track, though it cannot be combined with 203k renovation financing. Two important limitations: (1) Because it uses FHA 203k Limited, repairs must be non-structural – if your project is structural or above the $75,000 Limited 203k cap, we’ll review whether a Standard 203k or another renovation loan is a better fit. (2) Diamond in the Rough does NOT allow manufactured homes. If you’d like DPA help on a Limited 203k for a different scenario, ask about pairing with the DSHA Keys4You 4% DPA or the First State 3% DPA.
What Are the FHA 203k Qualification Requirements?
- Minimum 620 FICO credit score (some scenarios may go lower with compensating factors)
- 3.5% down payment on the total loan amount (purchase + repairs combined)
- Primary residence only – you must occupy as your primary home for at least 1 year
- 1-to-4 unit owner-occupied properties qualify (you live in one unit; the rest can be rented)
- All work must be completed by a licensed contractor – you cannot do the work yourself unless you’re a licensed general contractor (and even then, only materials are reimbursable, not labor)
- 2-year wait period from a Chapter 7 bankruptcy discharge
- 3-year wait period from a foreclosure or short sale
- FHA mortgage insurance applies – 1.75% upfront MIP plus monthly MIP for the life of the loan in most cases
Common Mistakes Delaware Buyers Make on FHA 203k Loans
- Picking a contractor before getting pre-approved. Get the loan structure first – your contractor selection has to fit the lender’s licensing and experience requirements.
- Underestimating the contingency reserve. A 203k requires a 10-20% contingency built into the rehab budget. Plan for it, don’t pretend it doesn’t exist.
- Trying to do work themselves to save money. Self-help labor is allowed in narrow circumstances on a Standard 203k, but only if you’re a licensed GC, and you can only be reimbursed for materials. Plan to use a licensed contractor.
- Choosing a lender who doesn’t close 203k loans regularly. Most lenders advertise the 203k. Few actually close them. The 203k has more moving parts than any other FHA loan, and an inexperienced lender can derail your contract.
- Overpaying for the home assuming the after-repair value will support it. The Limited 203k now requires both an “as-is” and “after-repair” appraisal. If you offer more than the as-is value of the home, the difference comes out of your pocket as additional down payment.
- Forgetting about the 2026 transfer tax. Delaware’s standard real estate contract splits the 4% state and county transfer tax 2% buyer / 2% seller. Watch out on new construction – many Delaware home builders write contracts that require the buyer to pay the full 4%. Read every contract before you sign.
Delaware FHA 203k Loans by County
The John Thomas Team closes FHA 203k loans across all three Delaware counties from our office at 248 E Chestnut Hill Rd in Newark. The 2026 FHA loan limits above apply per county and reflect the maximum combined purchase price plus rehab budget.
New Castle County FHA 203k
Strong fit for older homes that need roof, HVAC, kitchen, bath, or safety repairs. Common cities we serve:
Wilmington · Newark · Bear · New Castle · Claymont · Middletown
Kent County FHA 203k
Useful for buyers looking at homes that need repairs but offer long-term value at lower price points. Common cities we serve:
Dover · Smyrna · Camden · Harrington · Milford
Sussex County FHA 203k
Works well for older homes that may need septic, well, window, or accessibility improvements. Common cities we serve:
Georgetown · Millsboro · Lewes · Seaford · Laurel
How to Apply for a Delaware FHA 203k Loan
Quick Answer: To apply for a Delaware FHA 203k loan, contact an FHA-approved lender experienced with 203k renovation loans, get pre-approved, choose a Limited or Standard 203k, gather contractor estimates, complete the loan application, and have the property appraised based on its after-repair value. John Thomas, NMLS #38783, helps Delaware buyers and homeowners review FHA 203k options for both purchase and refinance.
Applying for an FHA 203k starts with finding a lender who actually closes them – not just any FHA-approved lender. The 203k has more moving parts than a regular FHA loan: contractor bids, renovation escrow, FHA 203k appraisal rules, and draw inspections. An inexperienced lender can derail your contract. Here’s the application path I walk Delaware buyers through:
- Step 1: Schedule a Delaware FHA 203k review. Start by speaking with a lender who closes FHA 203k loans regularly. We’ll review your situation in 15 minutes and tell you whether the 203k makes sense for your purchase, refinance, or renovation project. Schedule your Delaware FHA 203k review or call 302-703-0727.
- Step 2: Review credit, income, and down payment. Your lender will pull credit, review pay stubs and tax returns, calculate your debt-to-income ratio, and verify your down payment funds. FHA 203k generally allows 3.5% down with a 620 minimum FICO, but full approval depends on your complete profile.
- Step 3: Choose Limited 203k or Standard 203k. Limited 203k covers non-structural repairs up to $75,000 – kitchens, baths, roof, HVAC, flooring, paint, windows. Standard 203k covers structural rehab, additions, and major projects with no per-job repair cap (other than your county FHA limit). We’ll walk through the repair list with you so you understand which version fits.
- Step 4: Find an eligible Delaware property. The home must be your primary residence (1-to-4 units), at least one year old, and meet FHA 203k property rules. The 203k can be used to purchase a fixer-upper or to refinance a home you already own and finance the improvements.
- Step 5: Get contractor estimates. You’ll need written, itemized contractor estimates for all the work. Standard 203k loans require a HUD-approved 203k Consultant to prepare the work write-up; Limited 203k loans don’t require a consultant, and the consultant fee can be financed if you choose to use one.
- Step 6: Complete the FHA 203k loan application. Once your structure is clear, you’ll complete the full mortgage application and provide income, asset, credit, and property documents. The lender reviews both your borrower qualifications and the renovation plan together.
- Step 7: Order the FHA 203k appraisal. The appraiser values the home twice: as-is and after the proposed repairs are complete. The after-repair value (ARV) is what supports your loan amount – you can borrow up to 110% of ARV.
- Step 8: Close the loan and begin renovations. At closing, the repair funds go into a rehabilitation escrow account at the lender. The contractor is paid in stages (draws) as inspections verify the work is complete. You don’t receive the repair money directly – that’s by FHA design, to protect you.
Documents you’ll typically need to apply: 30 days of pay stubs, two years of W-2s and federal tax returns, two months of bank statements, photo ID, the sales contract (for purchases) or current mortgage statement (for refinances), and contractor estimates. Self-employed borrowers will also need YTD profit-and-loss statements and business tax returns. Standard 203k borrowers will additionally need a HUD-approved 203k Consultant work write-up. We’ll send you a complete document checklist tailored to your specific situation after Step 1.
Ready to apply? Schedule a Delaware FHA 203k review with John Thomas, NMLS #38783. We’ll walk through your purchase, refinance, repair budget, and down payment assistance options step-by-step.
FHA 203k vs HomeStyle vs VA Renovation: Which Renovation Loan Is Right?
The FHA 203k isn’t the only renovation loan in Delaware. Depending on your credit, eligibility, and the property type, one of these alternatives may be a better fit:
- Conventional HomeStyle Renovation Loan – better for buyers with 660+ credit. Works on primary residences, second homes, AND investment properties. No repair cap other than the conforming loan limit. Often a better fit than FHA 203k for stronger borrowers.
- VA Renovation Loan – for eligible veterans. Zero down payment, no mortgage insurance, finances purchase + up to $50,000 in repairs.
- Renovation Lending Guide – full comparison of all renovation loan options.
- FHA Title 1 Property Improvement Loan – for current homeowners who only need to finance repairs (not buy or refinance). The Title 1 is an alternative HUD program for smaller improvement projects when you don’t need a full 203k transaction. We can help you compare whether Title 1 or a Limited 203k refinance fits your scenario better.
If you’re a Delaware first-time buyer comparing the 203k to your other low-down-payment options, the Delaware First Time Home Buyers Guide walks through every program side-by-side, and the Delaware Down Payment Assistance Programs guide covers the DPA programs that can pair with renovation loans.
FAQ – Delaware FHA 203k Loans
What is the maximum repair amount on a Delaware FHA 203k loan?
The Limited 203k allows up to $75,000 in repair costs as of November 4, 2024 (raised from $35,000 by HUD Mortgagee Letter 2024-13). The Standard 203k has no per-project cap on repairs – you’re limited only by your county’s FHA loan limit. For 2026 in Delaware, that’s $630,200 in New Castle County and $541,287 in Kent and Sussex counties for a single-family home. The total of your purchase price plus rehab budget combined cannot exceed the FHA county limit.
What is the minimum repair amount on an FHA 203k loan?
The FHA Standard 203k requires a minimum of $5,000 in eligible rehabilitation costs. The FHA Limited 203k has no minimum repair amount, so it works for projects well under $5,000 all the way up to the $75,000 Limited cap. In practice, most Delaware buyers whose repair list comes in under $5,000 end up using the Limited 203k. If your scope sits near the $5,000 line and involves structural work, call John Thomas at 302-703-0727 to review which version of the 203k your project actually files under.
What credit score do I need to qualify for an FHA 203k in Delaware?
You need a minimum 620 FICO credit score to qualify for either the Limited 203k or the Standard 203k in Delaware. Some lenders set higher overlays. With compensating factors like strong reserves, low debt-to-income, or a substantial down payment above 3.5%, scores below 620 can sometimes be considered. Call John Thomas at 302-703-0727 to review your specific credit profile.
Can I do the renovation work myself on a 203k loan?
Generally no. FHA 203k loans require all repair and rehabilitation work to be completed by a licensed contractor who meets the lender’s licensing, insurance, and experience requirements. The only exception is on a Standard 203k where the borrower is a licensed general contractor approved by the lender – and even in that case, the borrower can only be reimbursed for materials, not for labor or time. Self-help is rarely worth pursuing because it slows the project and creates compliance risk.
How long do I have to complete the repairs on an FHA 203k?
As of November 2024, FHA extended the rehab completion window. Limited 203k projects must be completed within 9 months from closing (extended from 6 months). Standard 203k projects must be completed within 12 months from closing (extended from 6 months). Your lender may set tighter deadlines depending on the project scope and contractor capacity.
Can I use a Delaware FHA 203k loan to buy a foreclosure or bank-owned property?
Yes. FHA 203k Rehab Loans are an excellent tool for purchasing bank-owned (REO) properties, foreclosures, and short sales that need repairs. The 203k is one of the few loan products that lets you finance both the purchase and the renovation of a distressed property in a single transaction. Just remember the property still has to meet FHA’s basic safety, soundness, and security standards after the planned repairs are completed.
How does an FHA 203k loan pair with DSHA down payment assistance in Delaware?
DSHA’s Diamond in the Rough program pairs an FHA 203k Limited renovation loan with 5% down payment and closing cost assistance through the DSHA Welcome Home first mortgage. The Limited 203k allows up to $75,000 in non-structural repairs, and the 5% DPA is a no-interest second mortgage that doesn’t have to be repaid until you sell, refinance, or move out of the home. Minimum credit score is 640. Diamond in the Rough does not allow manufactured homes. If your project requires structural work or a Standard 203k, ask about other Delaware renovation financing options. For non-Diamond Limited 203k projects, you may also be able to layer DSHA Keys4You (4% DPA) or First State Home Loan (3% DPA) where eligible.
What’s the difference between a Limited 203k and a Standard 203k?
The Limited 203k (formerly called Streamline 203k) is for non-structural repairs up to $75,000 – kitchen and bath remodels, roofing, HVAC, flooring, paint, windows, energy-efficient upgrades. The Standard 203k is for major rehab including structural changes, additions, foundation work, and projects with no per-job repair cap. Standard 203k always requires a HUD-approved 203k Consultant; Limited 203k makes the consultant optional and now allows the consultant fee to be financed into the loan.
Are FHA 203k loans only for fixer-uppers, or can I use one on a livable older home?
You can absolutely use an FHA 203k on a livable older home that just needs updating. The 203k isn’t restricted to distressed properties. Many Delaware buyers use the Limited 203k to update an older home that’s perfectly habitable but needs a kitchen refresh, new flooring, new windows, or HVAC replacement. The 203k lets you finance those upgrades into your mortgage at FHA rates instead of putting them on credit cards or a separate home equity loan.
Can I use a Delaware FHA 203k loan on a condo or manufactured home?
Yes to both, with limits. For condos, the unit and the project must be FHA-approved, and 203k repairs are restricted to the interior of the unit (you can’t finance work on common-area roofs, exteriors, or shared systems). For manufactured homes, only the FHA 203k Limited is allowed and only for non-structural repairs – HUD permits manufactured homes titled as real estate where the rehab does not affect structural components. Note that DSHA Diamond in the Rough does NOT allow manufactured homes. Call John Thomas at 302-703-0727 to confirm whether your specific property qualifies.
How are contractors paid on a Delaware FHA 203k? What if repairs cost more than expected?
Contractors are paid through a rehabilitation escrow account held by the lender – not at closing, and not directly by the borrower. Funds are released in stages (called draws) as inspections verify the work is complete. Limited 203k allows up to 2 draws (typically 50% upfront and 50% on completion); Standard 203k allows up to 5 draws on a structured inspection schedule. FHA requires the project to start within 30 days of closing. Every 203k requires a 10-20% contingency reserve built into the rehab budget for unexpected costs. If the project goes over the contingency, you may need to bring additional borrower funds. If the contingency goes unused, the leftover money is applied to your loan principal, not refunded as cash.
How long does a Delaware FHA 203k take to close, and what are the closing costs?
Plan for 60 days or more, versus 30-45 days for a standard FHA loan. The 203k requires extra steps that a regular mortgage doesn’t: contractor bids, scope of work review, an FHA 203k appraisal that values the property based on after-repair value, escrow account setup, and (for Standard 203k) HUD-approved consultant coordination. Closing costs on an FHA 203k typically run 3-6% of the loan amount, similar to a standard FHA loan, plus a supplemental origination fee of about 1.5% specific to the 203k. The closing itself isn’t slower – it’s the front-end work that adds time. Working with a lender who closes 203k loans regularly is the single biggest factor in keeping your timeline on track. Most Delaware lenders advertise the 203k. Few actually close them.
How do I apply for an FHA 203k loan in Delaware?
You apply for an FHA 203k loan in Delaware through an FHA-approved mortgage lender that actively closes 203k renovation loans. The lender will review your credit, income, debts, down payment funds, property type, and repair plans to determine whether a Limited 203k or Standard 203k fits your situation. Most Delaware buyers start with a 15-minute pre-approval review, then find their property, gather contractor estimates, and complete the full loan application. John Thomas, NMLS #38783, helps Delaware buyers and homeowners compare Limited 203k and Standard 203k options before starting the formal application. Call 302-703-0727 or schedule online to start.
Who should I contact to apply for a Delaware FHA 203k loan?
Contact a mortgage lender who regularly closes FHA 203k renovation loans in Delaware – not just any FHA-approved lender. The 203k has more moving parts than a regular FHA loan: contractor bids, renovation escrow accounts, FHA 203k appraisal rules, draw inspections, and consultant requirements on Standard 203k. An inexperienced lender can derail your contract. John Thomas, NMLS #38783, is a Delaware FHA 203k specialist with 20+ years of mortgage lending experience and 1,000+ Delaware renovations funded across both Limited and Standard 203k. Call 302-703-0727 or visit delawaremortgageloans.net to get started.
Can I apply for an FHA 203k loan before choosing a contractor?
Yes – and in most cases, it’s the smart order. Speaking with your lender first lets you understand what type of contractor documentation is required, whether your project fits Limited or Standard 203k rules, what your maximum borrowing capacity is based on after-repair value, and how the repair budget affects your loan approval. Once you have that framework, you can search for contractors who fit the requirements (licensing, insurance, 203k experience) instead of picking one only to learn they don’t qualify. We typically recommend Step 1 (pre-approval review) before Step 5 (contractor estimates) for exactly this reason.
What documents do I need to apply for an FHA 203k loan in Delaware?
You typically need: 30 days of recent pay stubs; two years of W-2s and federal tax returns (last two filed years); two months of bank statements showing all asset accounts; photo ID and Social Security number authorization for credit; the sales contract (for purchases) or current mortgage statement and homeowner’s insurance declaration page (for refinances); and written contractor estimates with itemized scope of work. Self-employed borrowers also need year-to-date profit-and-loss statements and two years of business tax returns. Standard 203k applicants additionally need a HUD-approved 203k Consultant work write-up. Your lender will give you a complete document checklist tailored to your specific situation at the start of the application.

About the Author – John R. Thomas, NMLS #38783
Branch Manager & Division Vice President of Sales, John Thomas Team with AnnieMac Home Mortgage
John R. Thomas is Branch Manager and Division Vice President of Sales with the John Thomas Team with AnnieMac Home Mortgage in Newark, Delaware. With over 20 years of mortgage lending experience and 3,000+ Delaware buyers helped, John is a recognized FHA 203k specialist and DSHA-approved lender, closing both Limited and Standard 203k renovation loans across New Castle, Kent, and Sussex counties as well as Maryland. On 203k files specifically, the step John pushes hardest on is the contractor conversation before the offer goes in – in his experience most Delaware 203k deals that stall do so because the bids arrived after the contract was already signed. He is the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826).
John holds a Bachelor of Science in Physics Education from the University of Delaware and a Master of Science in Curriculum and Instruction from Delaware State University. He runs the monthly Delaware Home Buyer Seminar series and his YouTube channel publishes weekly Delaware mortgage education videos.
John Thomas Team with AnnieMac Home Mortgage
248 E Chestnut Hill Rd, Newark, DE 19713
Phone: 302-703-0727 | Email: team@johnthomasteam.com
See John Thomas Team on Google for reviews, directions, and local office information.
YouTube · Facebook · Instagram · TikTok · X / Twitter · LinkedIn
Licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA). NMLS #38783. The license list is a credential, not a service-area claim; day-to-day origination is Delaware and Maryland. Schedule Appointment | YouTube Channel
What Happens After You Contact Us?
No pressure, no surprises. Here’s the path from first call to pre-approval:
- We review your credit, income, and renovation goals on a 15-minute call.
- We estimate your purchase price + repair budget based on your county FHA limit.
- We confirm whether Limited 203k or Standard 203k fits your project.
- We tell you whether you also qualify for DSHA Diamond in the Rough or another DPA program.
- You decide if and when you want to move forward – no commitment, no pressure.
Get Your Delaware FHA 203k Pre-Approval Started
Whether it’s a $20,000 kitchen refresh or a $200,000 gut rehab, the John Thomas Team closes 203k loans that other lenders walk away from.
DSHA-approved. 20+ years of FHA 203k experience. Delaware and Maryland.
Call 302-703-0727 Schedule Appointment Apply Online Now
Equal Housing Lender FHA Approved DSHA Approved NMLS #38783
Last Updated: September 2026 · John Thomas Team with AnnieMac Home Mortgage · Mortgage content reviewed by John R. Thomas, NMLS #38783.
2026 FHA loan limits per HUD, effective for FHA case numbers assigned on or after January 1, 2026; multi-unit figures verified against the HUD FHA Mortgage Limits List (FHA Forward, CY2026, DE, last revised 01/01/2026) on September 14, 2026. FHA 203(k) Limited $75,000 rehabilitation cap per HUD Mortgagee Letter 2024-13.
John R. Thomas, NMLS #38783 | AnnieMac Home Mortgage NMLS #338923 | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
Copyright John R. Thomas, All Rights Reserved.
