
DSHA Delaware Diamonds DPA Program — $10,000 for Delaware Essential Workers (2026 Guide)

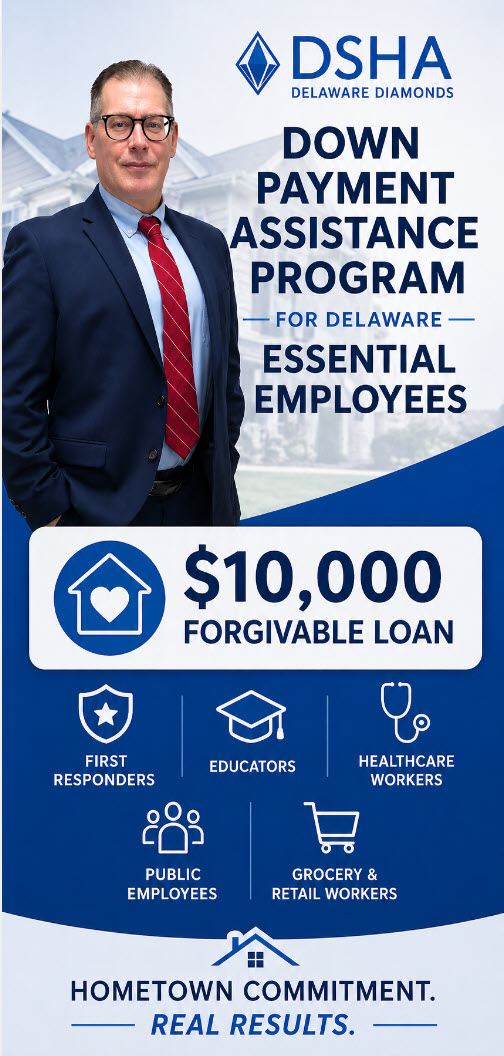
Quick Answer: The DSHA Delaware Diamonds Home Loan is a $10,000 zero-interest, forgivable second mortgage for Delaware essential workers — teachers, nurses, first responders, active-duty military, veterans, state employees, and qualifying grocery/retail workers. It pairs with a DSHA Welcome Home or Open Door first mortgage and is forgiven 10% per year over 10 years.
Funding Status — April 2026: The Delaware Diamonds program is currently out of funds. DSHA reloads the program when its bond funding cycle resets, and demand is high every time it does. If you’re an essential worker planning a Delaware home purchase in 2026, get on my early-notice list — I’ll let you know the moment Diamonds reopens so we can lock your reservation before funds run out again.
Get Funding AlertsI’m John Thomas, NMLS #38783, branch manager at Primary Residential Mortgage in Newark, Delaware, and I’ve been originating DSHA loans for over 20 years. The Delaware Diamonds program is one I’ve helped hundreds of Delaware essential workers use since DSHA first launched it — and the question I get most often is, “John, do I really qualify? My job isn’t on the list I saw.” Half the time, the answer is yes — and people leave $10,000 on the table because they read a short summary and assumed they didn’t fit. The list is broader than most people realize, the rules around how the $10,000 is forgiven are clearer than they look, and the way Diamonds layers on top of a DSHA Welcome Home or Open Door first mortgage is what makes it powerful. This page is the complete 2026 guide. If you’re a teacher, nurse, first responder, veteran, state employee, or work for one of the qualifying grocery/retail chains in Delaware, read this top-to-bottom — and then call me at 302-703-0727 to find out what you actually qualify for.
Delaware Diamonds DPA — Program at a Glance
| Assistance Amount | $10,000 (flat) |
| Loan Type | 0% interest, forgivable second mortgage |
| Forgiveness Schedule | 10% per year over 10 years |
| Monthly Payment | None — no payments required |
| Eligible Buyers | Delaware essential workers (teachers, nurses, first responders, military/veterans, state employees, qualifying grocery/retail) |
| First Mortgage Pairing | DSHA Welcome Home or DSHA Open Door |
| Minimum Credit Score | 620 (660 for manufactured homes) |
| Counseling Required | 8 hours HUD-approved counseling if score is 620–659 |
| Property Location | New Castle, Kent, or Sussex County (Delaware) — primary residence only |
| Apply Through | DSHA-approved lender (not directly with DSHA) |
| Current Status | Out of funds (April 2026) — get on the notification list |
| Source | Delaware State Housing Authority (DSHA) |
Are You a Delaware Essential Worker?
Find out in one phone call whether you qualify for the $10,000 Delaware Diamonds DPA — and which DSHA first mortgage is the best pairing for your situation.
What is the Delaware Diamonds DPA Program?
The DSHA Delaware Diamonds Home Loan — historically marketed as the “Delaware Diamond DPA Program” — is a down payment assistance loan from the Delaware State Housing Authority (DSHA) designed specifically for Delaware essential workers. It’s a $10,000 zero-interest, forgivable second mortgage that you use toward your down payment and/or closing costs when buying a primary residence in Delaware.
The program first launched at $15,000, was reduced to $10,000 in its second funding cycle, and has stayed at $10,000 since. Funding moves in waves — when DSHA issues new bonds, the program reopens; when the allocation runs out, the program pauses until the next cycle. In 2023 alone, 147 Delaware families used Diamonds, totaling $2.148 million in disbursed assistance. Demand consistently outpaces supply, which is why getting on an approved DSHA lender’s notification list before the next reopening matters.
Diamonds is not a standalone loan. You always pair it with a DSHA first mortgage — under the April 16, 2026 DSHA Delaware Mortgage Program rebrand, that means either DSHA Welcome Home (for first-time buyers) or DSHA Open Door (for first-time + repeat buyers). The Diamonds DPA itself stays the same; the first mortgage program just determines which income limits and underwriting overlay apply.
Who Qualifies as a Delaware Essential Worker?
This is the question I get more than any other. DSHA defines “essential worker” by occupation category and qualifying employer — not by job title alone. If you’re on the loan with a co-borrower, only one borrower needs to be an essential worker for the household to qualify. You also must have been employed in your essential worker role for at least 6 months prior to your loan application and currently be a Delaware resident.
Here are the qualifying occupation categories under the current DSHA Diamonds guidelines:
- Veterans and Active-Duty Military — Army, Navy, Air Force, Marines, Coast Guard, Space Force, National Guard, and Reserves.
- Education — Employees of public or private school districts; employees of licensed Delaware childcare facilities; licensed registered home childcare providers.
- Medical and Healthcare — Employees of Delaware hospitals (including Bayhealth, Beebe Healthcare, Nemours, Saint Francis Healthcare, ChristianaCare, and the VA Hospital); Registered Nurses (RN); Licensed Practical Nurses (LPN); Advanced Practice Registered Nurses (APRN); Certified Nursing Assistants; Health Care Practitioners; Physicians and Physician Assistants; Social Workers; Nursing Home employees.
- First Responders — Firefighters, police officers, Emergency Medical Technicians (EMT), paramedics, and qualifying volunteer first-responders.
- Grocery Store Employees — Employees of these chains: Acme, Giant, Wegmans, ShopRite, Food Lion, Redner’s, Lidl, Janssens’ Market, Weis Markets, Zingo’s, Safeway, Aldi, and Trader Joe’s.
- General & Wholesale Merchandise Retailers — Employees of these chains only: Walmart, Target, Costco, Sam’s Club, and BJ’s Wholesale.
- State of Delaware Employees — Anyone employed directly by the State of Delaware.
If you’re not sure whether your employer or job title qualifies — call. I review the current DSHA-approved employer list every time it updates, and I’ll tell you in one conversation whether you fit.

How Does the $10,000 Forgivable Loan Work?
Diamonds is structured as a zero-interest second mortgage recorded against the property. You don’t make any monthly payments on it. The loan is forgiven at 10% per year for as long as you live in the home as your primary residence. After 10 years, the entire $10,000 is forgiven and you owe nothing.
If you sell, refinance, or stop using the home as your primary residence before the 10-year mark, you owe back a prorated portion of the original $10,000. Here’s the year-by-year forgiveness schedule:
| Year in Home | Amount Forgiven | Amount Still Owed |
|---|---|---|
| After Year 1 | $1,000 | $9,000 |
| After Year 2 | $2,000 | $8,000 |
| After Year 3 | $3,000 | $7,000 |
| After Year 4 | $4,000 | $6,000 |
| After Year 5 | $5,000 | $5,000 |
| After Year 6 | $6,000 | $4,000 |
| After Year 7 | $7,000 | $3,000 |
| After Year 8 | $8,000 | $2,000 |
| After Year 9 | $9,000 | $1,000 |
| After Year 10 | $10,000 (full) | $0 |
If you change jobs after closing — even out of an essential worker role — that does not trigger repayment. The eligibility test is at the time of application. As long as you continue using the property as your primary residence, the forgiveness clock keeps ticking.

How Does Diamonds Compare to Delaware’s Other DSHA DPAs?
Diamonds is one of five DSHA down payment assistance programs available under the Delaware Mortgage Program. Each DPA has different qualification rules, dollar amounts, and first-mortgage pairings. This is the side-by-side breakdown most buyers want to see:
| DPA Program | Amount | Structure | Pairs With | Best For |
|---|---|---|---|---|
| Diamonds | $10,000 flat | 0% forgivable over 10 yrs | Welcome Home or Open Door | Essential workers (when funded) |
| First State | 3% of loan | 0% deferred 2nd | Welcome Home or Open Door | Anyone — universal pairing |
| Keys4You | 4% of loan | 0% deferred 2nd | Welcome Home or Open Door | Largest DPA for repeat buyers |
| Take5 | 5% of loan | 0% deferred 2nd | Welcome Home only | First-time buyers, max DPA |
| Diamond in the Rough | 5% of loan + 203k | 0% deferred 2nd + renovation | Welcome Home only | Fixer-upper purchases |
Important: Diamonds is a flat $10,000, while the others are percentage-based. On smaller loan amounts, Diamonds is often the largest DPA you can access. On loans over ~$250,000–$330,000, First State (3%), Keys4You (4%), or Take5 (5%) may produce more dollars. The right answer depends on your loan size, profession, and whether you’re a first-time or repeat buyer — that’s exactly what a 30-minute pre-approval call sorts out.
What Are the Income Limits for the Delaware Diamonds Program?
Income eligibility for Diamonds is tied to the income limits of the DSHA first mortgage you pair it with — Welcome Home or Open Door. Welcome Home has lower income limits and is for first-time buyers only. Open Door has higher income limits and accepts both first-time and repeat buyers. For both first-mortgage programs, only the income of borrowers on the Note and Mortgage is counted (not all household members) — though household size still sets the limit tier.
Income limits are set per county and per household size, and DSHA updates them as bond cycles allow. Welcome Home limits in non-targeted areas are currently $119,400 (1–2 person) for New Castle County and $108,800 (1–2 person) for Kent and Sussex counties. Open Door limits are higher — and they shift more often, so I always confirm the current figure on the phone before issuing a pre-approval.
Targeted-area income limits are significantly higher and waive the first-time buyer requirement statewide for properties in DSHA-designated targeted census tracts. If you’re looking at a property in a targeted area, the math changes a lot in your favor. Call 302-703-0727 and I’ll pull the current income limit chart for your specific county and household size before we file anything.
Heads-up: Chart shows 2024 income limits. DSHA refreshes income limits with each new bond cycle, and 2026 limits have been updated. Always confirm current limits for your county and household size by calling 302-703-0727 before submitting an offer.

What Properties Can I Buy with the Delaware Diamonds DPA?
Diamonds follows the eligible-property rules of the DSHA first mortgage you pair it with. The property must be located in Delaware (New Castle, Kent, or Sussex County), it must become your primary residence, and it must fit one of these property types:
- Single-family detached residence
- Townhomes and row homes
- Warrantable condominiums
- Planned Unit Developments (PUDs)
- Manufactured homes meeting DSHA guidelines (660 minimum credit score)
- 1–4 unit properties — as long as you live in one of the units
Properties that do not qualify: rental/investment properties, second homes, co-ops, and non-warrantable condos.
There’s also a maximum sales price per county that DSHA updates with each new bond cycle. The current limits run higher in New Castle County than in Kent or Sussex. If you’re shopping at the upper end of your county’s price range, this matters — call before you submit an offer so we can confirm the current cap.
Heads-up: Chart shows 2024 maximum purchase price limits. DSHA updates the cap each bond cycle, and 2026 limits are higher in all three counties than what’s shown below. Confirm the current cap for the county where you’re buying by calling 302-703-0727 before submitting an offer.

Heads-Up on Delaware’s 4% Transfer Tax
One of the biggest reasons buyers use Diamonds is to cover Delaware’s 4% transfer tax — which on a $300,000 home is $12,000. The standard Delaware Association of Realtors (DAR) sales contract splits the transfer tax equally: 2% buyer / 2% seller. So on a $300,000 home, your buyer-side share is $6,000 — and Diamonds’ $10,000 covers all of that plus other closing costs.
Critical for new construction: Home builders write their own contracts and may require the buyer to pay the full 4% transfer tax — not the standard 2%/2% DAR split. Always have your buyer’s agent and your lender review the builder’s contract before you sign. If the builder is shifting all 4% to you, on that same $300,000 home you’re now at $12,000 — and Diamonds plus an additional DPA like First State or Keys4You may be needed to cover everything.
For the full Delaware closing-cost breakdown — title, recording, attorney fees, escrow setup, and pre-paids — see my Understanding Seller-Paid Closing Costs guide.
Do I Apply Through DSHA or Through a DSHA-Approved Lender?
You apply through a DSHA-approved lender — not through DSHA directly. DSHA is the state agency that funds the program and sets the rules, but it does not take individual loan applications. Instead, DSHA partners with a network of approved Delaware mortgage lenders, and only those lenders are authorized to originate, underwrite, and submit Diamonds files to DSHA’s mortgage division.
This is the same setup DSHA uses on its own website — the Delaware State Housing Authority directs prospective buyers to “contact a DSHA-trusted lender” as the first step. Primary Residential Mortgage is one of those lenders, and I’ve been originating DSHA loans since the Diamonds program existed. Working with an approved lender who actually knows the program — versus a national lender who has only heard of it — is the single biggest factor in whether your reservation goes through clean and on time.
How Do I Apply for the Delaware Diamonds DPA Program?
You can’t apply directly to DSHA — Diamonds is only available through DSHA-approved lenders. Primary Residential Mortgage is one of them, and I’ve been originating DSHA loans since the program existed. Here’s the process:
- Step 1 — Initial call. Call 302-703-0727 or schedule a 30-minute appointment. We confirm essential worker eligibility, confirm Diamonds funding status, and identify the right first-mortgage pairing (Welcome Home vs. Open Door).
- Step 2 — Credit pull and pre-approval. We start with a soft credit pull, then collect income, employment, and asset documentation for the full pre-approval. The minimum credit score for Diamonds is 620; if you’re between 620 and 659, DSHA requires you to complete 8 hours of HUD-approved homebuyer counseling before closing.
- Step 3 — Reservation. Once you’re pre-approved, I reserve your Diamonds DPA with DSHA. This is the step that locks in your $10,000 — when funds are tight, getting your reservation in early matters.
- Step 4 — Find the home, go under contract. Your buyer’s agent helps you find the property. Once you’re under contract, your formal application gets submitted to DSHA underwriting along with the standard mortgage file.
- Step 5 — Closing. Delaware uses attorney-state closings. Your real estate attorney handles the settlement; both the first mortgage and the Diamonds second mortgage record against the property at the same time.
Total time from initial call to pre-approval letter is typically 24–48 hours. From pre-approval to closing is usually 30–45 days, depending on the property and the contract.
What Should I Do While Delaware Diamonds Is Out of Funds?
The fact that Diamonds is currently paused doesn’t mean you stop. It means you stage everything so the day DSHA reopens funding, your reservation is the first one in. Here’s the productive sequence — these are the same steps I walk every essential worker buyer through right now:
- Get a soft pre-approval done now. A soft credit pull and a documented pre-approval don’t expire — they refresh easily — and having the file already built means we submit your Diamonds reservation the moment DSHA’s portal reopens. Buyers without pre-approvals are still gathering paystubs while reserved buyers are already locked in.
- Confirm your essential worker eligibility. Some borderline cases (charter school staff, certain home daycare providers, some retail employers) need a closer look at the current DSHA-approved list. We sort that on the call so you’re not finding out at underwriting.
- Evaluate alternative DSHA DPAs in parallel. If you’re a first-time buyer, the DSHA First State (3%), Keys4You (4%), or Take5 (5%) programs may be funded right now and may give you more dollars on a larger loan than Diamonds’ flat $10,000. Don’t wait for Diamonds to reopen if a better-funded option already fits.
- Take the homebuyer counseling now if your score is 620–659. The 8-hour HUD-approved counseling requirement is the most common reason a Diamonds closing gets delayed. Take it now — it’s good for 12 months — and your file is fully cleared the moment funds return.
- Attend a free Delaware Homebuyer Seminar. The seminar covers DSHA programs, FHA/VA/USDA, closing costs, the 4% transfer tax, and what to expect from contract to close. It’s the same content I deliver to clients one-on-one, but you can watch it on your own timeline.
- Get on my Diamonds notification list. When DSHA’s reservations portal reopens, the first 24–48 hours are the busiest of the cycle. I notify pre-approved buyers on day one — call 302-703-0727 or schedule a 30-minute call.
Delaware Areas We Help with the Diamonds DPA Program
I help Delaware essential workers review DSHA Delaware Diamonds eligibility across all three Delaware counties. The most common areas I work in include:
- New Castle County: Newark, Wilmington, Bear, Middletown, New Castle, Hockessin, Pike Creek, Glasgow, Claymont, Smyrna
- Kent County: Dover, Camden, Smyrna, Magnolia, Felton, Harrington, Milford
- Sussex County: Lewes, Rehoboth Beach, Milford, Georgetown, Seaford, Millsboro, Bridgeville, Selbyville, Dagsboro, Laurel
The Diamonds program rules are the same statewide, but income limits and maximum sales price limits do vary by county. I’m based in Newark, Delaware, and I work with essential worker buyers across the entire state. Wherever you’re buying, the conversation starts the same way: a 30-minute eligibility review.
Want to Learn More? Attend a Free Delaware Homebuyer Seminar
I host free Delaware First Time Home Buyer Seminars every month in Newark, Wilmington, and Dover — and the 8-hour HUD-approved counseling requirement for Diamonds buyers below a 660 credit score can be satisfied through the seminar partner agencies. Watch a recent recording below or register for the next live seminar at DelawareHomeBuyerSeminar.com.
FAQ — Delaware Diamonds DPA Program
Is the Delaware Diamonds DPA program currently funded?
As of April 2026 the Delaware Diamonds program is out of funds. DSHA reloads Diamonds when its bond funding cycle resets, and demand fills the allocation quickly each time. If you are an essential worker planning a Delaware home purchase, call 302-703-0727 to get on my early-notice list — I will let you know the moment Diamonds reopens so we can submit your reservation before funds run out again.
What is the Delaware Diamonds DPA program?
The DSHA Delaware Diamonds Home Loan is a $10,000 zero-interest, forgivable second mortgage from the Delaware State Housing Authority for qualifying Delaware essential workers. It is paired with a DSHA Welcome Home or DSHA Open Door first mortgage and is used toward your down payment and closing costs. The loan is forgiven at 10% per year over 10 years if you continue using the home as your primary residence. After year 10, the entire $10,000 is forgiven and you owe nothing.
How much does the Delaware Diamonds DPA program provide?
The current Delaware Diamonds DPA amount is $10,000. The program initially launched at $15,000, was reduced to $10,000 in its second funding cycle, and has remained at $10,000 since. The full $10,000 is provided as a zero-interest, forgivable second mortgage with no monthly payments.
Who qualifies as a Delaware essential worker for the Diamonds DPA?
DSHA defines essential workers by occupation category and qualifying employer. The categories include: veterans and active-duty military across all branches; education employees including school district staff and licensed childcare providers; medical and healthcare workers including hospital employees, RNs, LPNs, APRNs, CNAs, physicians, and nursing home staff; first responders including firefighters, police officers, EMTs, paramedics, and qualifying volunteer first-responders; grocery store employees at named chains including Acme, Giant, Wegmans, ShopRite, Food Lion, Redner’s, and others; retail employees at Walmart, Target, Costco, Sam’s Club, and BJ’s Wholesale; and State of Delaware employees. You must be employed in your essential worker role for at least 6 months prior to your loan application and currently be a Delaware resident.
Do I have to be a first-time home buyer to use Delaware Diamonds?
Not necessarily. Diamonds itself is the DPA — eligibility for first-time vs. repeat buyer is determined by which DSHA first mortgage you pair it with. If you pair Diamonds with DSHA Welcome Home, yes — you must be a first-time buyer (no homeownership in the past 3 years). If you pair Diamonds with DSHA Open Door, both first-time and repeat buyers qualify. This dual-pairing flexibility is one of the reasons Diamonds is valuable for essential workers buying their second or third home in Delaware.
What credit score do I need for the Delaware Diamonds DPA?
The minimum credit score for Delaware Diamonds is 620. If your credit score is between 620 and 659, DSHA requires you to complete 8 hours of HUD-approved homebuyer counseling before closing — typically a $125 fee at an approved Delaware housing counseling agency. If your score is 660 or higher, the counseling requirement is waived. For manufactured homes, the minimum credit score is 660 regardless of program.
Can I combine Delaware Diamonds with another DSHA DPA?
No. DSHA allows one DPA per transaction. You choose either Diamonds, First State (3%), Keys4You (4%), Take5 (5% — Welcome Home only), or Diamond in the Rough (5% with FHA 203k — Welcome Home only) — but not two stacked together. The right choice depends on your loan size, your essential worker status, your first-time-buyer status, and your cash needs at closing. On smaller loan amounts, the flat $10,000 from Diamonds often beats the percentage-based options. On larger loans, percentage-based DPAs may give you more dollars. We run the comparison for your exact scenario as part of the pre-approval process.
What happens to my Diamonds DPA if I leave my essential worker job after closing?
Nothing. Eligibility is verified at the time of application — you only need to have been in your essential worker role for at least 6 months prior to applying. After closing, your job status does not affect the forgiveness schedule. As long as you continue using the property as your primary residence, the loan continues to forgive at 10% per year and is fully forgiven after year 10.
What happens if I sell or refinance my home before 10 years?
You repay a prorated portion of the original $10,000. The forgiveness reduces the balance owed by 10% for each full year you have lived in the property. For example, if you sell after 4 years, $4,000 has been forgiven and you repay $6,000 at settlement. If you sell after 7 years, $7,000 has been forgiven and you repay $3,000. There is no penalty interest — you simply repay the prorated principal balance.
Can I use Delaware Diamonds in any Delaware county?
Yes. Delaware Diamonds is available statewide for primary-residence purchases in New Castle County, Kent County, and Sussex County. The income limits and maximum sales price limits vary by county and household size, and DSHA updates them with each bond cycle. New Castle County limits are typically higher than Kent and Sussex.
How do I apply for the Delaware Diamonds DPA?
You apply through a DSHA-approved lender — DSHA does not accept applications directly. Call John Thomas, NMLS #38783, at 302-703-0727 or apply online. We start with a soft credit pull and a 30-minute eligibility consultation, then build a full pre-approval that confirms your essential worker status, your income limit fit, the right first-mortgage pairing (Welcome Home or Open Door), and reserves your Diamonds funds with DSHA. The full pre-approval typically takes 24–48 hours.
What is the difference between Delaware Diamonds and Diamond in the Rough?
They are two different DSHA programs that share a similar name. Delaware Diamonds is the $10,000 forgivable DPA for essential workers. Diamond in the Rough is a separate program that combines an FHA 203(k) Limited renovation loan with a 5% DPA — designed for buyers purchasing a fixer-upper that needs renovations rolled into the mortgage. Diamond in the Rough does not require essential worker status. Diamonds requires essential worker status. They cannot be combined with each other on the same loan.
What happens if DSHA Diamonds funds run out before I go under contract?
If you have already reserved your Diamonds funds with DSHA before funds run out, your reservation is held for the standard reservation window (typically 60–90 days from reservation date) — even if the program closes to new applicants the day after you reserve. If you have not yet reserved when the program runs out of funds, you will need to wait for the next funding cycle to reopen. The best protection is to complete your pre-approval and reserve as early as possible. If funds run out during your reservation period, we evaluate alternative DPA programs (First State, Keys4You, or Take5) and switch your file before your contract closes — often without delaying settlement.
Can I use Delaware Diamonds with FHA, VA, USDA, or conventional financing?
Yes — Delaware Diamonds is the DPA second mortgage and works with most standard first mortgage products available through DSHA Welcome Home or DSHA Open Door. The DSHA first mortgage program supports FHA, VA, USDA Rural Housing, and conventional loans, and Diamonds layers on top of any of them. The right first mortgage type depends on your credit profile, the property location, your military/veteran status, and your down payment situation. As part of your eligibility review, we map out which first mortgage type plus DPA combination puts the most money in your pocket at closing.
Which is better — Delaware Diamonds or DSHA Keys4You?
It depends on your essential worker status and your loan size. Delaware Diamonds is a flat $10,000 — the same amount regardless of loan size. DSHA Keys4You is 4% of your loan amount — the dollar amount scales with the size of your mortgage. On a $200,000 loan, Keys4You provides $8,000 (less than Diamonds’ $10,000). On a $300,000 loan, Keys4You provides $12,000 (more than Diamonds). The break-even point is around $250,000. Keys4You also has no essential worker requirement, while Diamonds requires it. Because DSHA only allows one DPA per transaction, the right answer depends on your specific loan size, profession, and first-time-buyer status — which is exactly what we run during the pre-approval call.

About the Author — John R. Thomas
Branch Manager & Mortgage Loan Officer — Primary Residential Mortgage, Inc.
John R. Thomas is a DSHA-approved mortgage loan officer and Branch Manager at Primary Residential Mortgage, Inc. in Newark, Delaware. With over 20 years of mortgage lending experience and 3,000+ Delaware buyers helped, John has been originating DSHA Delaware Diamonds DPA loans since the program first launched and has guided hundreds of Delaware essential workers — teachers, nurses, first responders, veterans, state employees, and qualifying grocery/retail workers — through the qualification, reservation, and forgiveness rules.
John holds a Bachelor of Science in Physics Education from the University of Delaware and a Master of Science in Curriculum and Instruction from Delaware State University — credentials that translate directly into the way he teaches Delaware home buyers about complex topics like Diamonds’ employer-eligibility nuance, the math behind the 10-year forgiveness clock, and how to stage a pre-approval so the file is ready the moment DSHA reopens funding.
John is the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826) and teaches the monthly Delaware First Time Home Buyer Seminar in Newark, Wilmington, and Dover. His firsthand expertise on the DSHA Diamonds program — including the employer-list updates, the funding-cycle timing, and how to layer Diamonds with the right first mortgage — is the kind of lender knowledge national aggregator and bank sites simply cannot match.
248 E Chestnut Hill Rd, Newark, DE 19713
302-703-0727 | Schedule Appointment | See John Thomas Team on Google for reviews, directions, and local office information | YouTube Channel | NMLS #38783 Verified

Get on the Diamonds Notification List
Funding moves fast when DSHA reopens Diamonds. Start your soft pre-approval now so when the program reloads, your $10,000 reservation goes in on day one. No pressure, no obligation — just straight answers from a DSHA-approved lender with 20+ years in Delaware.
Last Updated: April 28, 2026
John Thomas, NMLS #38783 | Primary Residential Mortgage, Inc. | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net | Licensed by the Delaware State Bank Commissioner | Equal Housing Lender
Copyright John R. Thomas, All Rights Reserved.
