
What is PITI Mortgage Payment? A Delaware Buyer’s Guide

Quick Answer for Delaware Buyers
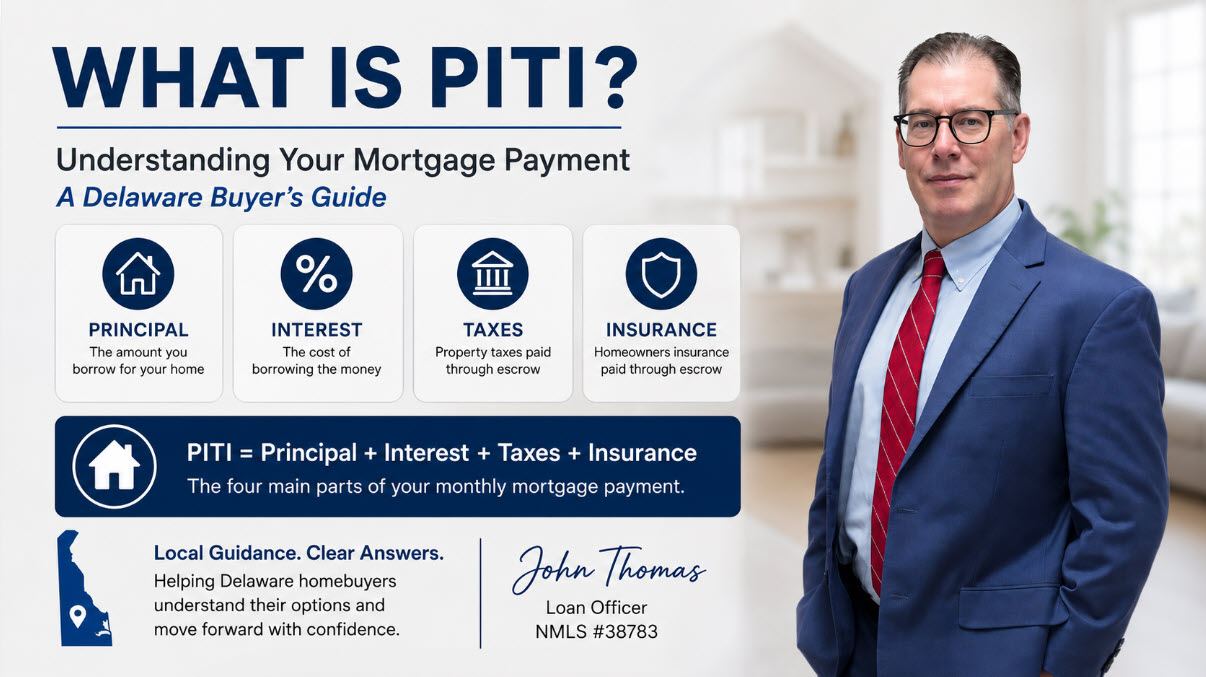
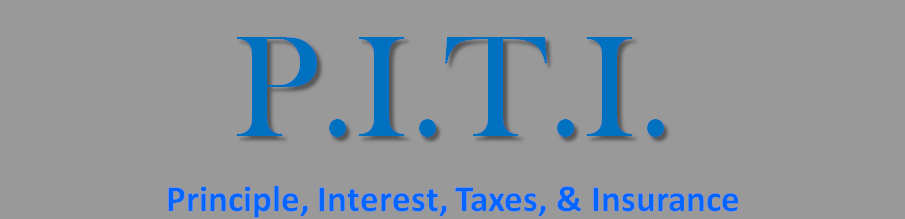
PITI stands for Principal, Interest, Taxes, and Insurance — the four main parts of a monthly mortgage payment for Delaware homebuyers.
- Principal — the loan amount you’re paying back
- Interest — what the lender charges you to borrow
- Taxes — Delaware property taxes, divided by 12 and held in escrow
- Insurance — homeowners insurance, also escrowed monthly
If your loan requires mortgage insurance — which applies to most FHA, USDA, and low-down-payment conventional loans in Delaware — that gets added on top as PITI + MI. VA loans skip mortgage insurance entirely. Current as of May 2026.
The PITI Formula
Principal + Interest + Taxes + Insurance = PITI
Add mortgage insurance and HOA dues for the full monthly housing payment lenders use to qualify you:
PITI + MI + HOA = Total Monthly Housing Payment
Your PITI mortgage payment is the four-part monthly payment every Delaware homebuyer needs to understand before closing — Principal, Interest, Taxes, and Insurance. I’m John Thomas, NMLS #38783, and I’ve been explaining PITI to Delaware first-time buyers for over 20 years out of the Primary Residential Mortgage office at 248 E Chestnut Hill Rd in Newark. Most of the confusion I see isn’t about what PITI means — it’s about what’s actually included, what changes year to year, and how mortgage insurance gets added on top. This page walks through all of it with Delaware-specific numbers and what to expect across FHA, VA, USDA, conventional, and DSHA loan programs. If this is your first home purchase, also check out our Delaware First-Time Home Buyer Guide for the full picture beyond just the monthly payment.
Who This Guide Is For
This PITI mortgage payment guide is written for: Delaware first-time buyers reviewing pre-approval numbers, repeat buyers comparing monthly payments across different homes or loan programs, and current homeowners trying to understand why their payment changed at escrow analysis. If you want a property-specific PITI estimate for an actual Delaware home you’re considering, call 302-703-0727 — that’s faster than any online calculator.
Ready to Calculate Your Actual Delaware Mortgage Payment?
Get a real PITI estimate based on your credit, down payment, and the home you’re considering. No guesswork, no generic calculators — just an actual quote from a Delaware loan officer.
Table of Contents
What Does PITI Stand For?
PITI is the four-letter acronym lenders, real estate agents, and underwriters use for the four parts of your monthly mortgage payment:
| Letter | Stands For | What It Pays |
|---|---|---|
| P | Principal | The portion that pays down the actual loan balance |
| I | Interest | What the lender charges you to borrow the money |
| T | Taxes | Delaware property taxes, divided by 12 and held in escrow |
| I | Insurance | Homeowners insurance premium, also escrowed monthly |
When your loan requires mortgage insurance, that gets added as a fifth piece — making your full payment PITI + MI. We’ll cover MI in detail further down.
PITI vs PITI + MI vs PITIA — what’s the difference? Technically, PITI means principal, interest, taxes, and homeowners insurance only. If your loan also has mortgage insurance, you’ll see PITI + MI. If your home is in a Delaware community with HOA dues, lenders will add the HOA to your qualifying ratios and may show your total as PITIA (the A is for Association fees). All three terms describe the same underlying math — they just differ in what’s included.
Quick note on what’s NOT in PITI: If you’re buying in a Delaware neighborhood with a Homeowners Association (HOA), your HOA fee is paid separately — it’s not collected with your mortgage payment. HOAs in Delaware can be monthly, quarterly, or annual depending on the community. Always check the HOA cost before you write the offer, because lenders will count it against your debt-to-income ratio.
How is Your Principal & Interest Calculated?
Your principal and interest payment — what loan officers call your P&I — is the part of your mortgage payment that pays back the actual loan plus the interest charged. It’s calculated using three numbers: how much you owe, your interest rate, and the loan term (also called amortization).
Here’s a sample calculation so you can see how it works. This is illustrative only — rates change daily, so call 302-703-0727 for a current Delaware rate quote based on your actual credit and loan scenario.
Sample P&I Calculation
- Loan amount (principal balance): $200,000
- Interest rate: 5.5% (illustrative — not a current rate quote)
- Term: 30 years (360 months)
- Monthly P&I: $1,135.58
Here’s something most first-time buyers don’t realize: even though your monthly P&I stays the same for the full 30 years on a fixed-rate loan, the breakdown between principal and interest shifts every single month. Mortgages are front-loaded with interest — meaning in the early years, most of your payment goes to interest, not principal.
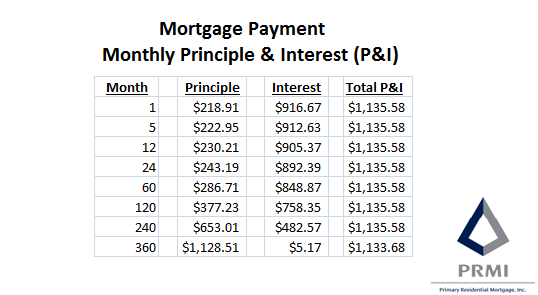
Look at the table above. On the very first payment of a $200,000 loan at 5.5%, only about $218 goes to principal — the other $917 goes to interest. By payment #210 (about 17.5 years in), you finally hit the 50/50 mark. By payment #240 (year 20), more is going to principal than interest. And on your final payment in year 30, almost the whole $1,135.58 goes to principal because there’s barely any loan balance left to charge interest on.
This is why refinancing early in a loan can save serious money — and why making extra principal payments has such an outsized effect (covered below).
How Are Property Taxes & Homeowners Insurance Added to Your Payment?
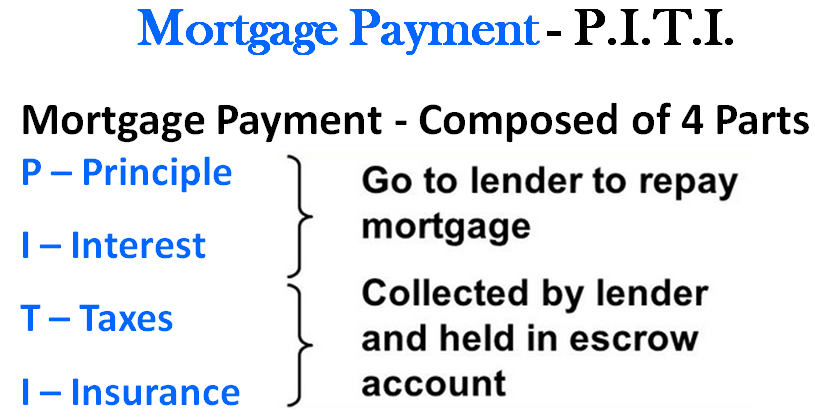
The “TI” part of PITI — taxes and insurance — gets added to your monthly payment through an escrow account. Here’s how it works in Delaware:
- Your lender estimates your annual Delaware property tax bill and your annual homeowners insurance premium.
- Both annual amounts get divided by 12.
- That monthly amount gets added to your P&I and collected with your mortgage payment every month.
- The lender holds those funds in your escrow account until the bills come due.
- When your county tax bill arrives, the lender pays it from escrow. When your insurance renewal comes up, the lender pays that too.
Let’s add taxes and insurance to the same example to see what a full PITI payment looks like:
Sample PITI Calculation (Same Loan + Taxes + Insurance)
- Monthly P&I (from above): $1,135.58
- Annual Delaware property taxes: $2,400 (= $200/month)
- Annual homeowners insurance: $600 (= $50/month)
- Total monthly PITI payment: $1,385.58
Property tax and insurance amounts shown are illustrative. Actual Delaware property taxes vary significantly by county and municipality (see Delaware-specific section below). Insurance varies by home value, location, and coverage.
How Do Delaware Property Taxes Affect Your PITI Payment?
Delaware has some of the lowest property tax rates in the country — but they vary meaningfully by county and by school district. The “T” in your PITI is going to look very different depending on where you buy:
| County | General Property Tax Range | Notes |
|---|---|---|
| New Castle County | Higher (county + school district + municipal layers) | Wilmington, Newark, Bear, Middletown — varies by school district |
| Kent County | Lower than NCC | Dover, Smyrna, Camden — generally moderate |
| Sussex County | Lowest of the three counties | Lewes, Rehoboth, Milford — beach markets often have lowest effective rates |
Two important things to know about Delaware property taxes for your PITI calculation:
- Property taxes can change. Delaware counties periodically reassess property values, and millage rates can shift year to year. When that happens, your escrow analysis adjusts and your PITI payment goes up or down accordingly. Most lenders run an escrow analysis once a year.
- Wilmington has a city-level transfer tax (separate issue from property tax, but often confused). For PITI purposes, Wilmington property taxes are higher than surrounding New Castle County areas because of city-specific assessments. If you’re buying in Wilmington proper versus the suburbs, your “T” will be noticeably different.
Delaware PITI Examples by City and County (Illustrative)
To show how location alone changes a Delaware PITI payment, here’s how the same $300,000 home with a $285,000 loan amount, illustrative 6.5% interest rate, and 30-year term might look across five Delaware markets. These are illustrative ranges only — actual property tax bills depend on the specific property, school district, and current assessment. Insurance varies by carrier and coverage. Always verify with the county assessor and an insurance quote for the exact home you’re considering. Rates change daily — call 302-703-0727 for a current rate quote.
| Delaware Market | P&I (illustrative) | Est. Monthly Tax Range | Est. Monthly Insurance | Est. Monthly PITI Range |
|---|---|---|---|---|
| Wilmington (NCC) | $1,801 | $350–$500 | $80–$120 | $2,231–$2,421 |
| Newark (NCC) | $1,801 | $280–$420 | $80–$120 | $2,161–$2,341 |
| Middletown (NCC) | $1,801 | $240–$380 | $80–$120 | $2,121–$2,301 |
| Dover (Kent) | $1,801 | $140–$240 | $70–$110 | $2,011–$2,151 |
| Lewes / Rehoboth (Sussex) | $1,801 | $120–$220 | $90–$140 (coastal) | $2,011–$2,161 |
What this means for you: Two Delaware homes priced identically can have meaningfully different monthly PITI payments because of where they sit. The $300,000 example above shows up to a $400/month range across markets — that’s $4,800 per year, $144,000 over 30 years. Before writing an offer, ask your loan officer for a property-specific PITI estimate using actual tax records and an insurance quote — not a generic calculator. Looking at homes in New Castle County? Call our Newark office at 302-703-0727 to run the exact PITI math on a specific property.
What if You Have to Pay Mortgage Insurance?
This is where Delaware buyers get tripped up the most. If your loan requires mortgage insurance (MI), your monthly payment becomes PITI + MI. Mortgage insurance protects the lender — not you — in case you default on the loan. The borrower pays the premium, but the policy benefits the lender.
Whether you owe MI depends entirely on which loan program you use:
| Loan Program | Mortgage Insurance Required? | When It Can Be Removed |
|---|---|---|
| Conventional | PMI required if down payment is less than 20% | Automatic at 78% LTV; can request at 80% LTV (Homeowners Protection Act) |
| FHA | UFMIP at closing + monthly MIP for the life of the loan in most cases | Cannot be removed in most current FHA loans — refinance to conventional once LTV reaches ~80% |
| USDA | Upfront guarantee fee + annual fee paid monthly | Cannot be removed — refinance to conventional to drop it |
| VA | NO mortgage insurance, even with 0% down (VA funding fee instead, paid once) | N/A — no monthly MI to remove |
| DSHA Welcome Home / Open Door | Depends on the underlying first mortgage (FHA, VA, USDA, or Conventional) | Follows the rule for whichever loan type underlies the DSHA program |
Here’s what mortgage insurance does to the same sample payment from earlier. Using a hypothetical monthly MI premium of $141.67 (premiums vary widely based on credit, LTV, and loan program):
Sample PITI + MI Calculation
- Monthly P&I: $1,135.58
- Monthly taxes (escrow): $200
- Monthly insurance (escrow): $50
- Monthly MI premium: $141.67 (illustrative)
- Total monthly PITI + MI: $1,527.25
MI premiums vary by program, credit profile, LTV, and current investor pricing — call 302-703-0727 for figures specific to your scenario.
How Does PITI Work With DSHA Down Payment Assistance in Delaware?
This is a question I get on almost every Delaware first-time buyer consultation. If you’re using a DSHA down payment assistance program like Keys4You, Take5, or First State, here’s the key thing to understand: the DPA money is a second loan — but it’s a zero-interest, deferred-payment second loan that doesn’t add anything to your monthly PITI.
What DSHA DPA does do is reduce the cash you bring to closing — meaning you may not need to drain your savings for the down payment. But because the second loan is deferred (no monthly payment), your monthly PITI is calculated only on the first mortgage (your DSHA Welcome Home or Open Door loan, which is typically FHA, VA, USDA, or Conventional). The mortgage insurance rules in the table above still apply based on whichever first-mortgage loan type you use.
The DSHA second loan only comes due when you sell the home, refinance the first mortgage, or pay off the first mortgage. Until then, it sits quietly in the background and doesn’t affect your monthly payment.
What Happens if You Make Extra Payments on Your Mortgage?
Because mortgages are front-loaded with interest, putting extra money toward your principal (not your total payment) early in the loan can shave years off the term and save tens of thousands in interest. There are two practical ways to do it:
Option 1: Add Extra to Each Monthly Payment
If your P&I is $1,200/month and you want to make one extra payment per year, divide $1,200 by 12 = $100. Pay an extra $100 toward principal every month. Over a 30-year mortgage, this typically shaves 5–7 years off the term. You stay flexible — you can stop, increase, or decrease the extra amount any time.
Option 2: Set Up Bi-Weekly Payments
Pay half your monthly mortgage payment every two weeks instead of the full amount once a month. Because there are 52 weeks in a year, you end up making 26 half-payments — equivalent to 13 full monthly payments instead of 12. That extra payment goes straight to principal and produces the same 5–7-year reduction on a 30-year loan. Important: make sure your lender actually applies bi-weekly payments to principal as you make them — some servicers hold the half-payments and only apply them as a single monthly payment, which kills the benefit.
When Extra Payments Are NOT the Right Move
Paying extra principal isn’t always the smartest use of your money. Skip extra payments if any of these apply:
- You don’t have 3–6 months of emergency savings. Cash trapped in home equity is hard to access in a crisis. Build the emergency fund first.
- You have higher-interest debt. Credit card debt at 22% APR or a personal loan at 14% APR costs more than your mortgage interest. Pay those off first — math wins.
- You’re not maxing your employer 401(k) match. A 50% or 100% employer match is an instant return that beats any extra principal payment.
- You plan to sell or refinance in the next 2–3 years. Extra principal payments build equity, but if you’re selling soon, you’ll get that equity back at closing anyway — without giving up cash flexibility now.
- Your mortgage rate is below market. If you locked a 3% rate during 2020–2021, that money is worth more invested elsewhere than paying down a sub-3% loan early.
How Can Your PITI Payment Change Over Time?
Even with a 30-year fixed-rate mortgage, your total PITI payment can shift year to year. Here’s why and what to watch for:
- Property tax reassessment. When your Delaware county reassesses property values or adjusts millage rates, your tax escrow goes up (or occasionally down). Your lender runs an annual escrow analysis and adjusts your monthly payment accordingly.
- Insurance premium increases. Homeowners insurance premiums have been rising significantly in recent years across most US markets, including Delaware. When your renewal premium comes in higher, your insurance escrow ticks up.
- Escrow shortage or surplus. If your taxes or insurance came in higher than what was being escrowed, you’ll have a shortage that gets spread over the next 12 months — temporarily raising your payment. The opposite can happen too: if you escrowed too much, you may get a refund check and a temporary lower payment.
- Mortgage insurance removal. On a conventional loan, when you reach 78% LTV, PMI drops off automatically — your monthly payment drops by the MI amount. You can request removal at 80% LTV under the Homeowners Protection Act.
- Refinancing. Refinancing replaces your existing loan with a new one and resets the entire PITI calculation based on the new rate, term, and loan amount.
Your P&I portion stays fixed for the life of a 30-year fixed loan — but the T, I, and MI portions can move. That’s why your statement shows your “current monthly payment” rather than a single locked number for 30 years.
How Lenders Use PITI to Decide What You Can Afford
When a Delaware lender tells you what home price you qualify for, they’re not looking at just your P&I — they’re looking at your full PITI plus any HOA fees. Two ratios matter:
| Ratio | What It Measures | General Guideline |
|---|---|---|
| Front-end (Housing) Ratio | PITI + MI + HOA divided by gross monthly income | Typically up to 31% on most loan programs (varies by program) |
| Back-end (Total DTI) Ratio | PITI + MI + HOA + all other monthly debt (cars, credit cards, student loans, etc.) divided by gross monthly income | Typically up to 43%–50% depending on loan program and compensating factors |
This is why two buyers with identical incomes can qualify for very different home prices — the buyer with no car payment and no student loans has more room in their back-end DTI than the buyer carrying $800/month in other debt. When you talk to me about getting pre-approved, the first thing I do is calculate your max PITI based on your income, then work backward from there to figure out a realistic Delaware home price range.
Want to dig deeper into Delaware buyer math? Our Delaware First-Time Home Buyer Guide walks through pre-approval, programs, and closing costs in detail, and our seller-paid closing costs guide explains how to get the seller to cover up to 6% of your closing costs (which can free up cash for a larger down payment, lowering your PITI).
FAQ — PITI & Your Delaware Mortgage Payment
Does PITI include HOA fees in Delaware?
No. HOA fees are paid separately from your PITI mortgage payment, even though lenders count HOA fees against your debt-to-income ratio when qualifying you. If you’re buying in a Delaware community with an HOA — common in newer developments in Bear, Middletown, and parts of Sussex County — make sure you find out the monthly HOA cost before writing your offer. Some real estate listings show PITIA (with the A for HOA association fee) when HOA is included in the affordability estimate, but PITI alone refers only to principal, interest, taxes, and insurance.
Can I get a Delaware mortgage after a Chapter 7 bankruptcy?
Yes, but the waiting period and impact on your PITI depends on the loan program. FHA generally requires a 2-year wait from Chapter 7 discharge with re-established credit. VA loans typically follow a similar 2-year guideline. Conventional loans usually require 4 years from discharge. USDA generally requires 3 years. DSHA programs follow the underlying first-mortgage rules (FHA, VA, USDA, or Conventional). After bankruptcy, your credit profile typically results in higher mortgage insurance rates initially, which raises your PITI — but as your credit recovers and equity builds, refinancing later can reduce or remove that MI cost. Call 302-703-0727 for a scenario-specific evaluation.
Why did my mortgage payment go up if I have a fixed-rate loan?
Your principal and interest portion of PITI is fixed for the life of a 30-year fixed-rate Delaware mortgage — but the taxes, insurance, and mortgage insurance portions can change. The most common reasons your monthly payment increased: (1) Delaware property taxes were reassessed or millage rates went up; (2) your homeowners insurance renewal premium came in higher than the prior year; (3) an escrow shortage from underestimated taxes or insurance is being spread over the next 12 months; or (4) you’re new to the loan and the lender’s initial escrow estimate was lower than what’s actually being collected by the county or insurance company. Your annual escrow analysis statement explains the change line by line.
How does mortgage insurance affect my Delaware PITI payment?
Mortgage insurance (MI) gets added on top of PITI as a fifth piece of your monthly payment whenever the loan program requires it. FHA loans charge upfront MIP at closing plus monthly MIP for the life of the loan in most cases. USDA charges an upfront guarantee fee plus a monthly annual fee. Conventional loans require PMI when your down payment is less than 20%, and PMI drops off automatically at 78% LTV (or by request at 80% LTV) under the federal Homeowners Protection Act. VA loans skip mortgage insurance entirely — VA charges a one-time funding fee at closing instead, with no monthly MI cost. The MI premium amount varies by program, credit score, LTV, and loan amount, so two Delaware buyers using the same program can have different MI rates.
Can I use gift funds for the down payment without affecting my PITI?
Yes — gift funds reduce your loan amount the same way your own savings would, which lowers your principal and lowers your monthly P&I payment. Most loan programs allow gift funds from family members for the down payment, and FHA allows gift funds for the entire down payment plus closing costs. The gift must be properly documented with a gift letter, source of funds, and paper trail showing the transfer. The gift itself doesn’t add anything to your PITI — but a larger down payment may reduce or eliminate mortgage insurance, which directly lowers your monthly payment. On a conventional loan, getting your down payment to 20% eliminates PMI entirely, which can save $100–$300+ per month depending on the loan size and credit profile.
Is escrow required on every Delaware mortgage?
Not always. Escrow for taxes and insurance is required on FHA, USDA, and most VA loans regardless of down payment. On conventional loans, escrow is required when your down payment is less than 20%, but you can typically waive escrow with 20% or more down (some lenders charge a small rate adjustment for waiving escrow). On DSHA loans, escrow is required because the underlying first mortgage is typically FHA, VA, USDA, or Conventional with less than 20% down. If you waive escrow, you become responsible for paying property taxes and homeowners insurance directly — which means budgeting carefully for the lump-sum tax bill and the annual insurance premium so you don’t fall behind.
What happens to my PITI if I refinance my Delaware mortgage?
Refinancing replaces your current mortgage with a new one, which resets the entire PITI calculation. Your new P&I depends on the new loan amount, new interest rate, and new term you select. Your taxes and insurance escrow gets recalculated based on current Delaware county tax bills and your current insurance premium. If you’re refinancing from FHA to conventional and your new LTV is below 80%, you eliminate the monthly MIP from your old FHA loan and don’t replace it with PMI on the new conventional loan — that single change can drop your monthly payment by $100–$300 or more depending on loan size. Refinancing also resets your amortization schedule, so you’re back at the front-loaded-with-interest stage on the new loan. For most Delaware borrowers, the math works out when current rates are at least 0.5%–0.75% lower than your existing rate, but the right answer depends on your individual situation.
Will making one extra mortgage payment a year really save me 5–7 years on a 30-year loan?
Yes, in most cases — but the exact savings depend on your interest rate and how early in the loan you start making the extra payments. The earlier you start, the bigger the benefit because you’re attacking the front-loaded interest portion of your amortization schedule. On a typical 30-year fixed loan at current Delaware market rates, paying an extra 1/12 of your monthly P&I every month (effectively one extra payment per year) shaves roughly 5–7 years off the loan term and saves tens of thousands in interest. The extra MUST be applied directly to principal — write “apply to principal” on the check or specify it in your online payment. If your servicer applies the extra to next month’s payment instead of principal, you get no benefit. Bi-weekly payments accomplish the same thing if your servicer applies them as paid (some servicers don’t, which kills the benefit).
How much higher is my PITI in Wilmington versus suburban New Castle County?
Wilmington has higher property taxes than the surrounding New Castle County suburbs because of city-level assessments on top of the county and school district rates. For a similarly-priced home, the Wilmington PITI typically runs noticeably higher than the same home in Newark, Bear, or Middletown — the difference is in the T (taxes) portion, not the P&I or insurance portions. Wilmington also has a city-level transfer tax that affects closing costs (separate issue from monthly PITI, but worth knowing). When you’re shopping across New Castle County, ask for PITI estimates on each candidate property rather than assuming the payment will be the same just because the home prices are close.
Does my PITI count toward my mortgage interest tax deduction?
Only the I (interest) and T (property taxes) portions of your PITI may be deductible on your federal income tax return if you itemize deductions, subject to current tax law limits. The principal portion is not deductible — it’s paying down debt, not an expense. The insurance portion is not deductible (mortgage insurance was deductible in some past years but treatment has changed; check current tax law). The State and Local Tax (SALT) deduction is currently capped at $10,000 combined federal limit, which can affect Delaware homeowners with higher property taxes. This is general information only — talk to a tax professional about your specific situation.
Does PITI include flood insurance in Delaware?
Standard homeowners insurance does NOT cover flood damage, and standard homeowners insurance is what’s included in the I of PITI. If your Delaware home is in a FEMA-designated Special Flood Hazard Area — common in coastal Sussex County (Lewes, Rehoboth, Bethany, Fenwick), parts of Wilmington along the Christina and Brandywine rivers, and some low-lying inland areas — your lender will require a separate flood insurance policy in addition to homeowners insurance. When flood insurance is required, the monthly flood premium IS escrowed and added to your PITI alongside homeowners insurance — so your total payment becomes PITI + MI + flood. Flood insurance in Delaware coastal zones can run $700–$3,000+ per year depending on elevation, flood zone, and coverage limits, so it can meaningfully change your monthly payment. Always check the FEMA flood zone before you write an offer on a Delaware property near water.
What is PITIA and how is it different from PITI?
PITIA stands for Principal, Interest, Taxes, Insurance, and Association fees — it’s PITI plus your monthly HOA dues. The distinction matters because lenders use PITIA (not just PITI) when calculating your debt-to-income ratio for qualifying. If you’re buying a Delaware property in a community with HOA fees — common in Bear, Middletown, Sussex County beach communities, and most condo developments — the HOA dues count against your qualifying ratios even though they aren’t paid through the mortgage escrow. Your mortgage payment shows PITI; your total housing cost for affordability purposes is PITIA. When you call for a pre-approval, always disclose any HOA fees on properties you’re considering so the loan officer can run the math on the right number.
When do Delaware counties reassess property taxes — and how does that affect my PITI?
Delaware completed its first comprehensive countywide property reassessment in decades in 2023–2024 (New Castle, Kent, and Sussex counties were all reassessed under court order following a 2020 ruling). Going forward, Delaware counties have committed to more regular reassessment cycles. When your assessment changes, your annual property tax bill changes — and your lender’s escrow analysis (typically run once a year on the anniversary of your loan) will adjust your monthly tax escrow up or down to match. If your taxes go up significantly, you may also see a one-time escrow shortage spread over the next 12 months on top of the new higher monthly amount, which makes the payment increase feel sharper. Your annual escrow analysis statement explains the change in detail. If you receive a reassessment notice that seems wrong, Delaware counties allow assessment appeals — contact your county assessor’s office for the appeal deadline and process.

About the Author — John R. Thomas
Branch Manager & Mortgage Loan Officer, Primary Residential Mortgage, Inc.
NMLS #38783 20+ Years Mortgage Experience DSHA Approved Lender Author
John R. Thomas has spent over 20 years helping Delaware homebuyers understand exactly how their mortgage payment is structured before they close — because the buyers who understand PITI before signing the contract are the ones who don’t get surprised by escrow shortages, MI costs, or payment increases later. As Branch Manager of the Primary Residential Mortgage office at 248 E Chestnut Hill Rd in Newark, John has personally helped over 3,000 Delaware buyers close on their homes across FHA, VA, USDA, Conventional, Jumbo, and DSHA loan programs.
John holds a BS in Physics Education from the University of Delaware and an MS in Curriculum and Instruction from Delaware State University — and that teaching background is what shapes the way he explains mortgages: layered, clear, and grounded in actual examples. He’s the author of Your Guide to Buying Your First Home in Delaware (ISBN 0557349826) and the host of the long-running Delaware First-Time Home Buyer Seminar, where the PITI walkthrough on this page is taught live. Verify John’s NMLS license on NMLS Consumer Access ?
Contact John Thomas
Office: 248 E Chestnut Hill Rd, Newark, DE 19713
Phone: 302-703-0727
Email: JohnThomasTeam@primeres.com
Schedule: Schedule Appointment
YouTube: @Delawaremortgage
Google: See John Thomas Team on Google for reviews, directions, and local office information.
Licensing: Licensed in 17 states (AL, DC, DE, FL, GA, IN, KS, MD, MN, MO, NC, NJ, OH, PA, SC, TN, VA). NMLS #38783.
Get Your Real Delaware PITI Payment Calculated Today
Stop guessing with online calculators. Get a real PITI estimate based on your credit score, the home you’re considering, and your actual loan program — from a Delaware loan officer who’s been doing this for 20+ years.
Sources Used for This Guide
PITI definitions and federal mortgage rules are based on authoritative sources. We update this page when programs or rules change:
- Consumer Financial Protection Bureau — What is PITI?
- HUD — FHA Single Family Mortgage Insurance
- VA Home Loans — Department of Veterans Affairs
- USDA Rural Development — Single Family Housing Programs
- Delaware State Housing Authority (DSHA) — Delaware Mortgage Program
- New Castle County — Property Assessment
- Kent County — Finance Department
- Sussex County — Finance Department
Last Updated: May 2026
Mortgage content reviewed by John R. Thomas, NMLS #38783.
John Thomas, NMLS #38783 | Primary Residential Mortgage, Inc. | 248 E Chestnut Hill Rd, Newark, DE 19713 | 302-703-0727 | delawaremortgageloans.net
Copyright © 2026 John R. Thomas, All Rights Reserved.
